

Key Takeaways
- Snowflake stock is up 55% in 2026 (through Tuesday’s close), mostly on two earnings reports that each raised its full-year product revenue guidance.
- Snowflake’s guidance looks conservative, which makes the stock worth holding and adding to even after the run.
- Product revenue growth sped up for a third straight quarter, to 37% in the July quarter, yet the full-year guide implies about 35% growth in the January quarter.
- The early-December report is the test: a January-quarter guide of about $1.65 billion or more keeps the case intact.
Snowflake (SNOW) stock is up 55% in 2026 (through Tuesday’s close), nearly tripling from its April low in the software selloff. Two earnings reports drove most of that, each with a raised full-year outlook.
AI is speeding things up
In late May, Snowflake’s first-quarter product revenue rose 34% to $1.33 billion, and it raised its full-year guide to $5.84 billion. CEO Sridhar Ramaswamy said why:
“AI continues to be a powerful tailwind for Snowflake, and Q1 marks a clear inflection point in that journey.”
He’s been right so far. In early September, second-quarter product revenue rose 37% to $1.49 billion, a third straight quarter of faster growth. And the guide rose again, to $6.07 billion.
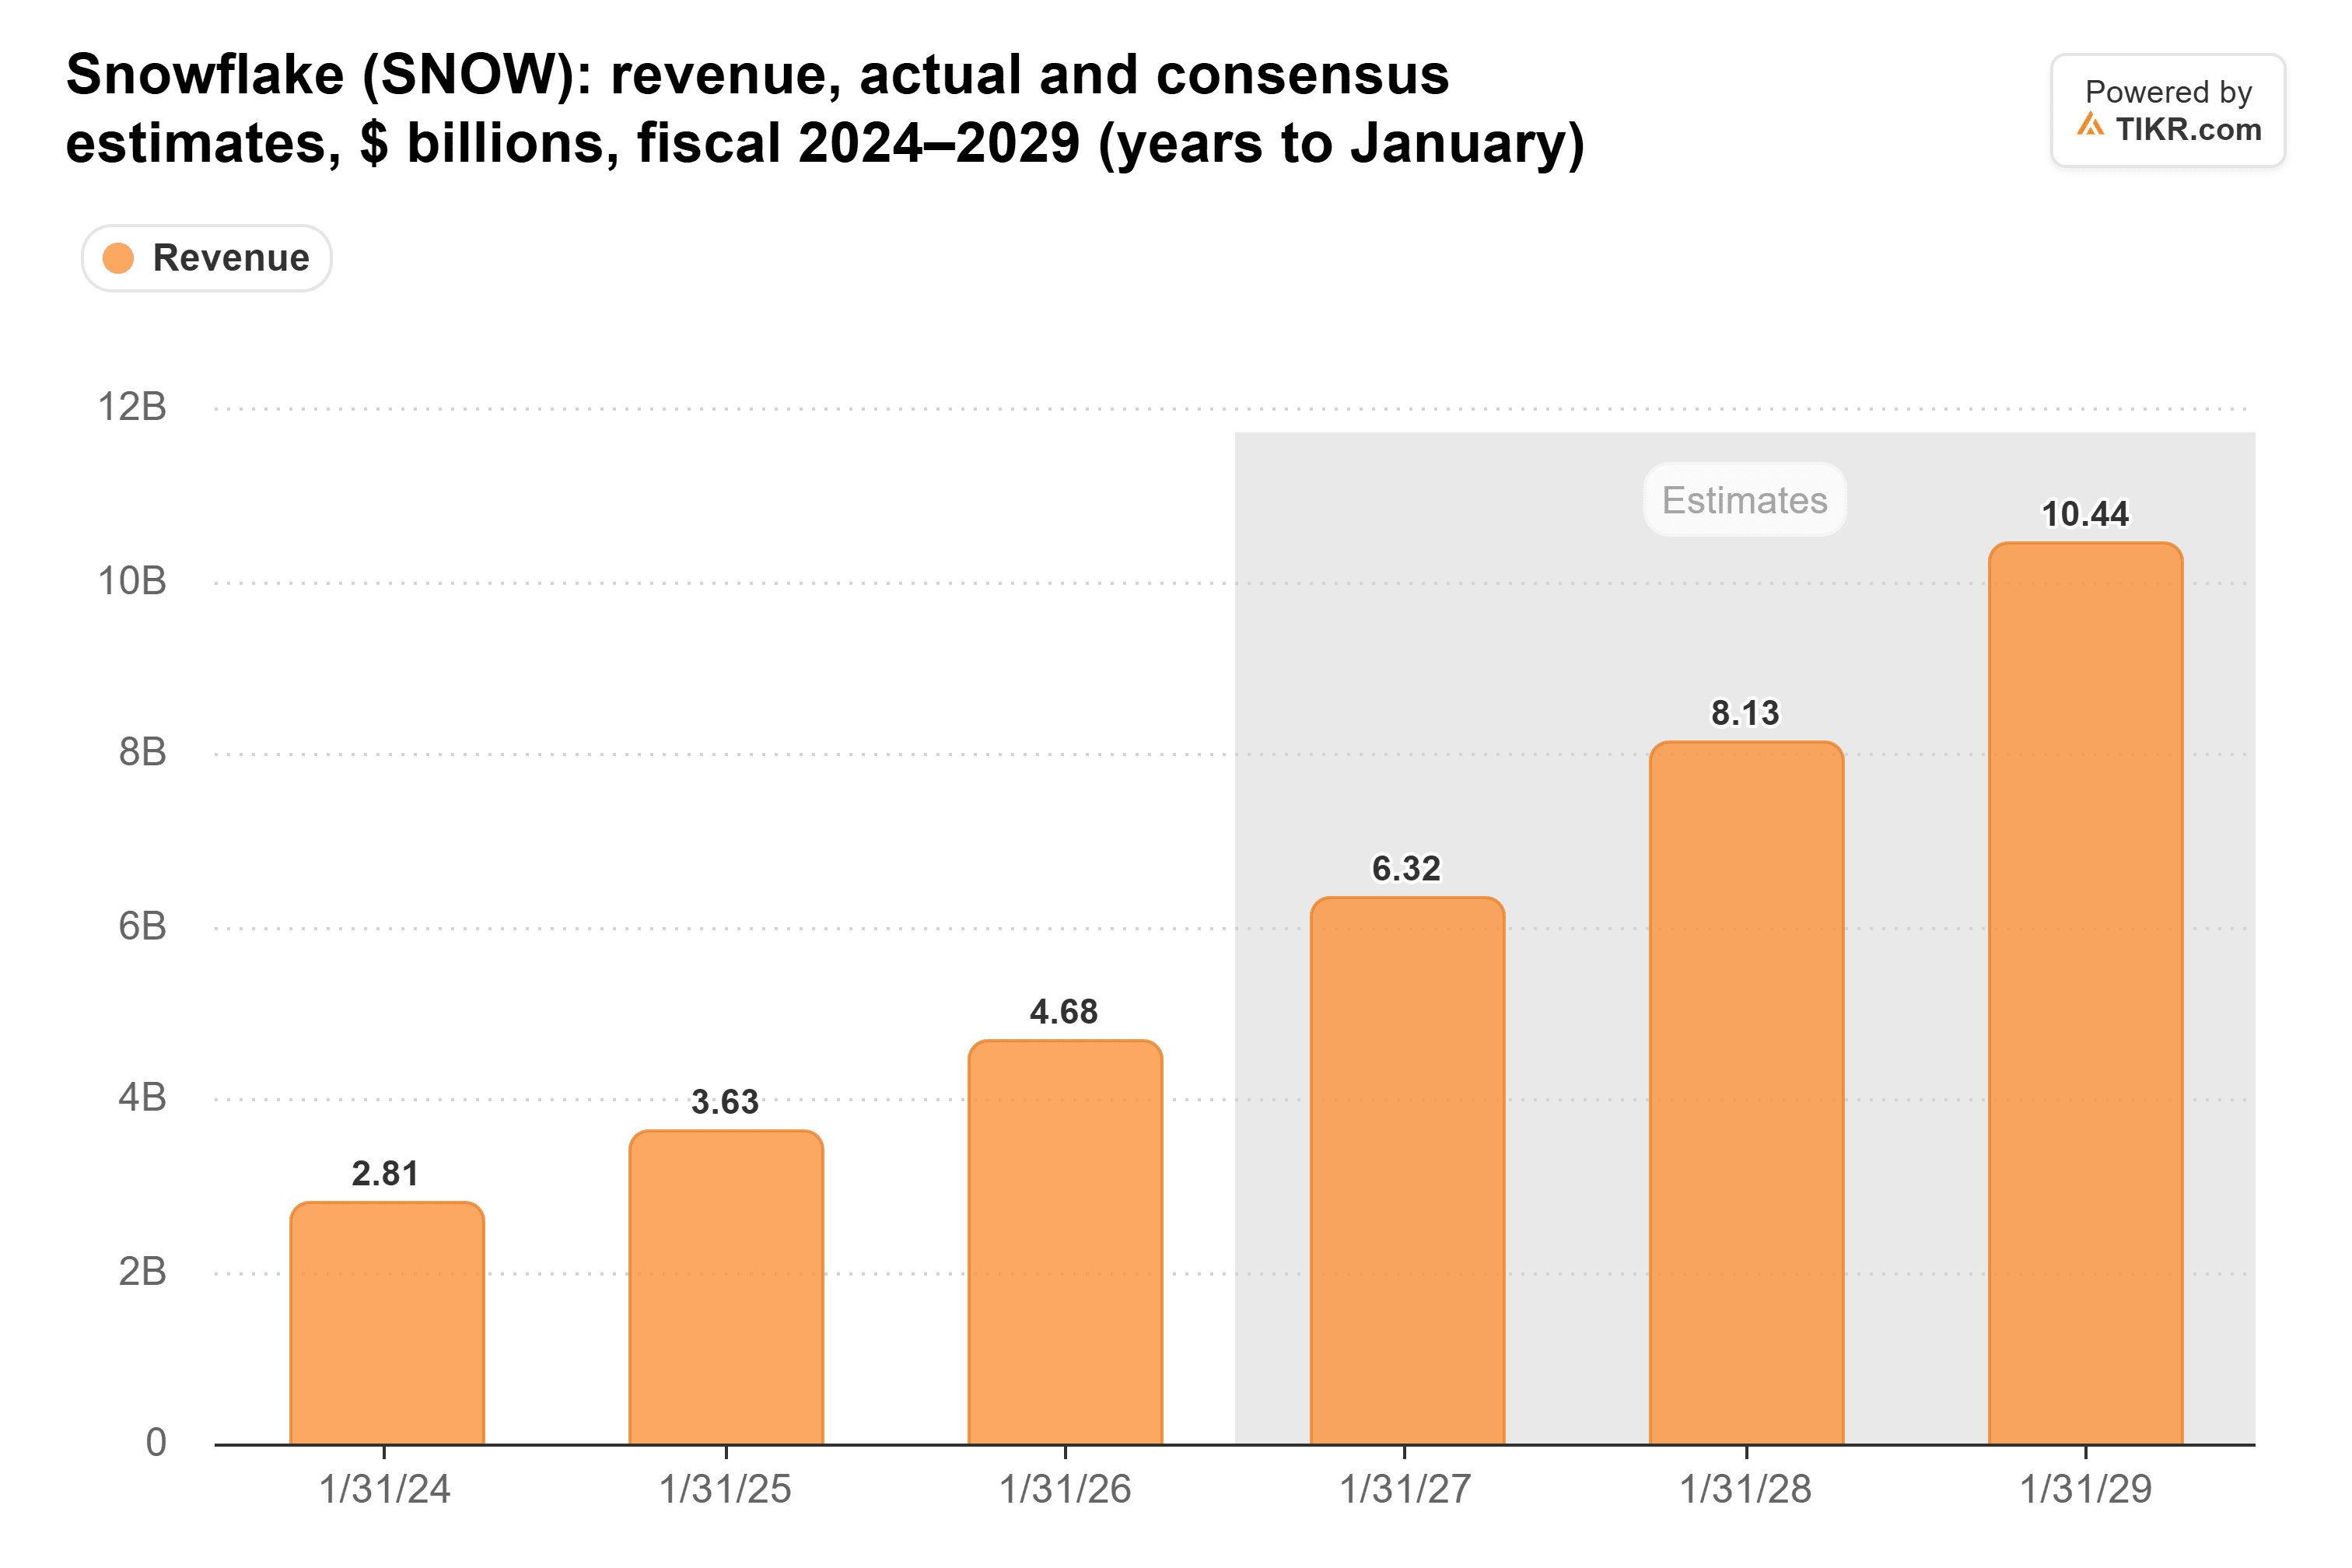
Analysts now see revenue reaching $8.13 billion in the year ending January 2028…
The guide looks beatable
Snowflake has beaten the top of its guide by more than 5% two quarters running. And CFO Brian Robins said at a Piper Sandler conference on Sept. 15 that the guide applies “a haircut” to Cortex Code, its AI coding agent, with only two quarters of data on it.
Plus: the full-year guide implies about $1.65 billion of January-quarter product revenue, roughly 35% growth, below the October quarter’s 37% to 38% guide.
That looks like a low bar.
TIKR tracks 53 analysts on Snowflake. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Snowflake, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Snowflake’s Analyst Ratings
And guidance moves this stock more than beats do: last December, Snowflake beat revenue estimates and still fell 11% on a weak fourth-quarter outlook.
Is it a buy at 12% off its high?
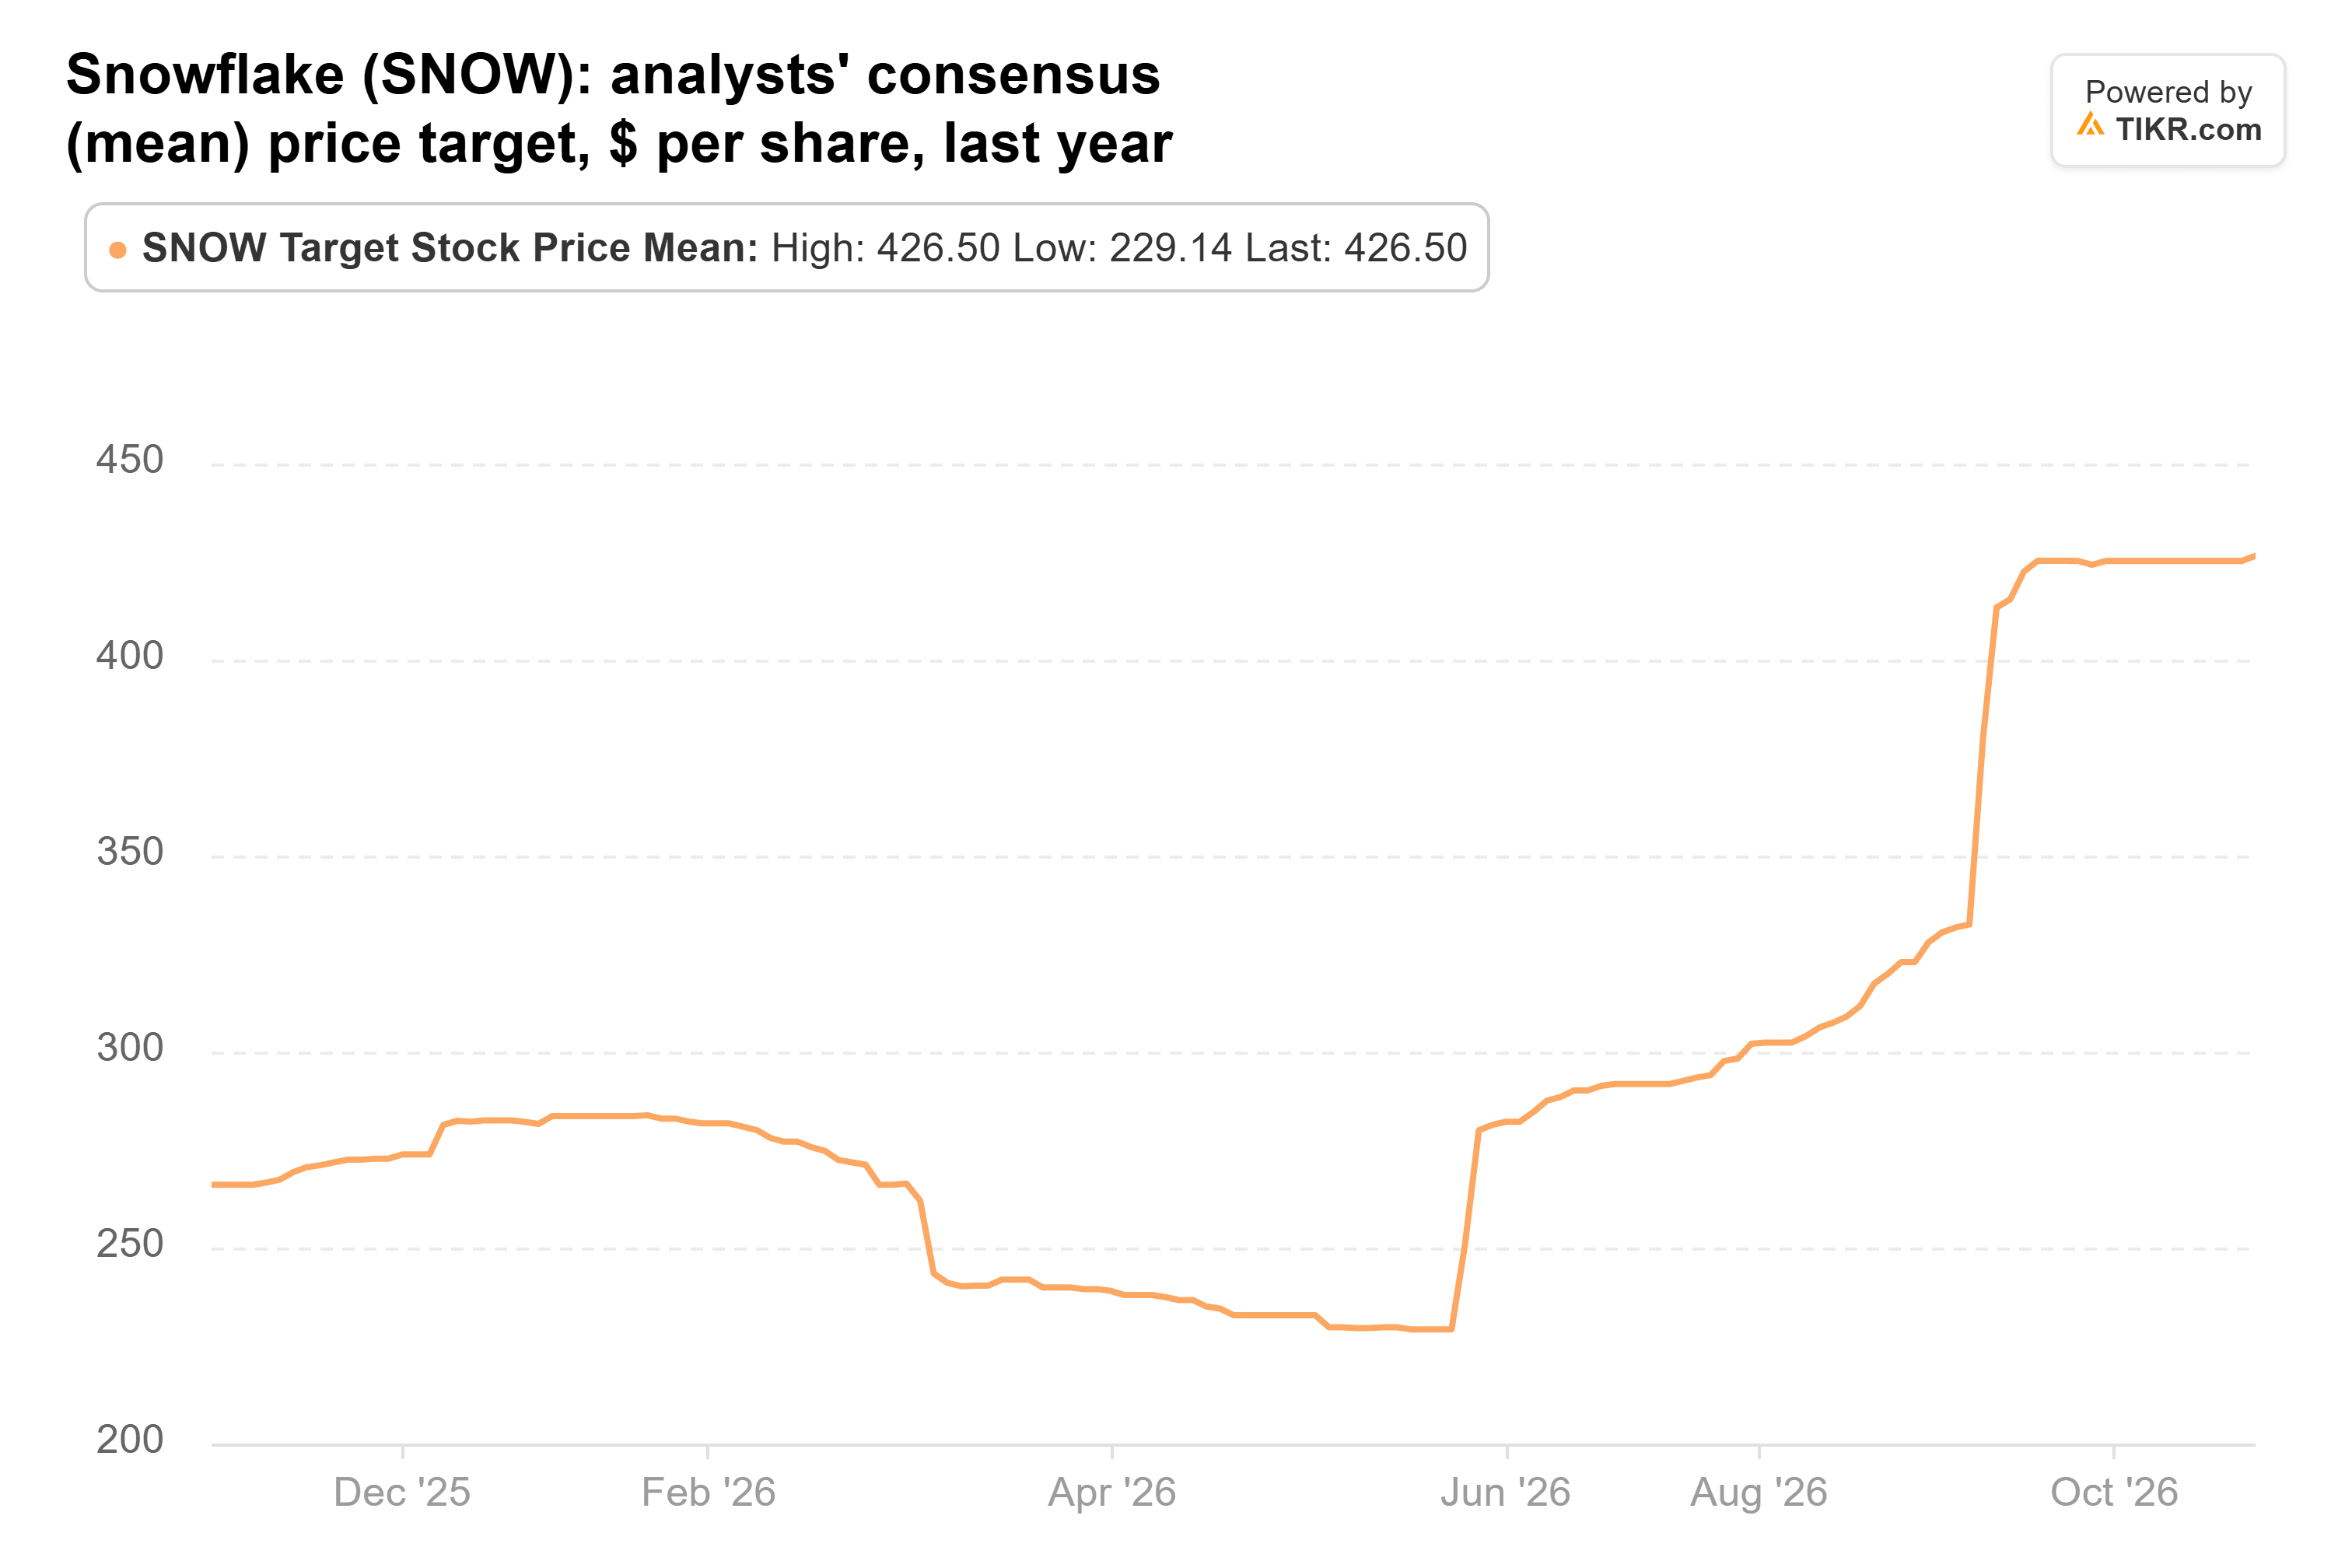
Snowflake trades at about 134x forward earnings, near its one-year average (130x) and below its three-year average (165x). The consensus target has climbed from $229 in late May to $427, about 26% above Tuesday’s close…
But Snowflake posted a $263 million GAAP operating loss in the July quarter, and its $3.75 billion of 0% convertible notes could dilute holders. The 8% drop on Oct. 16, during an AI selloff with no Snowflake news, shows how fast the premium can shrink.
My take: I wouldn’t take profits here. Snowflake keeps beating a cautious guide, and the multiple hasn’t outrun rising estimates. So I’d add on dips like Oct. 16’s.
It all hinges on early December’s report: a January-quarter guide of about $1.65 billion or more keeps the case intact. A weaker one could hit the stock like December 2025’s did.
So what is Snowflake stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Snowflake could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


