Novartis (NVS) raised its 2026 profit outlook on Tuesday, October 27, even as it booked a $1.9 billion write-down on a failed drug. Core operating income is now expected to come in flat to up low single digits at constant currencies, against a low single-digit decline before. The third-quarter release showed core EPS of $2.46, about 9% above the $2.25 Zacks consensus, while sales of $14.52 billion came in just under the $14.56 billion estimate.
The write-down follows a trial setback disclosed seven weeks ago that had already triggered a sharp selloff. What’s new is the raise: with sales guidance unchanged, it points to stronger margins, and cash flow isn’t keeping pace.
Where Novartis Found the Extra Profit
Sales grew 4% at constant currencies, while core operating income rose 10% to $6.04 billion. The core margin hit 41.6%, up 2 points. Kisqali (+37%), Kesimpta (+22%), Scemblix (+67%) and Leqvio (+63%) offset generic erosion, which CEO Vas Narasimhan called proof of “the replacement power of the business.”
Novartis left its sales outlook at low single-digit growth, so the higher profit outlook points to stronger expected margins. A lower share count also helped year-over-year EPS growth.
What September Already Cost Novartis Holders
The $1.94 billion is a partial impairment on del-desiran, the muscle-wasting drug at the center of the $12 billion Avidity deal. Novartis disclosed HARBOR’s primary-endpoint miss on September 8, four days after announcing the failed trial for heart drug pelacarsen. The Swiss-listed shares closed down 10.9%, erasing about CHF26 billion ($32 billion) in market value, according to Reuters. The ADRs fell 13.9% to $137.70, a move that also carried the pelacarsen news, which landed after the U.S. close on September 4, with markets shut for Labor Day on September 7.
The impairment wrote off roughly 26% of del-desiran’s $7.48 billion carrying value, according to the interim report, leaving about $5.5 billion on the books for a drug that missed its main goal. That balance is what’s at risk if Novartis scales the program back further. The charge is non-cash and sits outside core earnings.
TIKR Tracks 12 Analysts on Novartis. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Novartis, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Novartis’s Analyst Ratings
Cash Is Lagging the Profit Story
Free cash flow fell 18% to $5.1 billion in the third quarter, from $6.2 billion a year earlier. Over nine months, it totals $14.0 billion against $15.9 billion, a 12% drop, while core operating income slipped only 1%.
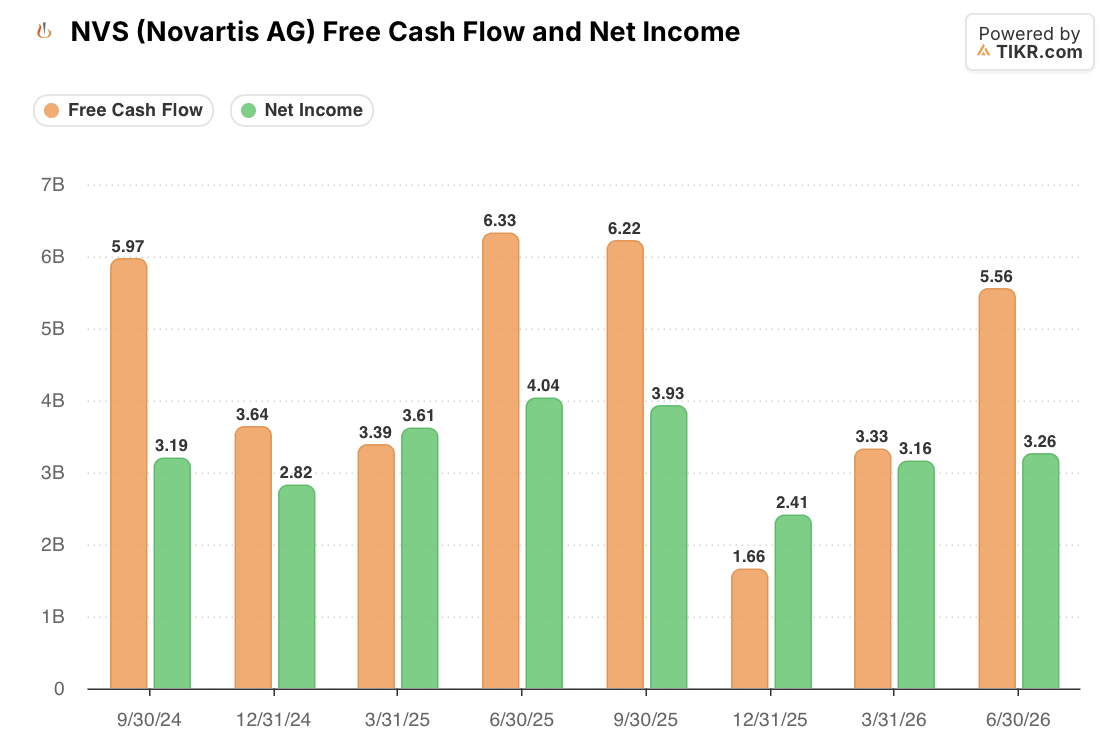
That’s softer, not broken. Cash still ran about four times reported net income this quarter, because the impairment never left the bank. But fourth-quarter 2025 free cash flow of $1.66 billion trailed net income of $2.41 billion, so another weak fourth quarter would turn this into a pattern.
What Novartis Holders Are Paying For

The stock trades at 16.4x forward earnings, above its 5-year average of 14.3x. September knocked the multiple down from near 18x, and it has only partly recovered.
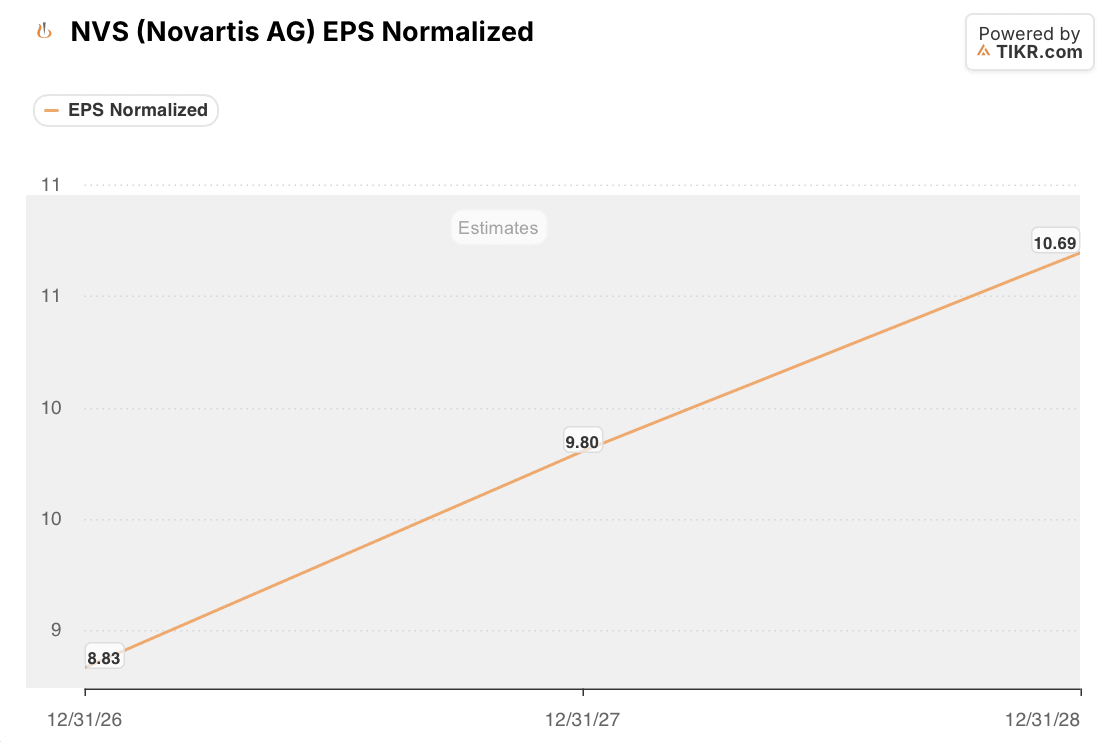
The Street expects EPS of $8.83 this year, $9.80 in 2027 and $10.69 in 2028, about 10% a year. Novartis guides to sales growth of 5% to 6% a year through 2030, so margin has to keep doing what it did this quarter. Today’s raise makes that more believable. At 16.4x, though, the price already counts on it, and the 2027 estimate needs 11% EPS growth from a company that just held its sales outlook.
So What Is Novartis Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what NVS stock could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!