Key Takeaways
- Navitas stock is up 12% in 2026 through Tuesday’s close, but it’s 73% below the high it hit in June during the AI power-chip boom.
- Buying Claros and new 800-volt designs with Nvidia and Microchip make its AI data-center pitch bigger, but quarterly revenue is still around $10 million.
- Stock sales, a Wolfspeed patent suit and a chip selloff erased most of the spring run, and revenue has to nearly triple from the third-quarter guide for the company to break even.
- At roughly 40x forward sales, the stock still prices in a ramp that hasn’t arrived, so it’s worth waiting for third-quarter results on Nov. 3 before buying.
Navitas Semiconductor (NVTS) is up 12% in 2026 (through Tuesday’s close). That looks fine until you notice it’s also down 73% from the $34 high it hit on June 3.
That round trip says a lot about the AI power-chip story. Navitas faces its next test when it reports third-quarter results after the close on Tuesday, Nov. 3.
The AI power story did the lifting
Navitas jumped 20% after its fourth-quarter beat in February. First-quarter revenue then rose 18% from the fourth quarter to $8.6 million. Investors bought the pitch: gallium nitride (GaN) and silicon carbide (SiC) chips for the 800-volt racks AI data centers are moving to. Management says Nvidia (NVDA) named Navitas a partner on that design.
Navitas used the run to sell $380.7 million of stock in May and June, at an average of $22 a share. That came on top of years of dilution…
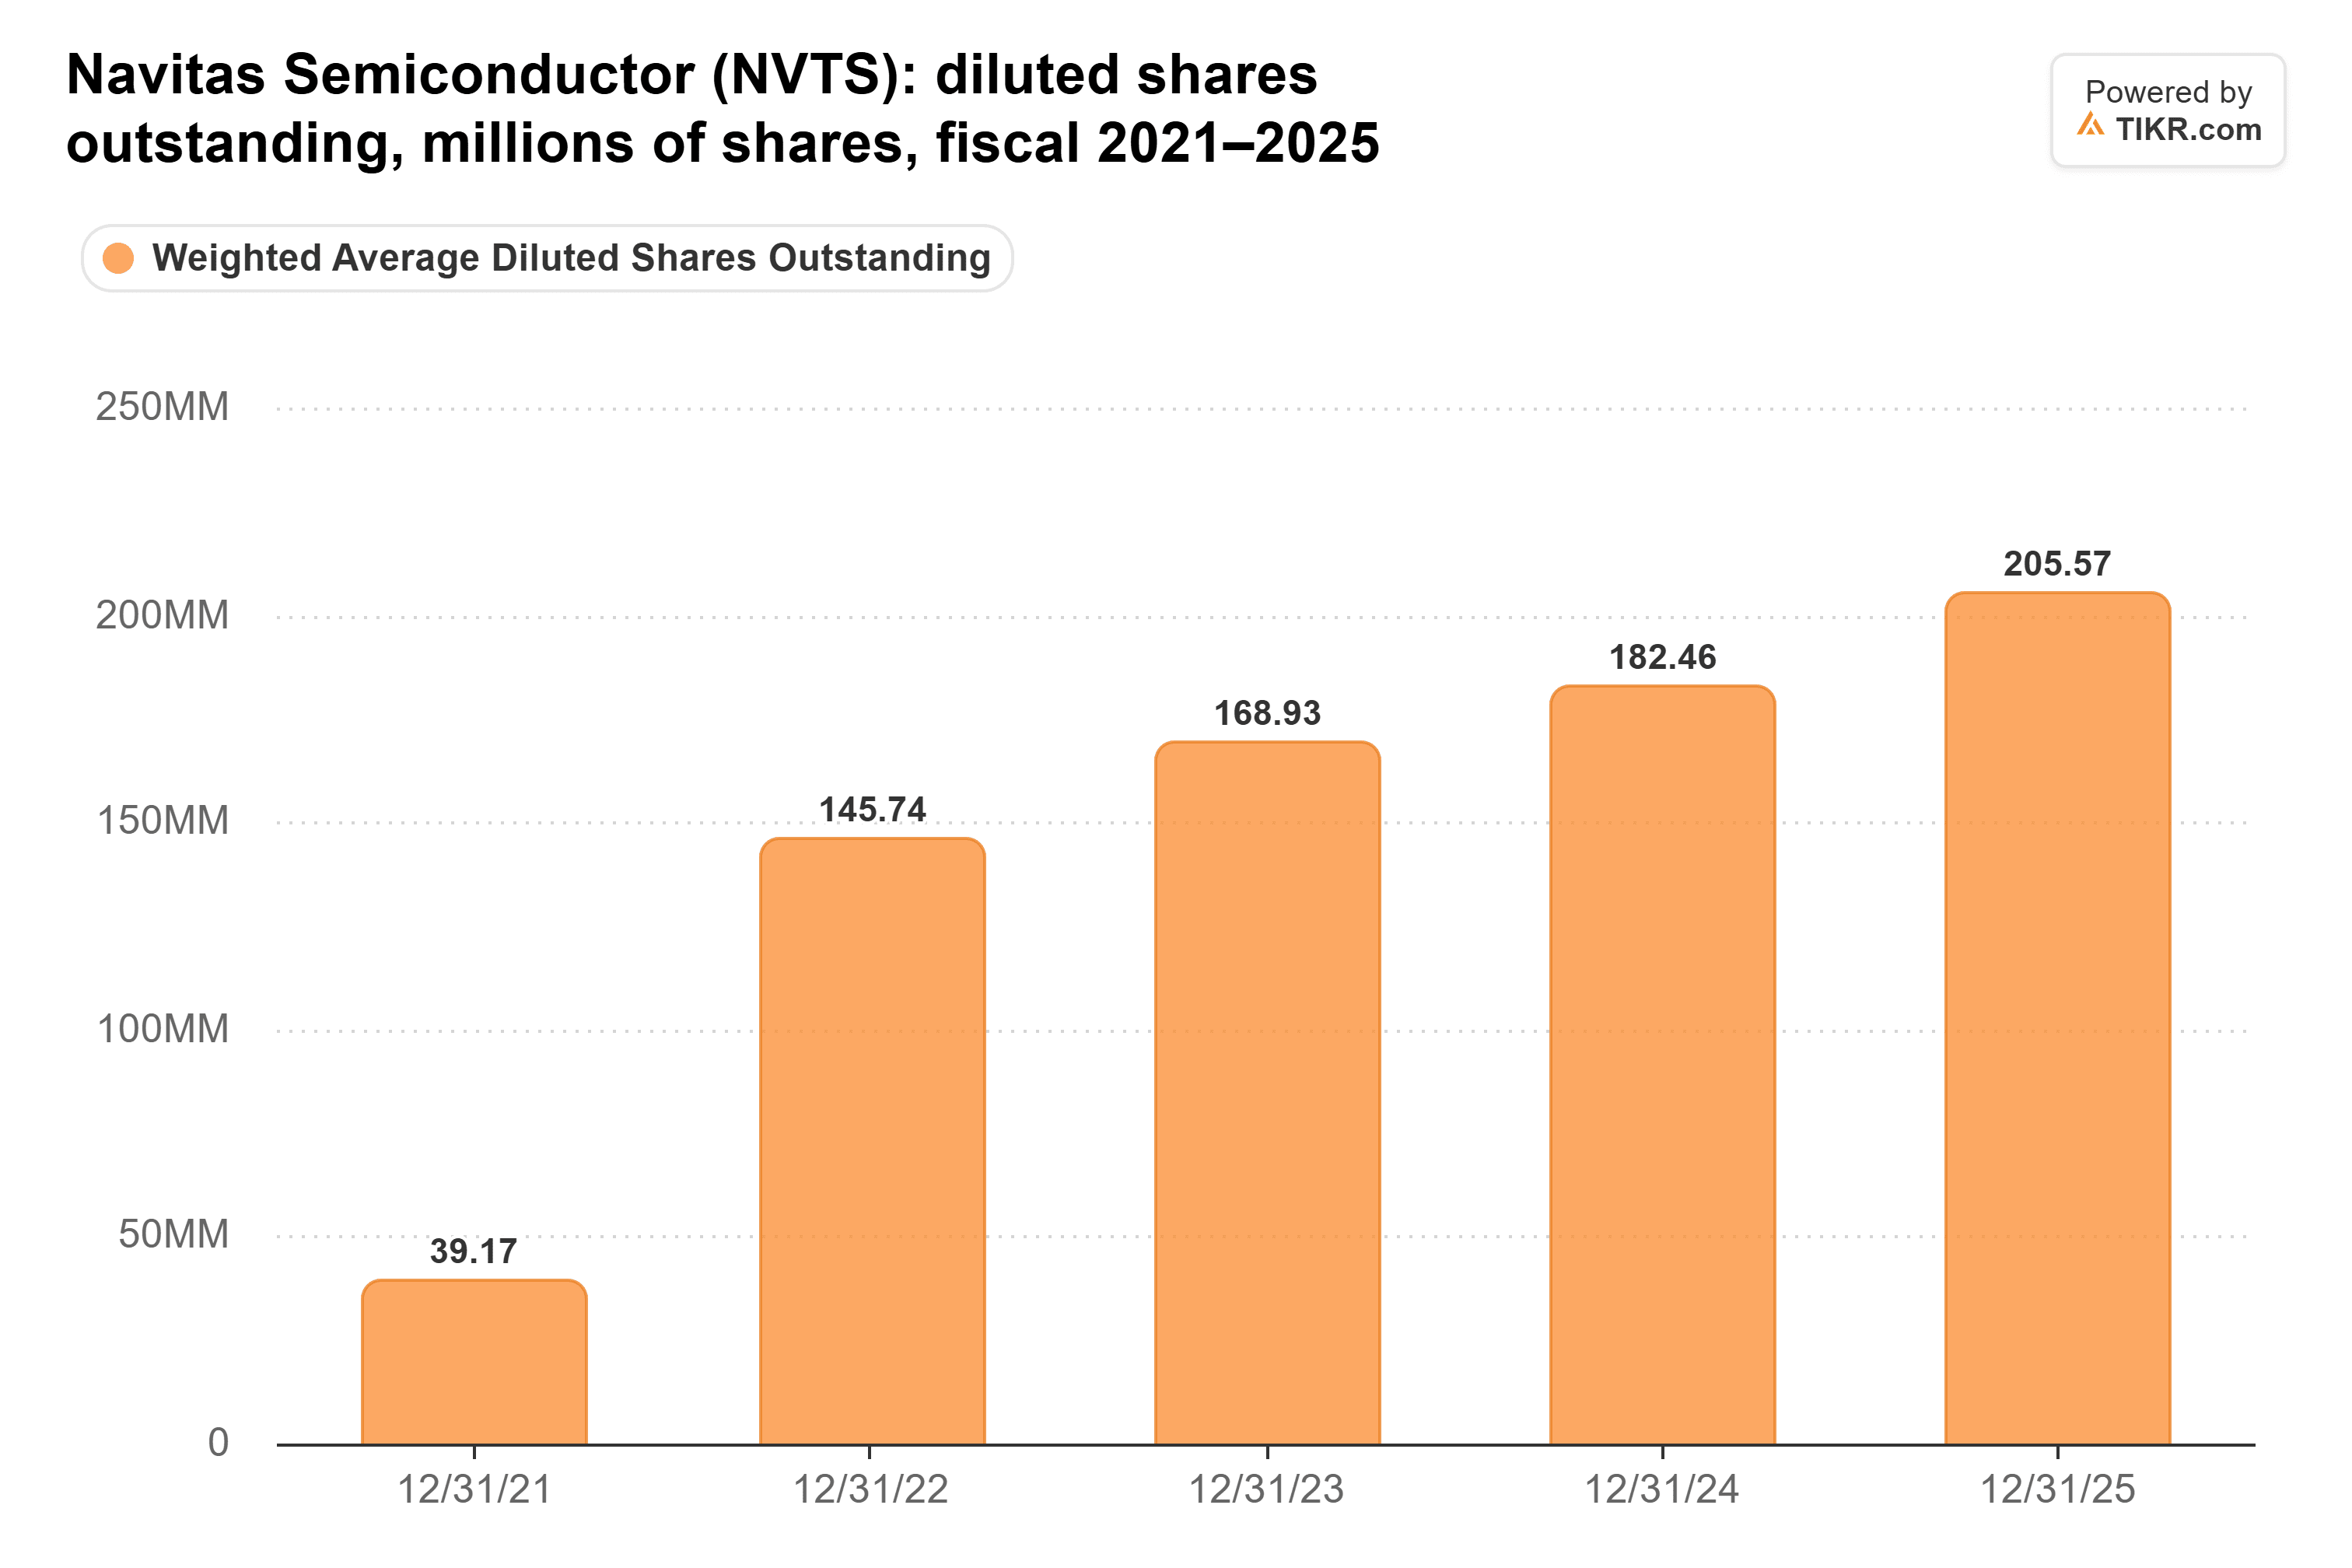
…and by June 30, 261.1 million shares were outstanding. About 6.9 million more went out later to pay for Claros.
Then in July came a patent suit from Wolfspeed (WOLF), a trade-secret suit from Renesas and a small-cap chip selloff.
TIKR tracks 8 analysts on Navitas Semiconductor. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Navitas Semiconductor, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Navitas Semiconductor’s Analyst Ratings
The business is growing again, from a low base
Revenue fell from $83.3 million in 2024 to $45.9 million in 2025 as Navitas walked away from phone chargers in China. Analysts see the climb back taking years…
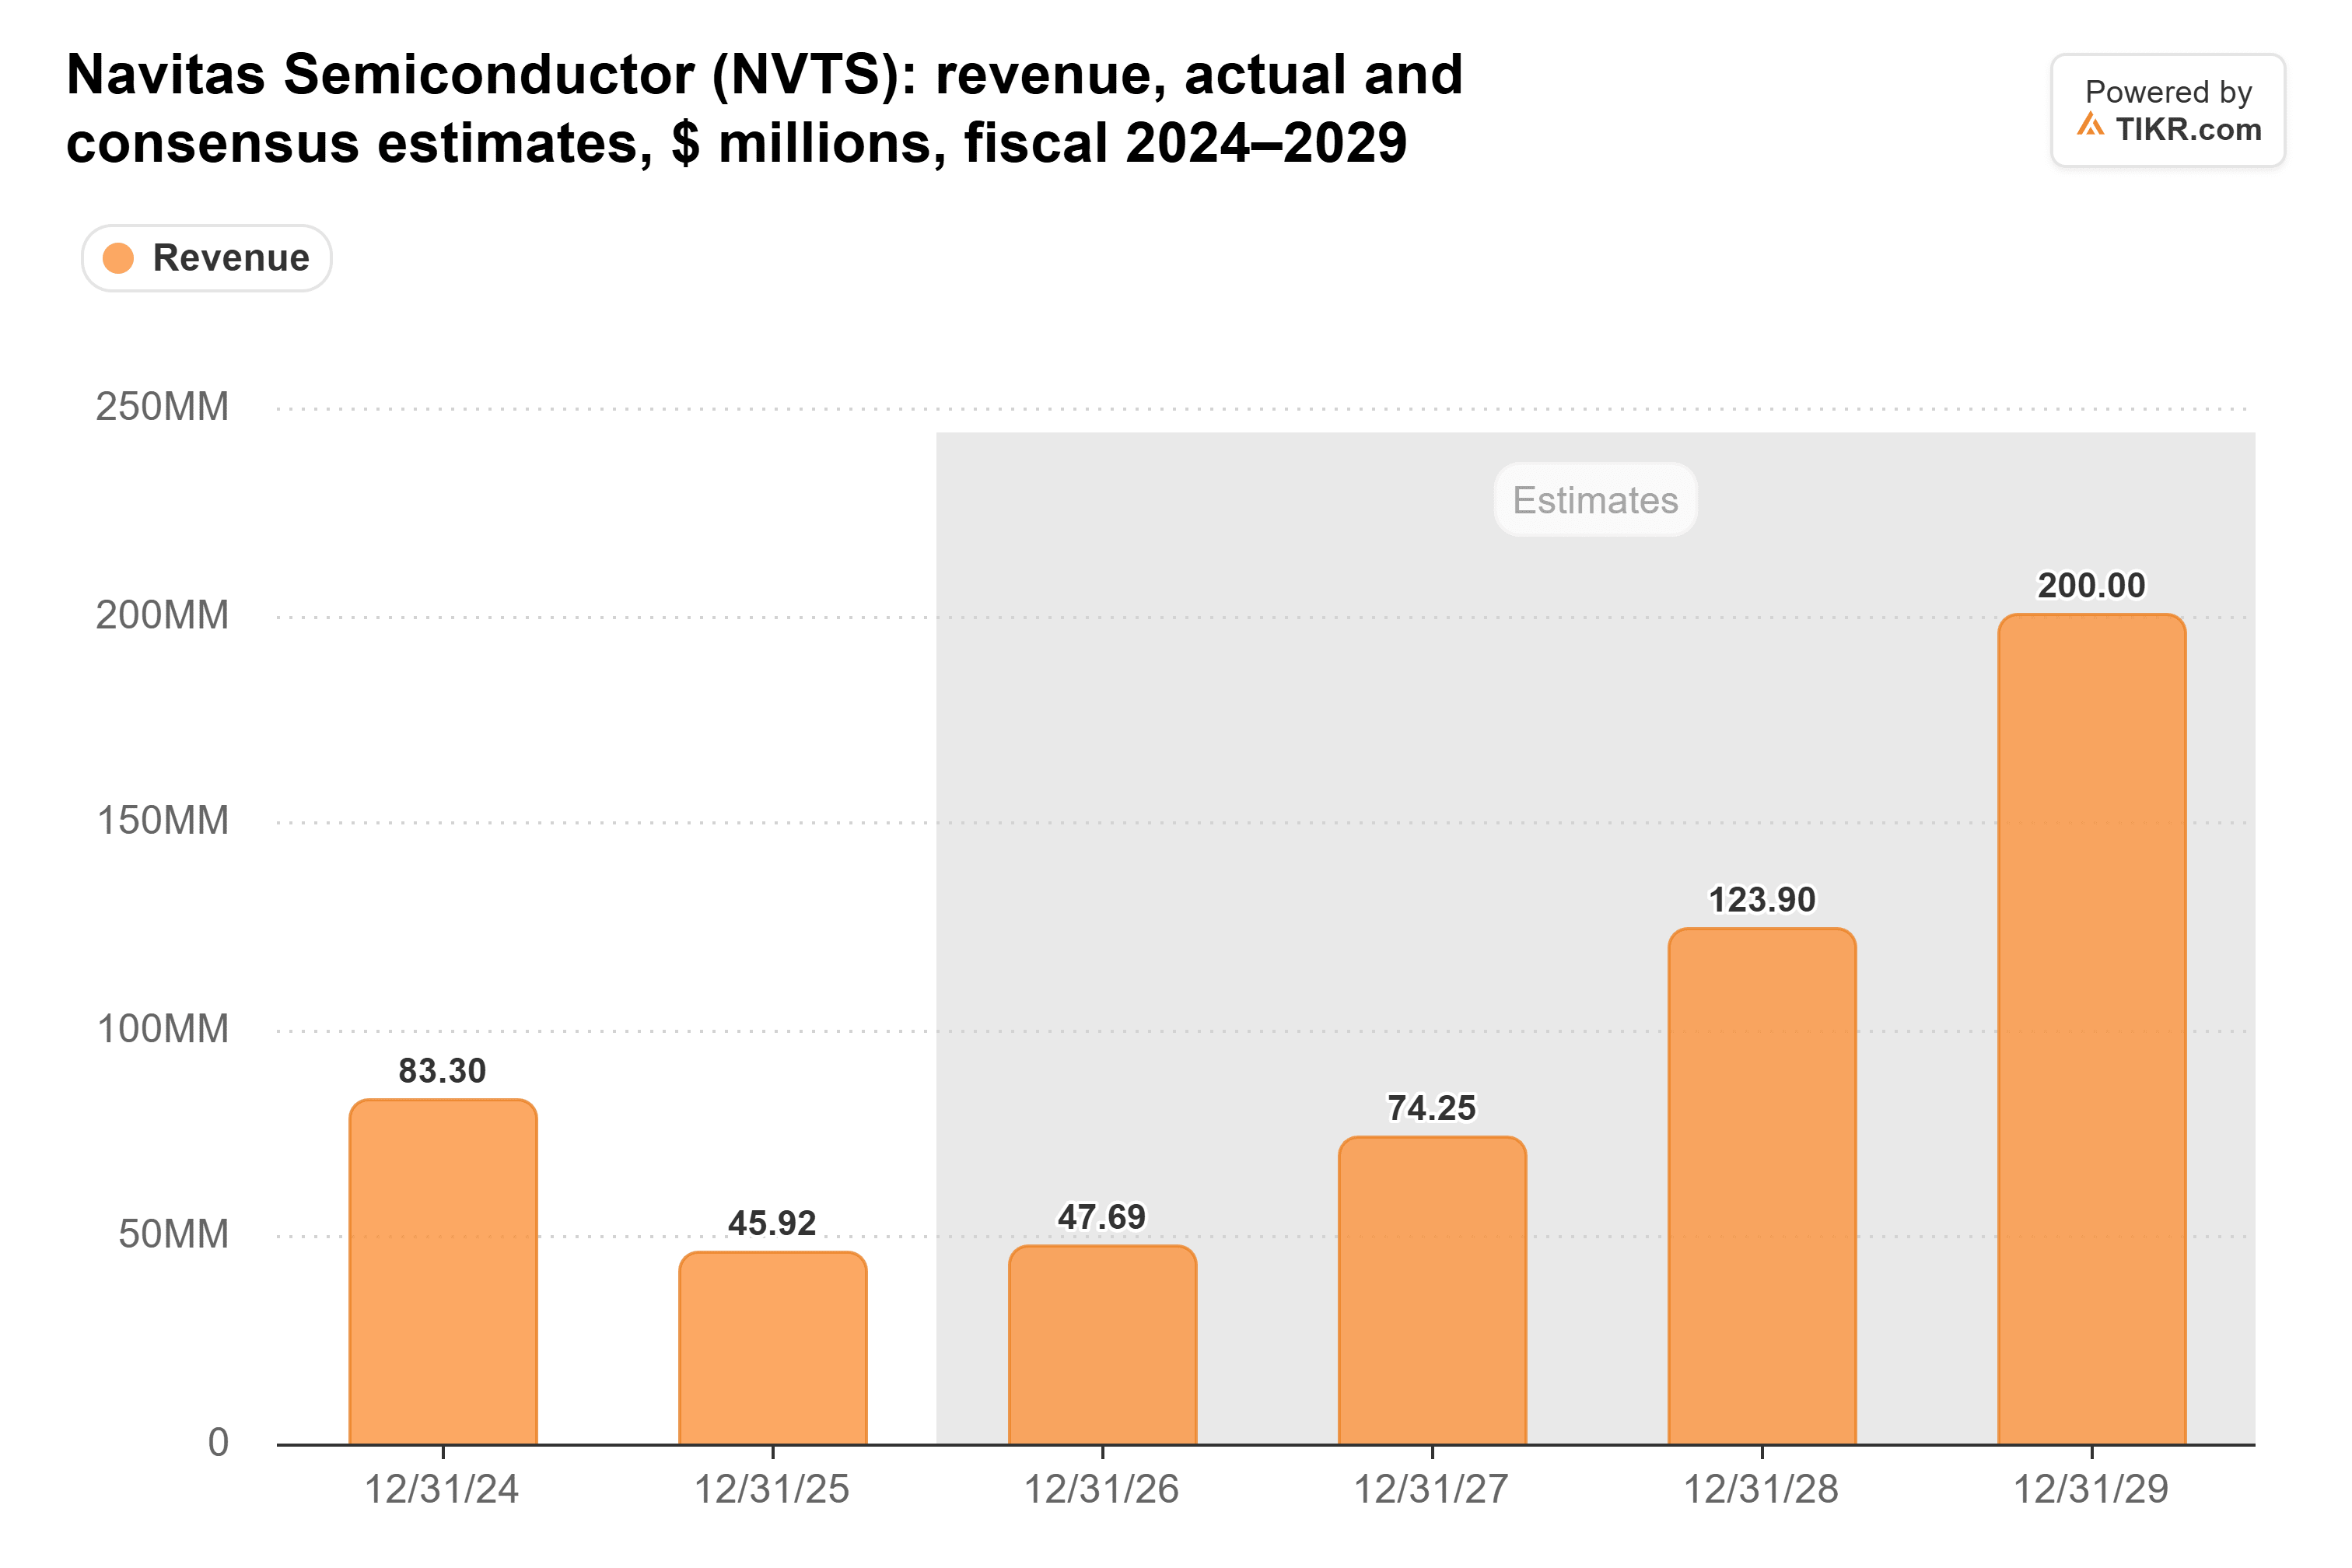
Second-quarter revenue was $10.53 million, up 22% from the first quarter and ahead of the $9.97 million analysts expected. Management guided the third quarter to $13.5 million. That’s progress. But in May, management said it needs quarterly revenue in the high $30 millions to break even, nearly triple that guide.
Claros makes the pitch bigger
On Oct. 6, Navitas closed its Claros deal, worth up to $232.8 million. Claros makes chips that deliver power right at the processor. President and CEO Chris Allexandre described the problem they’re meant to solve:
“This ‘power wall’ has restricted next-generation xPUs in megawatt-scale server racks from achieving the next wave of AI performance.”
Navitas says Claros takes the market it can serve in 2030 past $8 billion. But management doesn’t expect Claros to drive growth until around 2028 or 2029.
More news followed:
- an Army award for 10 kV SiC chips on Sept. 28
- an 800-volt reference design with Microchip (MCHP) on Oct. 5
- a 24-kilowatt power board developed with Nvidia on Oct. 12
None of it stopped a 20% slide in the past month (through Tuesday’s close). The stock moved with power-chip peers like Wolfspeed and Microchip far more than with its own news.
Priced for a ramp that hasn’t shown up
Even after a 73% fall, Navitas isn’t cheap. It traded at about 36x forward sales at Monday’s close, above its 31x three-year average. Tuesday’s 11% jump pushed that to roughly 40x…
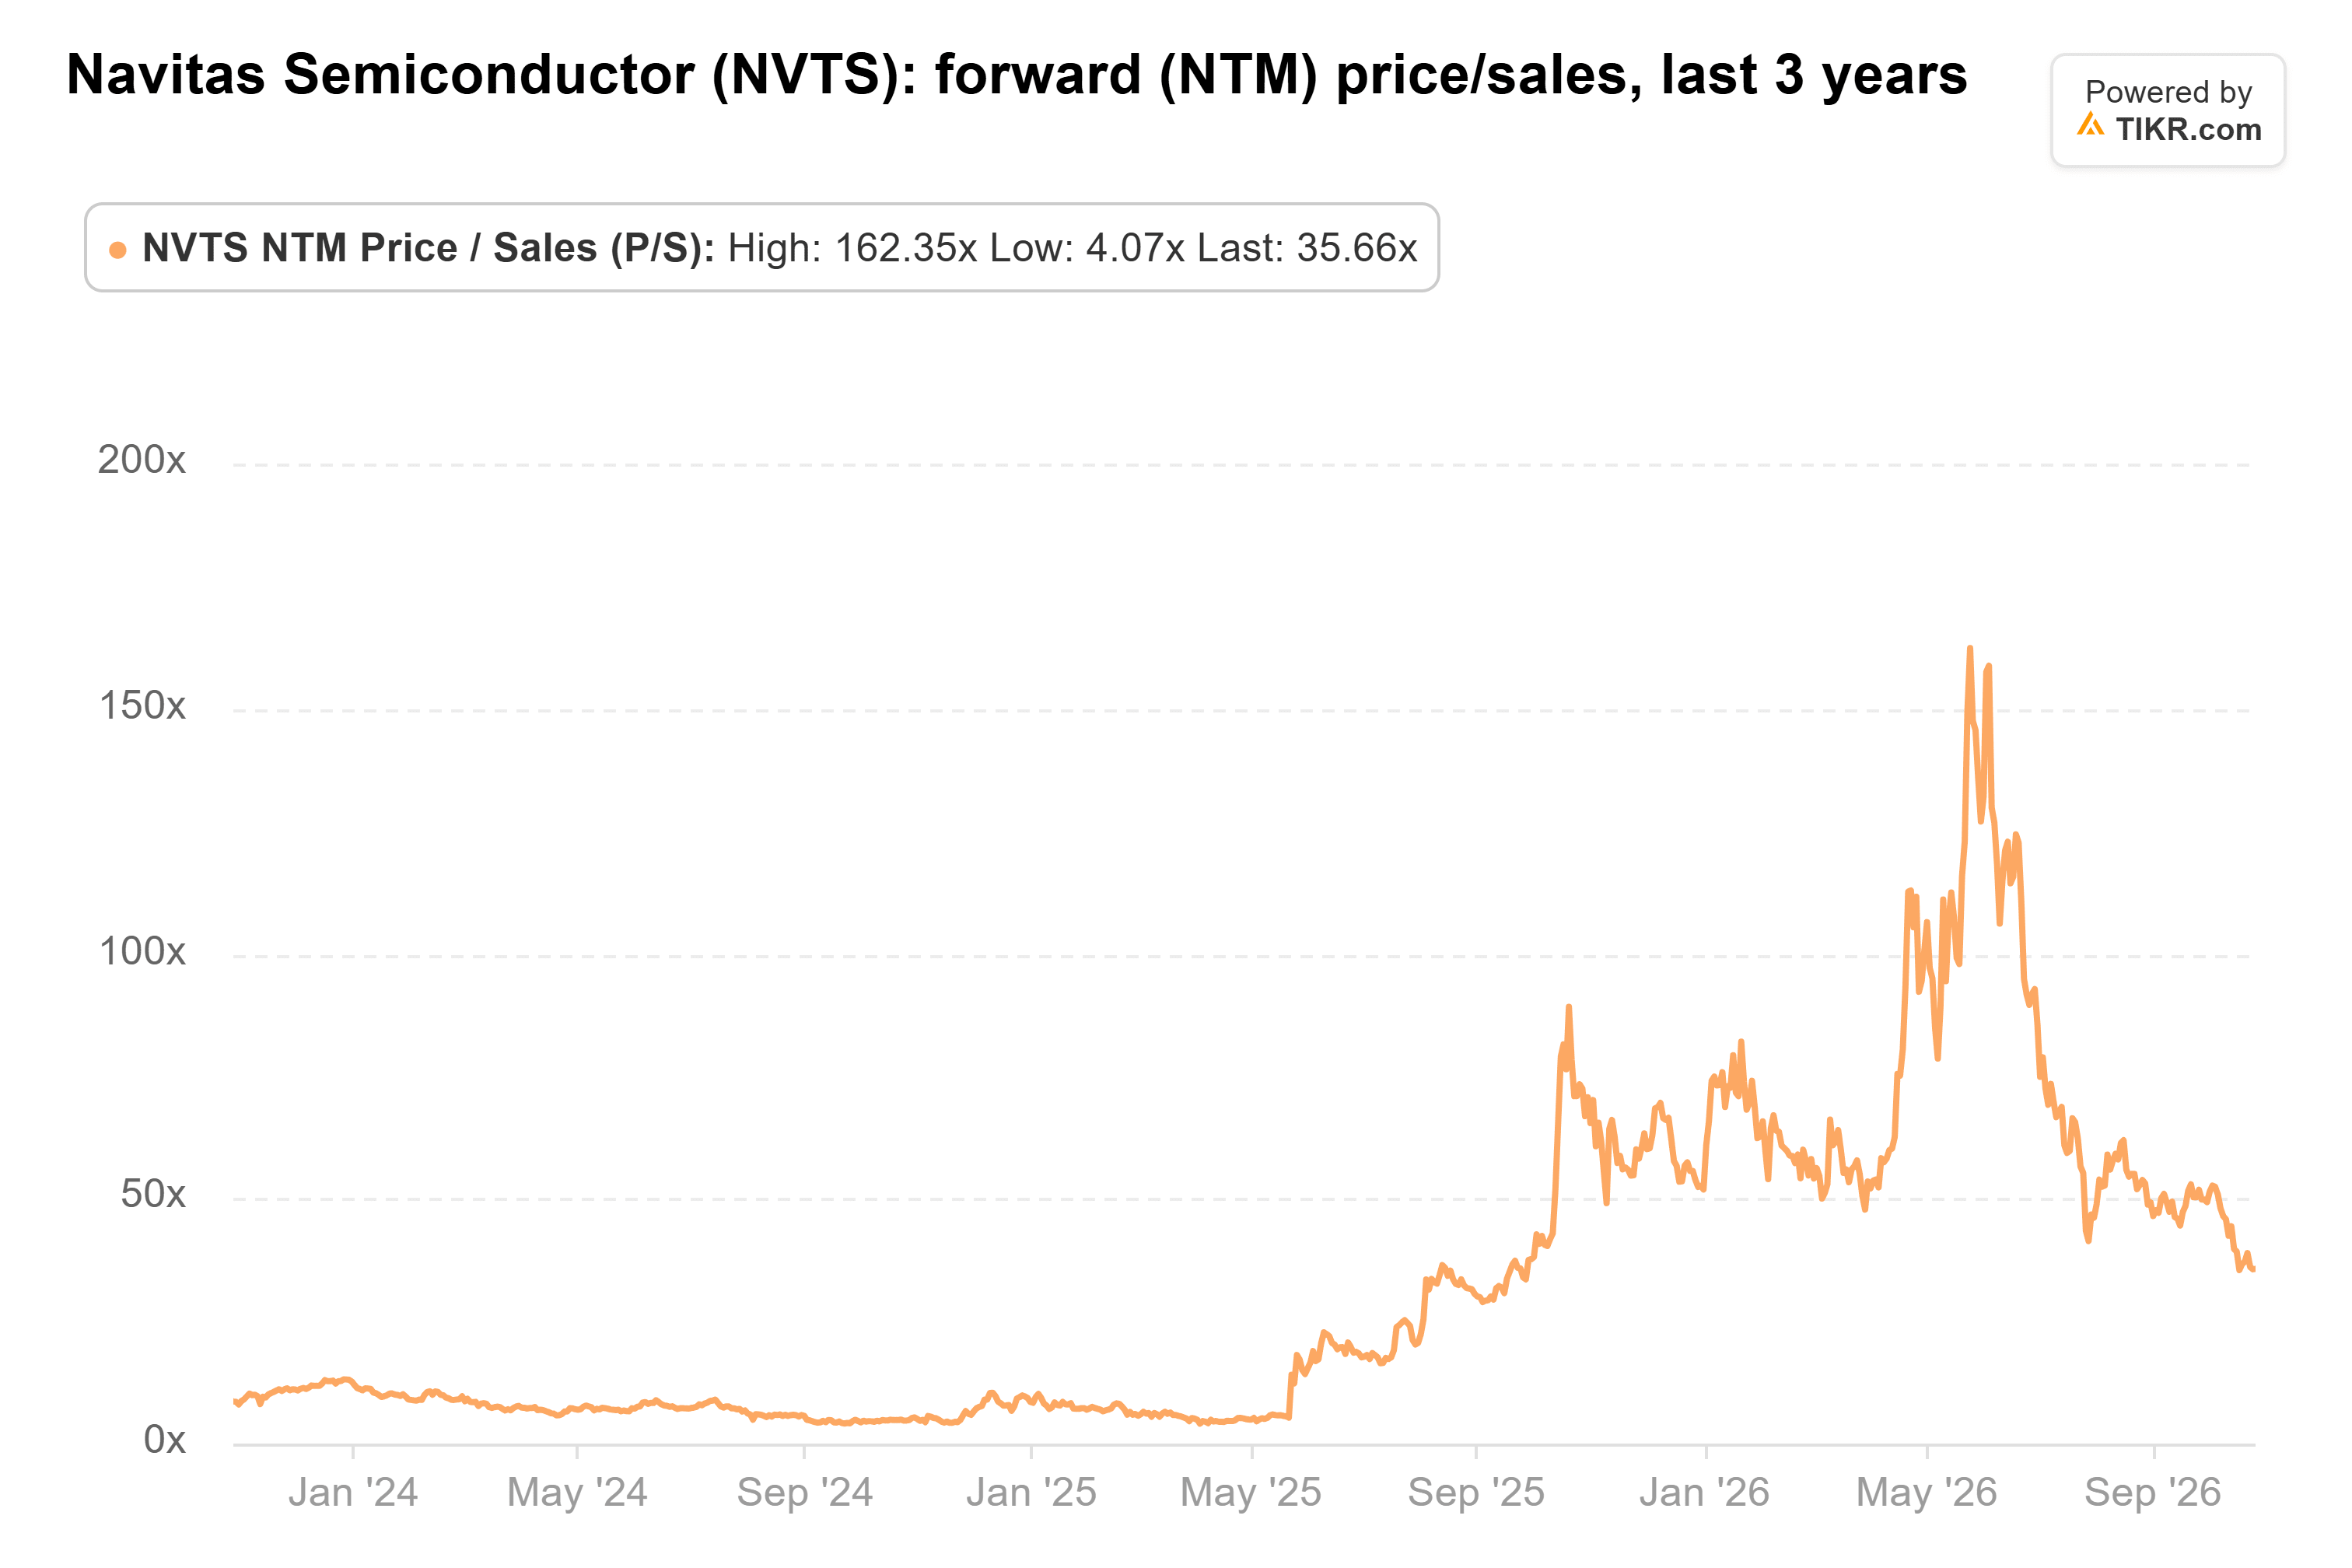
The Street is more upbeat. The $14 consensus target sits about 51% above Tuesday’s close, and even Morgan Stanley, which rates the stock Sell, has a $12.60 target.
So on Nov. 3, I’ll be watching:
- Third-quarter revenue against the $13.5 million guide
- A fourth-quarter guide of about $15 million or better, roughly what the full-year consensus implies
- How much cash is left after Claros, and whether Navitas sold more stock
My take: the “power wall” pitch is real, and Nvidia and Microchip are on board. But roughly 40x forward sales is a steep price for a company that has to nearly triple its revenue to break even. I’d wait for Nov. 3 to show the ramp is on schedule.
Of course, if the 800-volt rack programs management expects in the first half of 2027 ramp on time, today’s price could look cheap in hindsight.
So what is Navitas stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Navitas could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!