Key Takeaways
- Super Micro stock is down 32% over the past year after a revenue miss, an export-control indictment of people tied to the company and a $5.6 billion stock sale.
- The business has improved: fiscal 2026 sales rose 78% to $39.1 billion, and preliminary September-quarter sales beat its own guidance by about $4 billion.
- Growth has come at a cost: free cash flow was negative $7.0 billion in fiscal 2026, and the share count is still rising.
- At 7.5x forward earnings, the stock looks too cheap if the Nov. 3 report confirms the early numbers.
Super Micro Computer (SMCI) stock is down 32% in the past year (through Tuesday’s close), even though the company just said its September quarter came in about $4 billion above its own guidance.
Investors got burned three times
It started in November 2025, when fiscal first-quarter sales of $5.0 billion missed guidance of $6 billion to $7 billion.
The December quarter swung the other way: sales hit $12.7 billion, but one data center customer took about 63% of revenue, and gross margin sank to 6.3%.
Then in March, the Justice Department charged three people tied to Super Micro, including a co-founder. Prosecutors say they diverted about $2.5 billion of U.S. AI technology to China. The company wasn’t named as a defendant, but the stock lost a third of its value on March 20.
And in June, Super Micro raised $5.6 billion by selling common stock and mandatory convertible preferred. The common went out at $27.50 a share, a year after the company bought back stock at $40.89. (Not great timing.)
TIKR tracks 18 analysts on Super Micro Computer. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Super Micro Computer, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Super Micro Computer’s Analyst Ratings
Meanwhile, the business got much better
Gross margin climbed from 6.3% in the December quarter to 9.9% in March and 17.5% in June. That quarter, enterprise and channel customers made up half of sales.
Fiscal 2026 sales rose 78% to $39.1 billion, and new orders topped $60 billion. Management guided fiscal 2027 sales to $65 billion to $72 billion.
CEO Charles Liang credits the customer mix: “As demand accelerates, we are improving profitability through a richer enterprise customer mix.”
Still, one-time items and deals that slipped into later quarters helped June’s margin, so 17.5% isn’t the new baseline.
Then came the Oct. 20 update: estimated September-quarter sales of $18.5 billion to $19.5 billion. That’s nearly four times the year-ago quarter and well above the $15.23 billion analysts expected. The estimated 12.0% to 12.5% gross margin beat guidance, too.
And for the full year? Analysts expect $70.0 billion of fiscal 2027 revenue, near the top of management’s range.
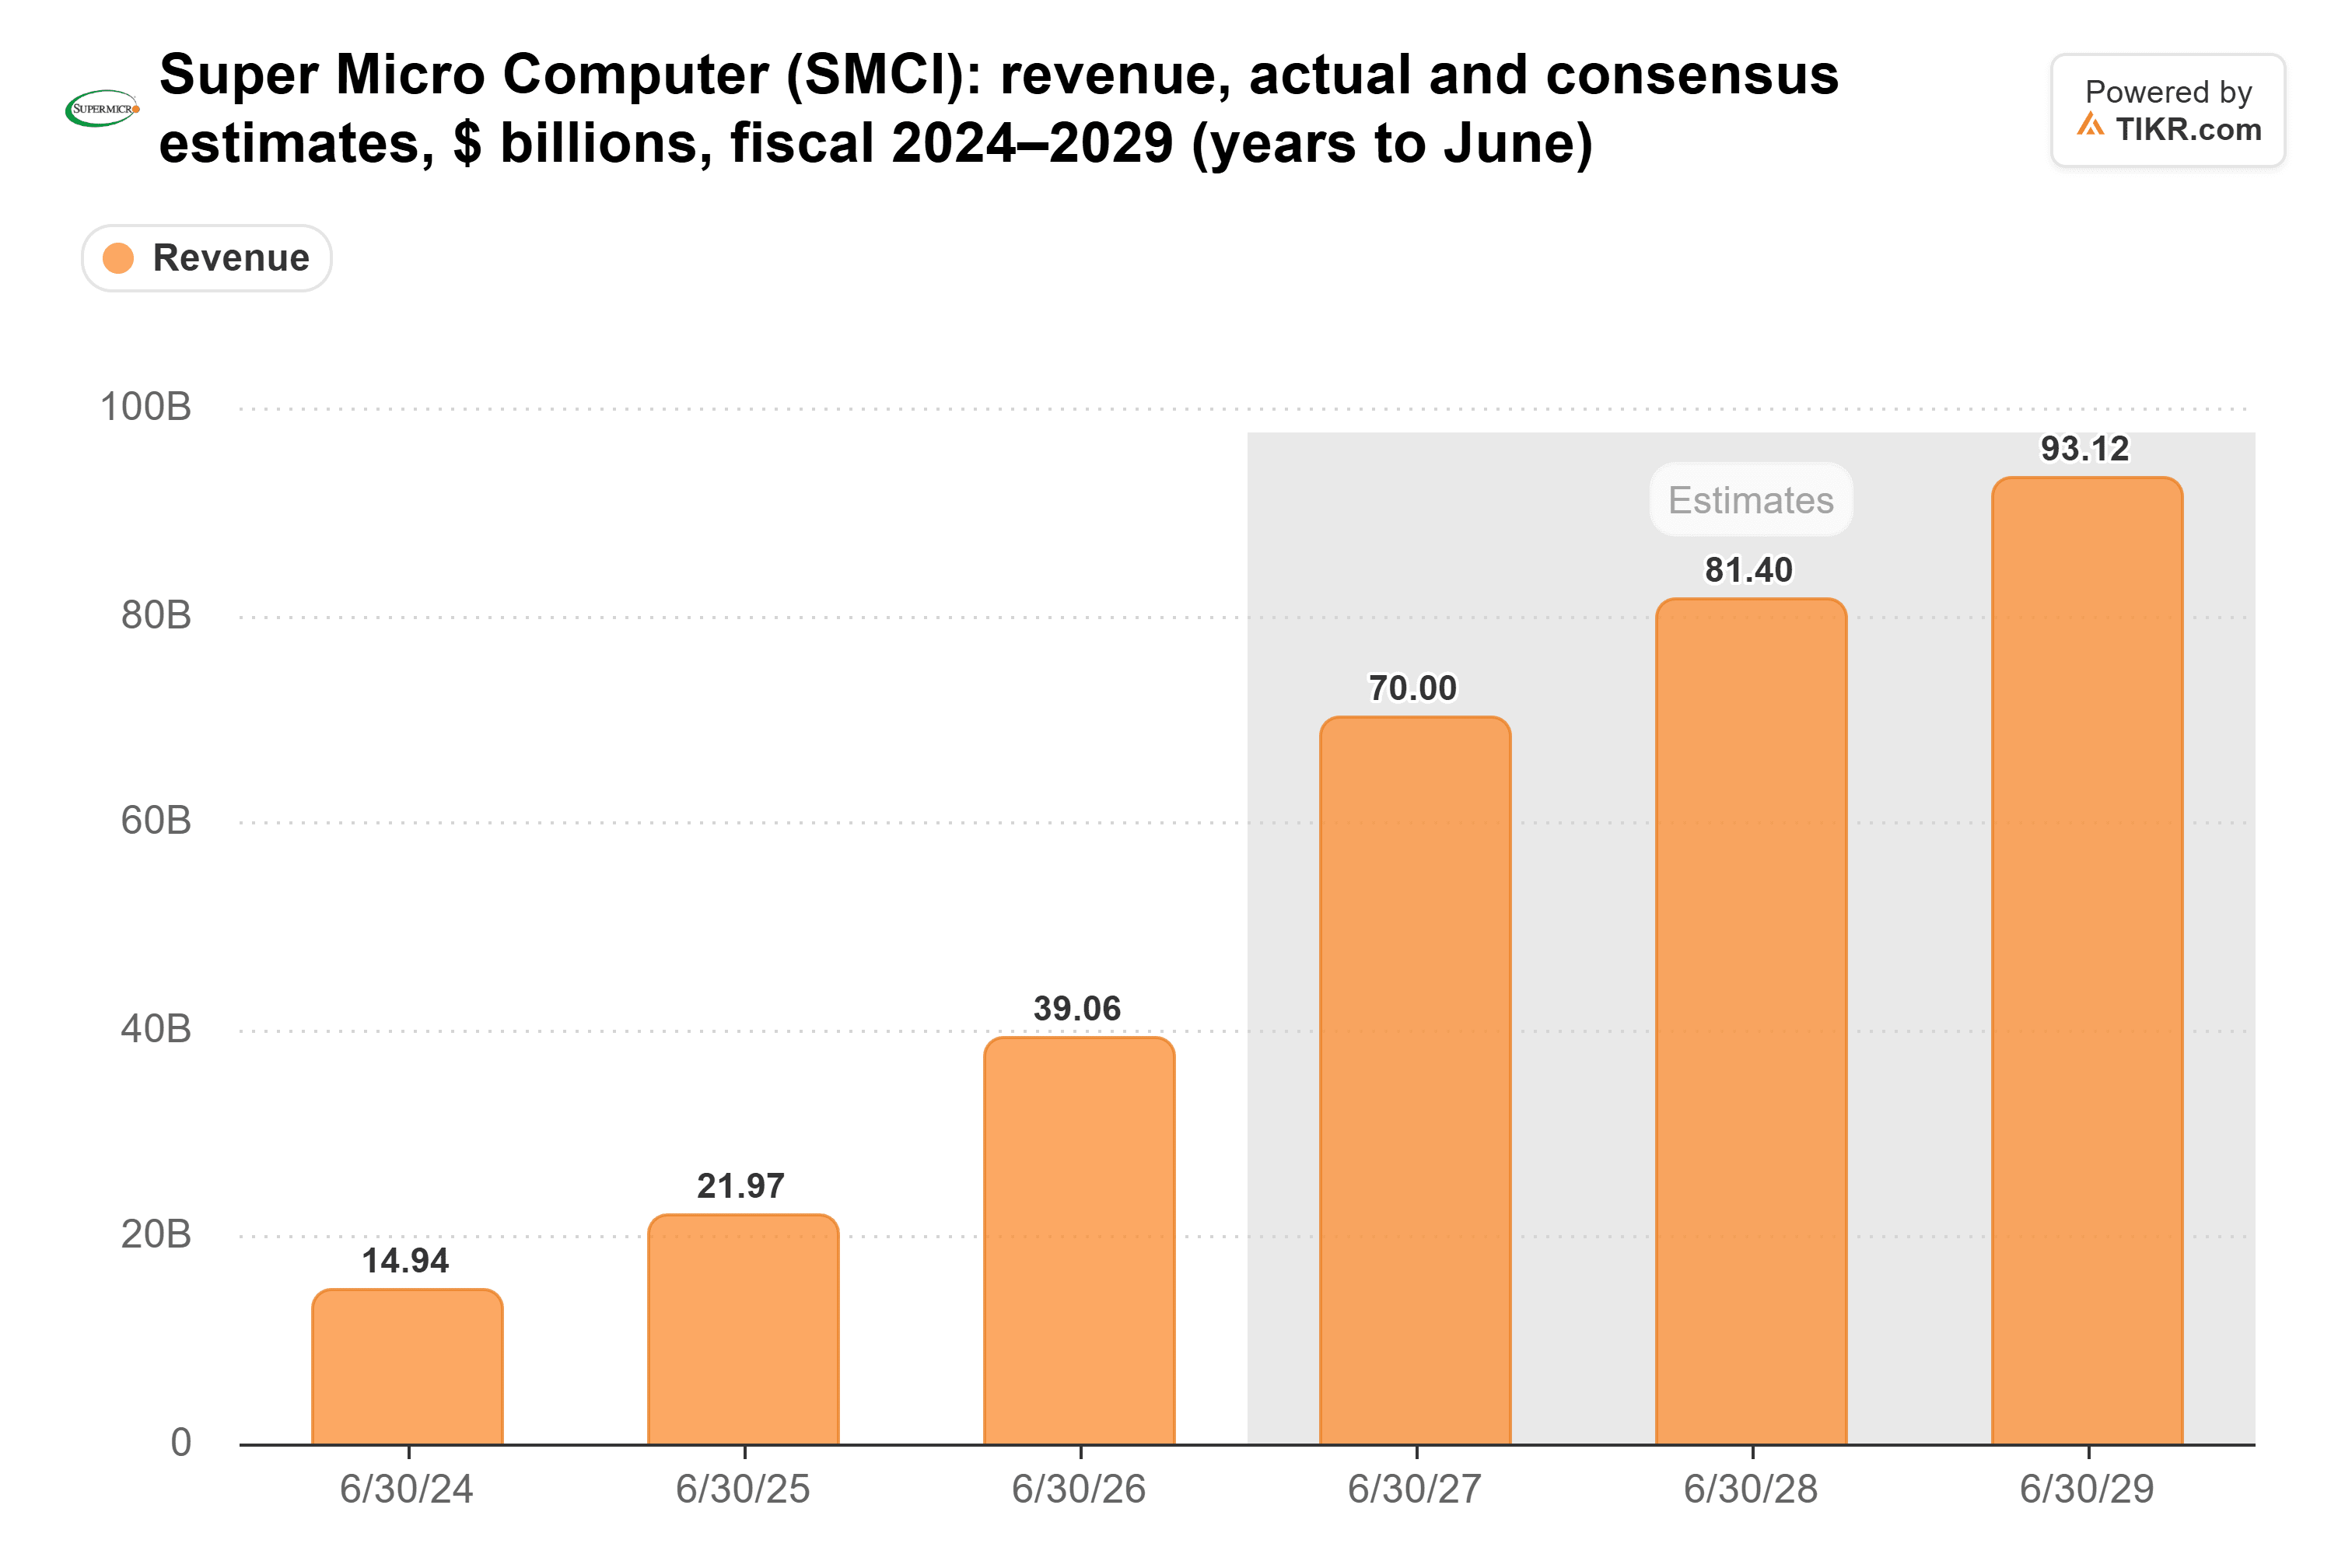
(Some of June’s margin came from one-time items and from deals that slipped into later quarters, so 17.5% isn’t the new baseline.)
Shareholders paid for the growth
Growth this fast eats cash: free cash flow was negative $7.0 billion in fiscal 2026. Dilution isn’t new, either. The share count was rising well before the raise…
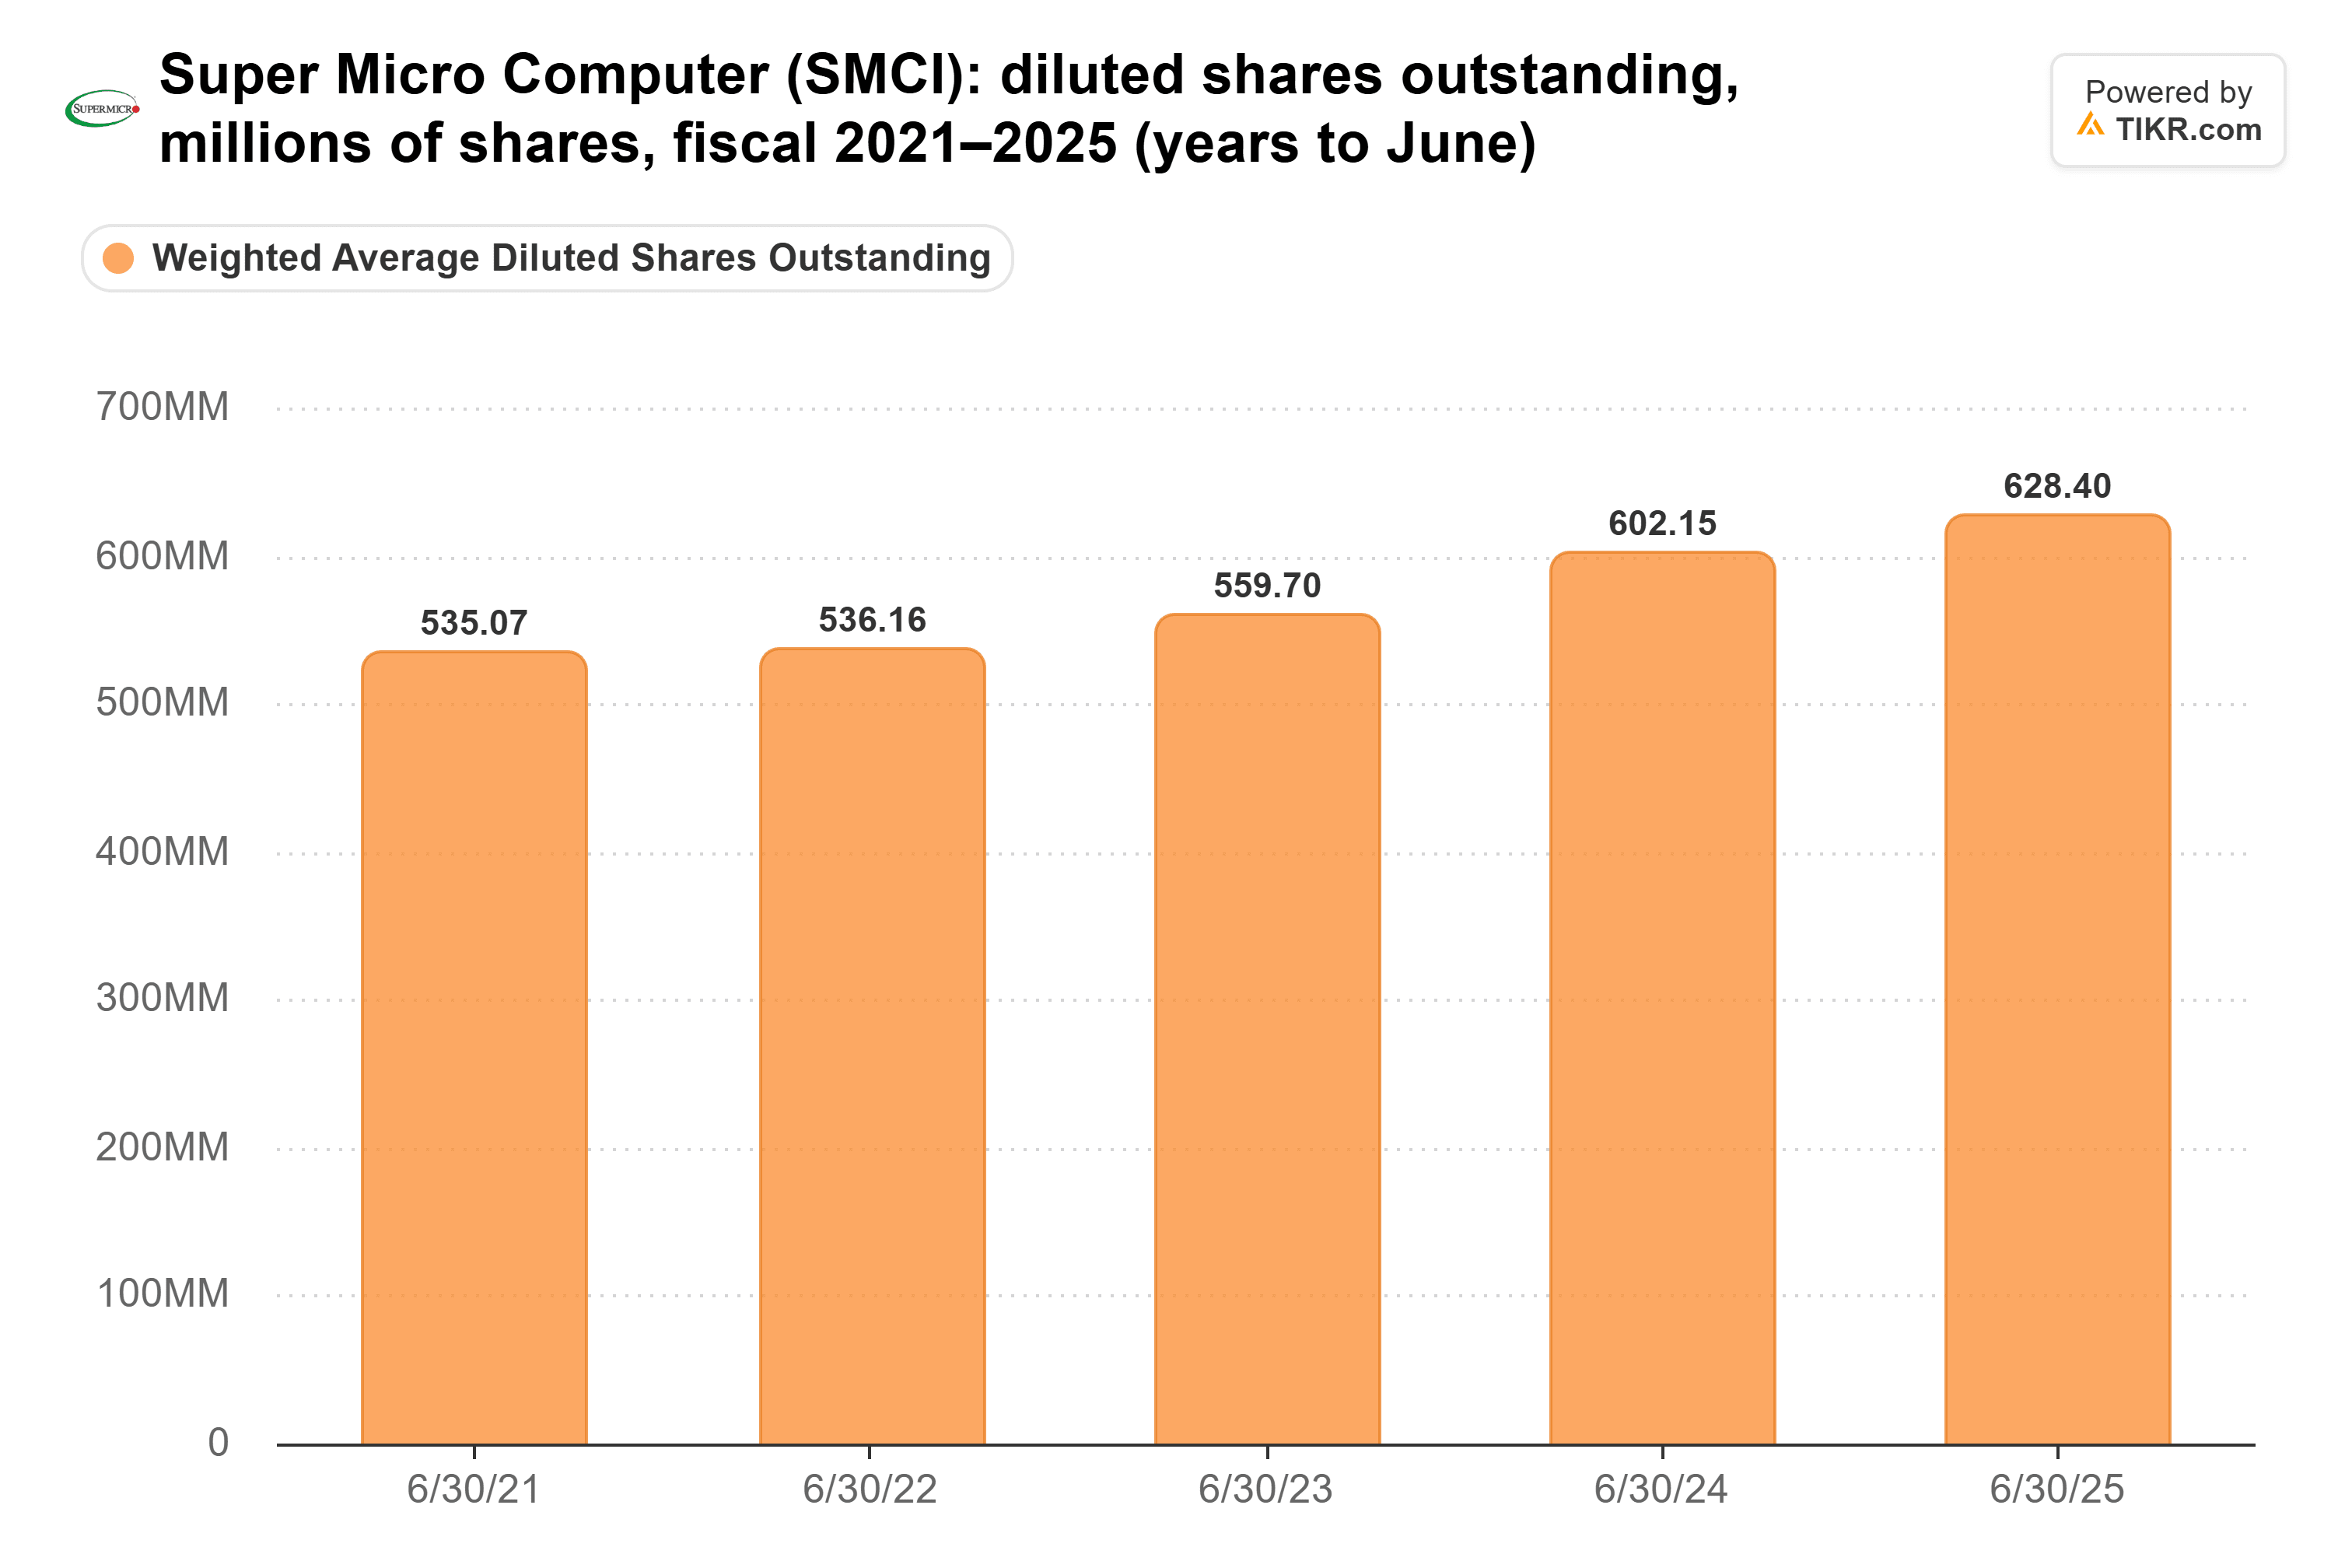
It’s still climbing: 697 million in fiscal 2026, and 745 million guided for the September quarter.
Nor has the legal cloud lifted. In August, a board-led investigation found no evidence that current senior management knew of the alleged scheme. But a former contractor pleaded guilty on Oct. 8, and co-founder Wally Liaw goes to trial in March 2027.
Cheap for a reason, and still too cheap
All of that leaves Super Micro at 7.5x forward earnings. That’s roughly half its five-year average of 14.7x.
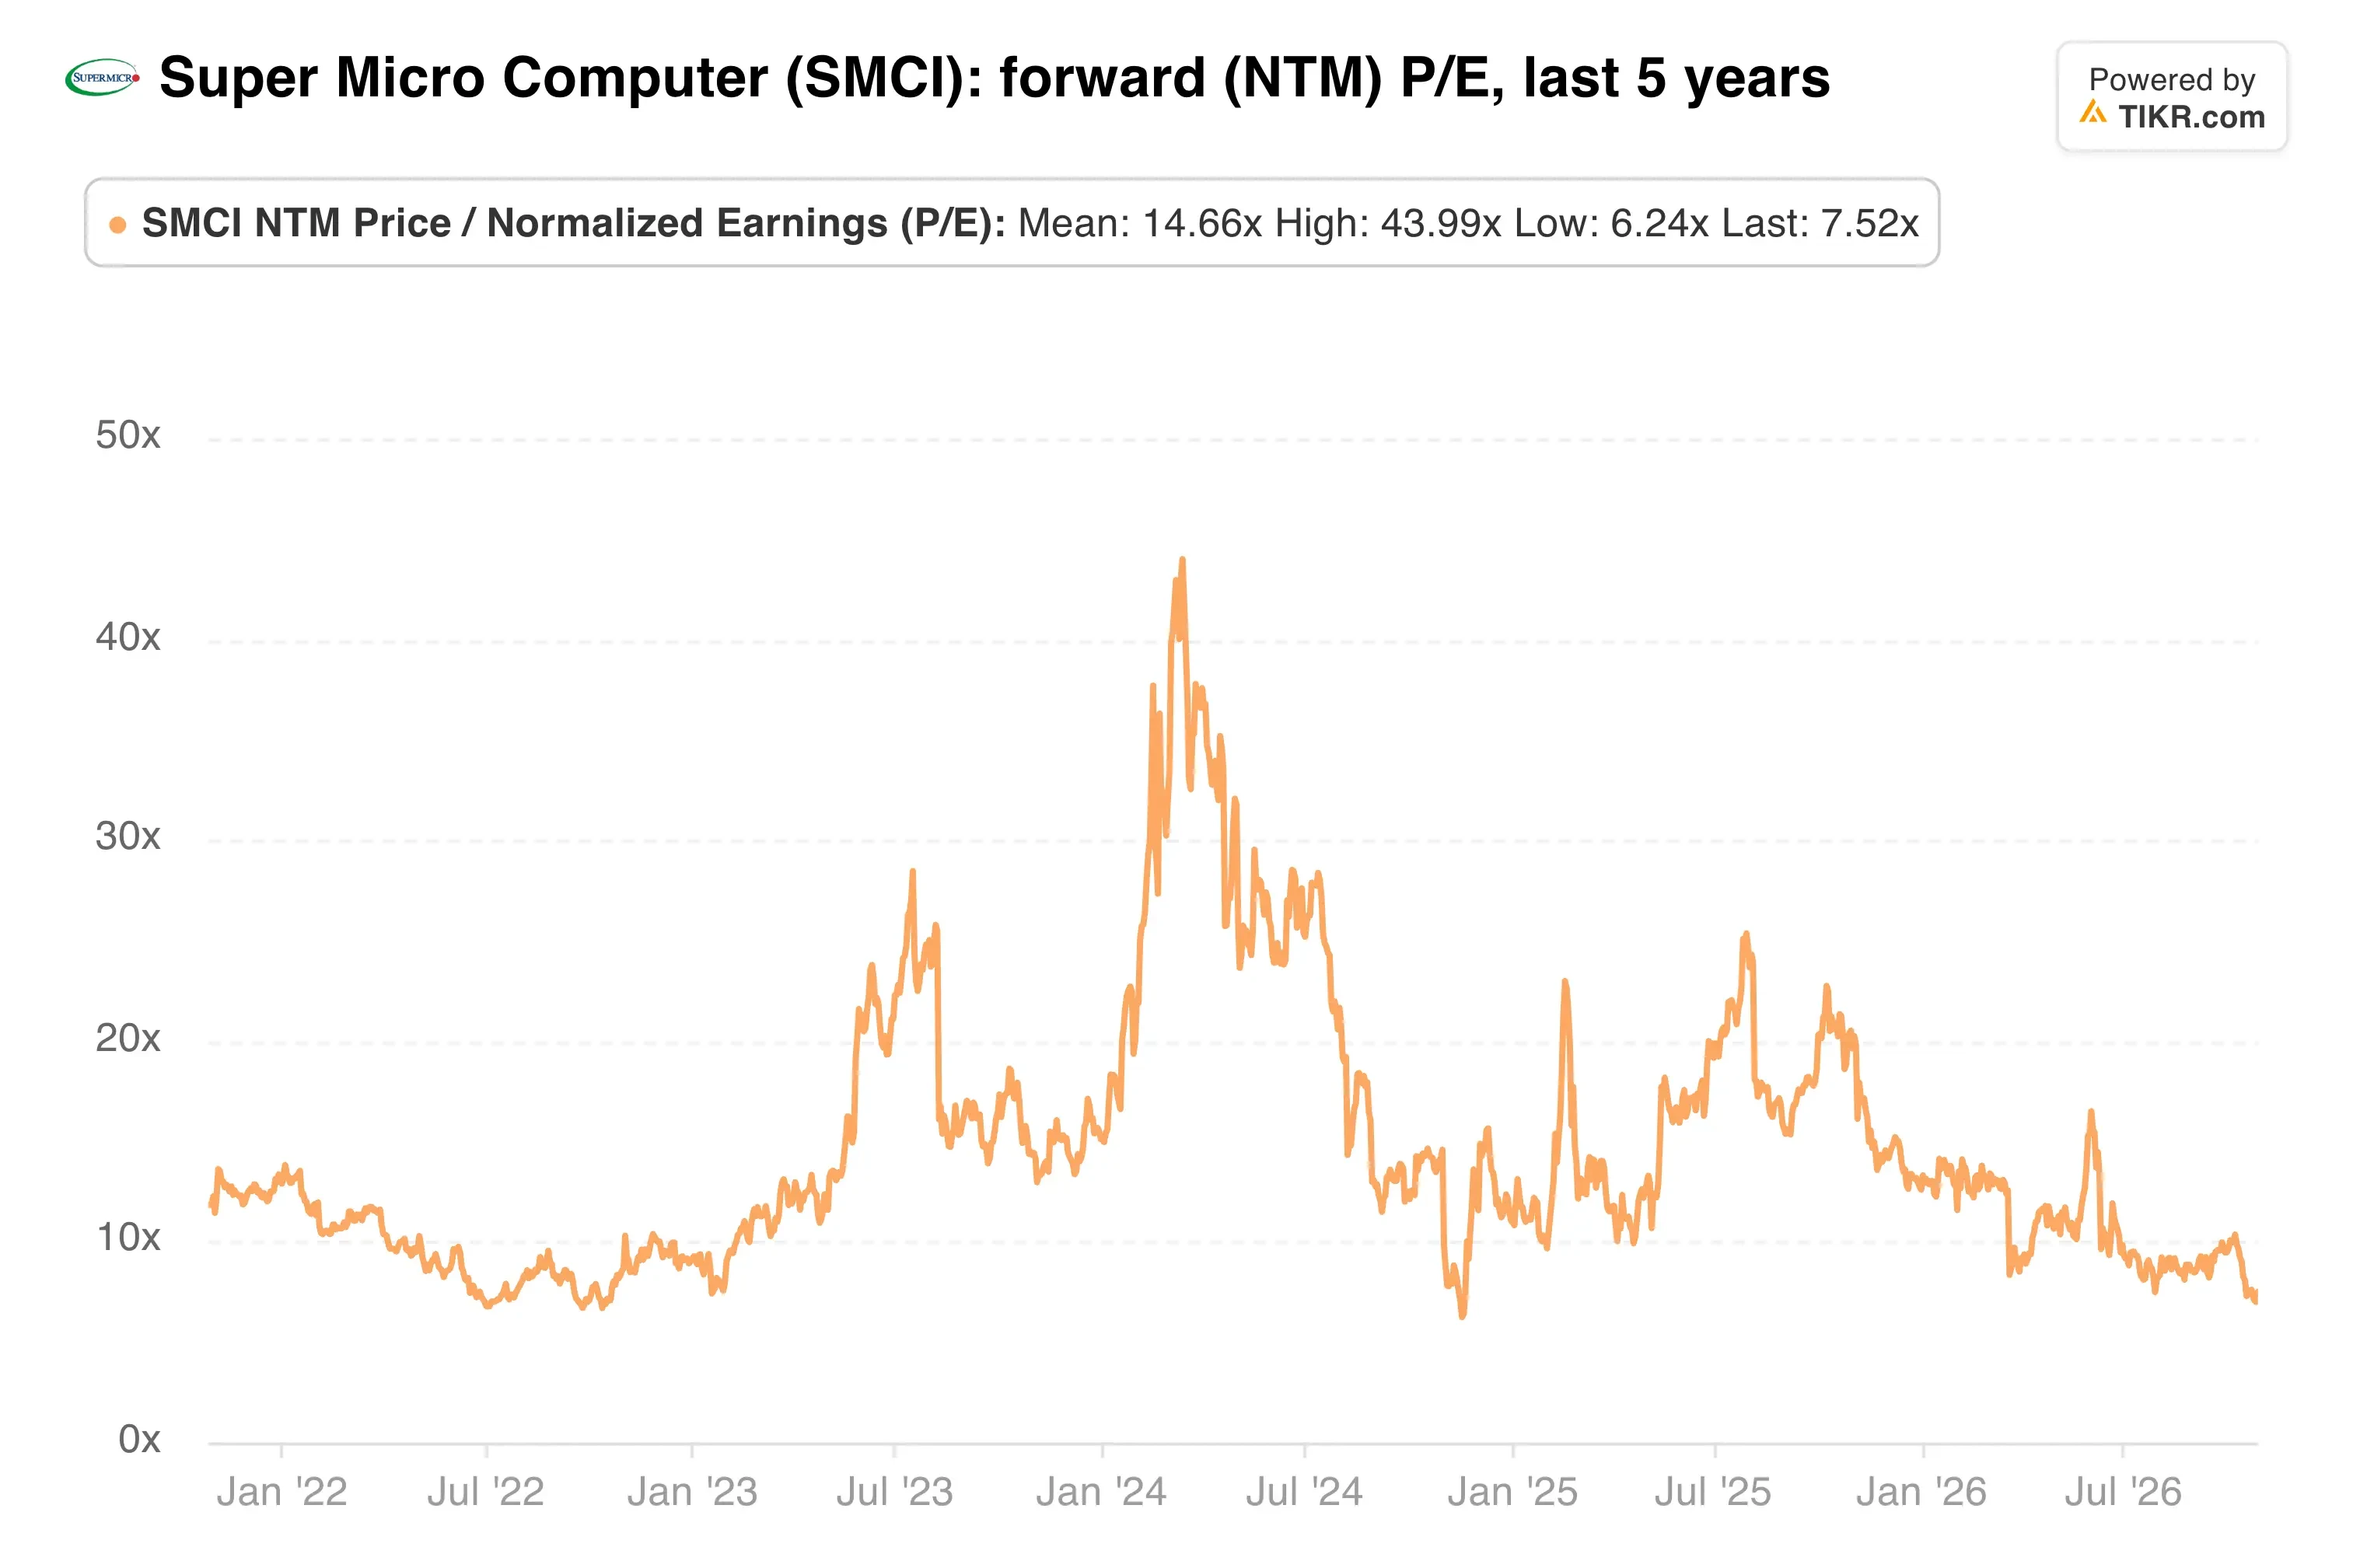
And analysts still expect normalized EPS to rise 29% in fiscal 2027, to $4.67. The $43 consensus target sits about 21% above Tuesday’s close. Even Underperform-rated BofA raised its target to $38 on Oct. 21.
The market is pricing in the next blow-up while sales run far ahead of guidance. At this price, I’d load up.
The next check is Nov. 3, when Super Micro reports final September-quarter results. Watch whether final figures land in the preliminary ranges and whether operating cash flow is positive.
Of course, another legal headline or an AI-spending scare like this month’s could widen the discount fast.
So what is Super Micro stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Super Micro could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!