Key Takeaways
- FIGS stock is up 84% in 2026 after three straight quarters of revenue growth near 30% and two raises to its full-year forecast.
- The August raise to about 20% growth drove the year’s biggest jump, though one-time tariff refunds inflated the record gross margin.
- FIGS’s own forecast implies growth slows to about 13% in the second half, and the stock now trades above Wall Street’s average price target.
- At 59x forward earnings, holding makes more sense than buying more until the Nov. 5 third-quarter report.
FIGS (FIGS) has had quite a year: the scrubs brand’s stock is up 84% in 2026 (through Monday’s close) and sits just below its 52-week high.
And the business backs most of it up. The harder question is how much of what comes next is already in the price.
Three quarters near 30%
It started with the fourth-quarter report in late February:
- Q4 2025: revenue up 33% to a record $201.9 million.
- Q1 2026: revenue up 28% to $159.9 million, with active customers past 3 million for the first time.
- Q2 2026: revenue up 28.8% to $196.6 million, and revenue per active customer hit $229, above its COVID-era high.
International sales jumped 67% in the second quarter. The price increases FIGS put on about a third of its styles also held up better than expected, KeyBanc found in June meetings with management.
The ride wasn’t smooth: the stock sank 24% the day after its May beat, when FIGS guided to growth in the low 20s for the second quarter.
TIKR tracks 9 analysts on FIGS. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on FIGS, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See FIGS’s Analyst Ratings
The August raise did the heavy lifting
With its second-quarter report on Aug. 6, FIGS raised its full-year growth forecast to about 20%, from 14% to 16%. It also lifted its adjusted EBITDA margin forecast to 14.8% to 15.0% and added $100 million to its buyback. Shares jumped 27% the next day, and the raise did most of that work.
CEO and co-founder Trina Spear sees a long runway: “given that we are still only serving a tiny percentage of the world’s healthcare professionals, we believe we are just getting started.”
The record 75.2% gross margin made the quarter look better than it was, though: 780 basis points came from one-time tariff refunds. Without them, it was 67.4%, barely above 67.0% a year earlier.
Supply costs more now, too. Since June 23, a U.S. Customs order has blocked imports from a Jordan manufacturer that made about a third of FIGS’s second-quarter goods. So FIGS is paying to move production elsewhere and to airfreight goods in.
Growth slows from here, by FIGS’s own math
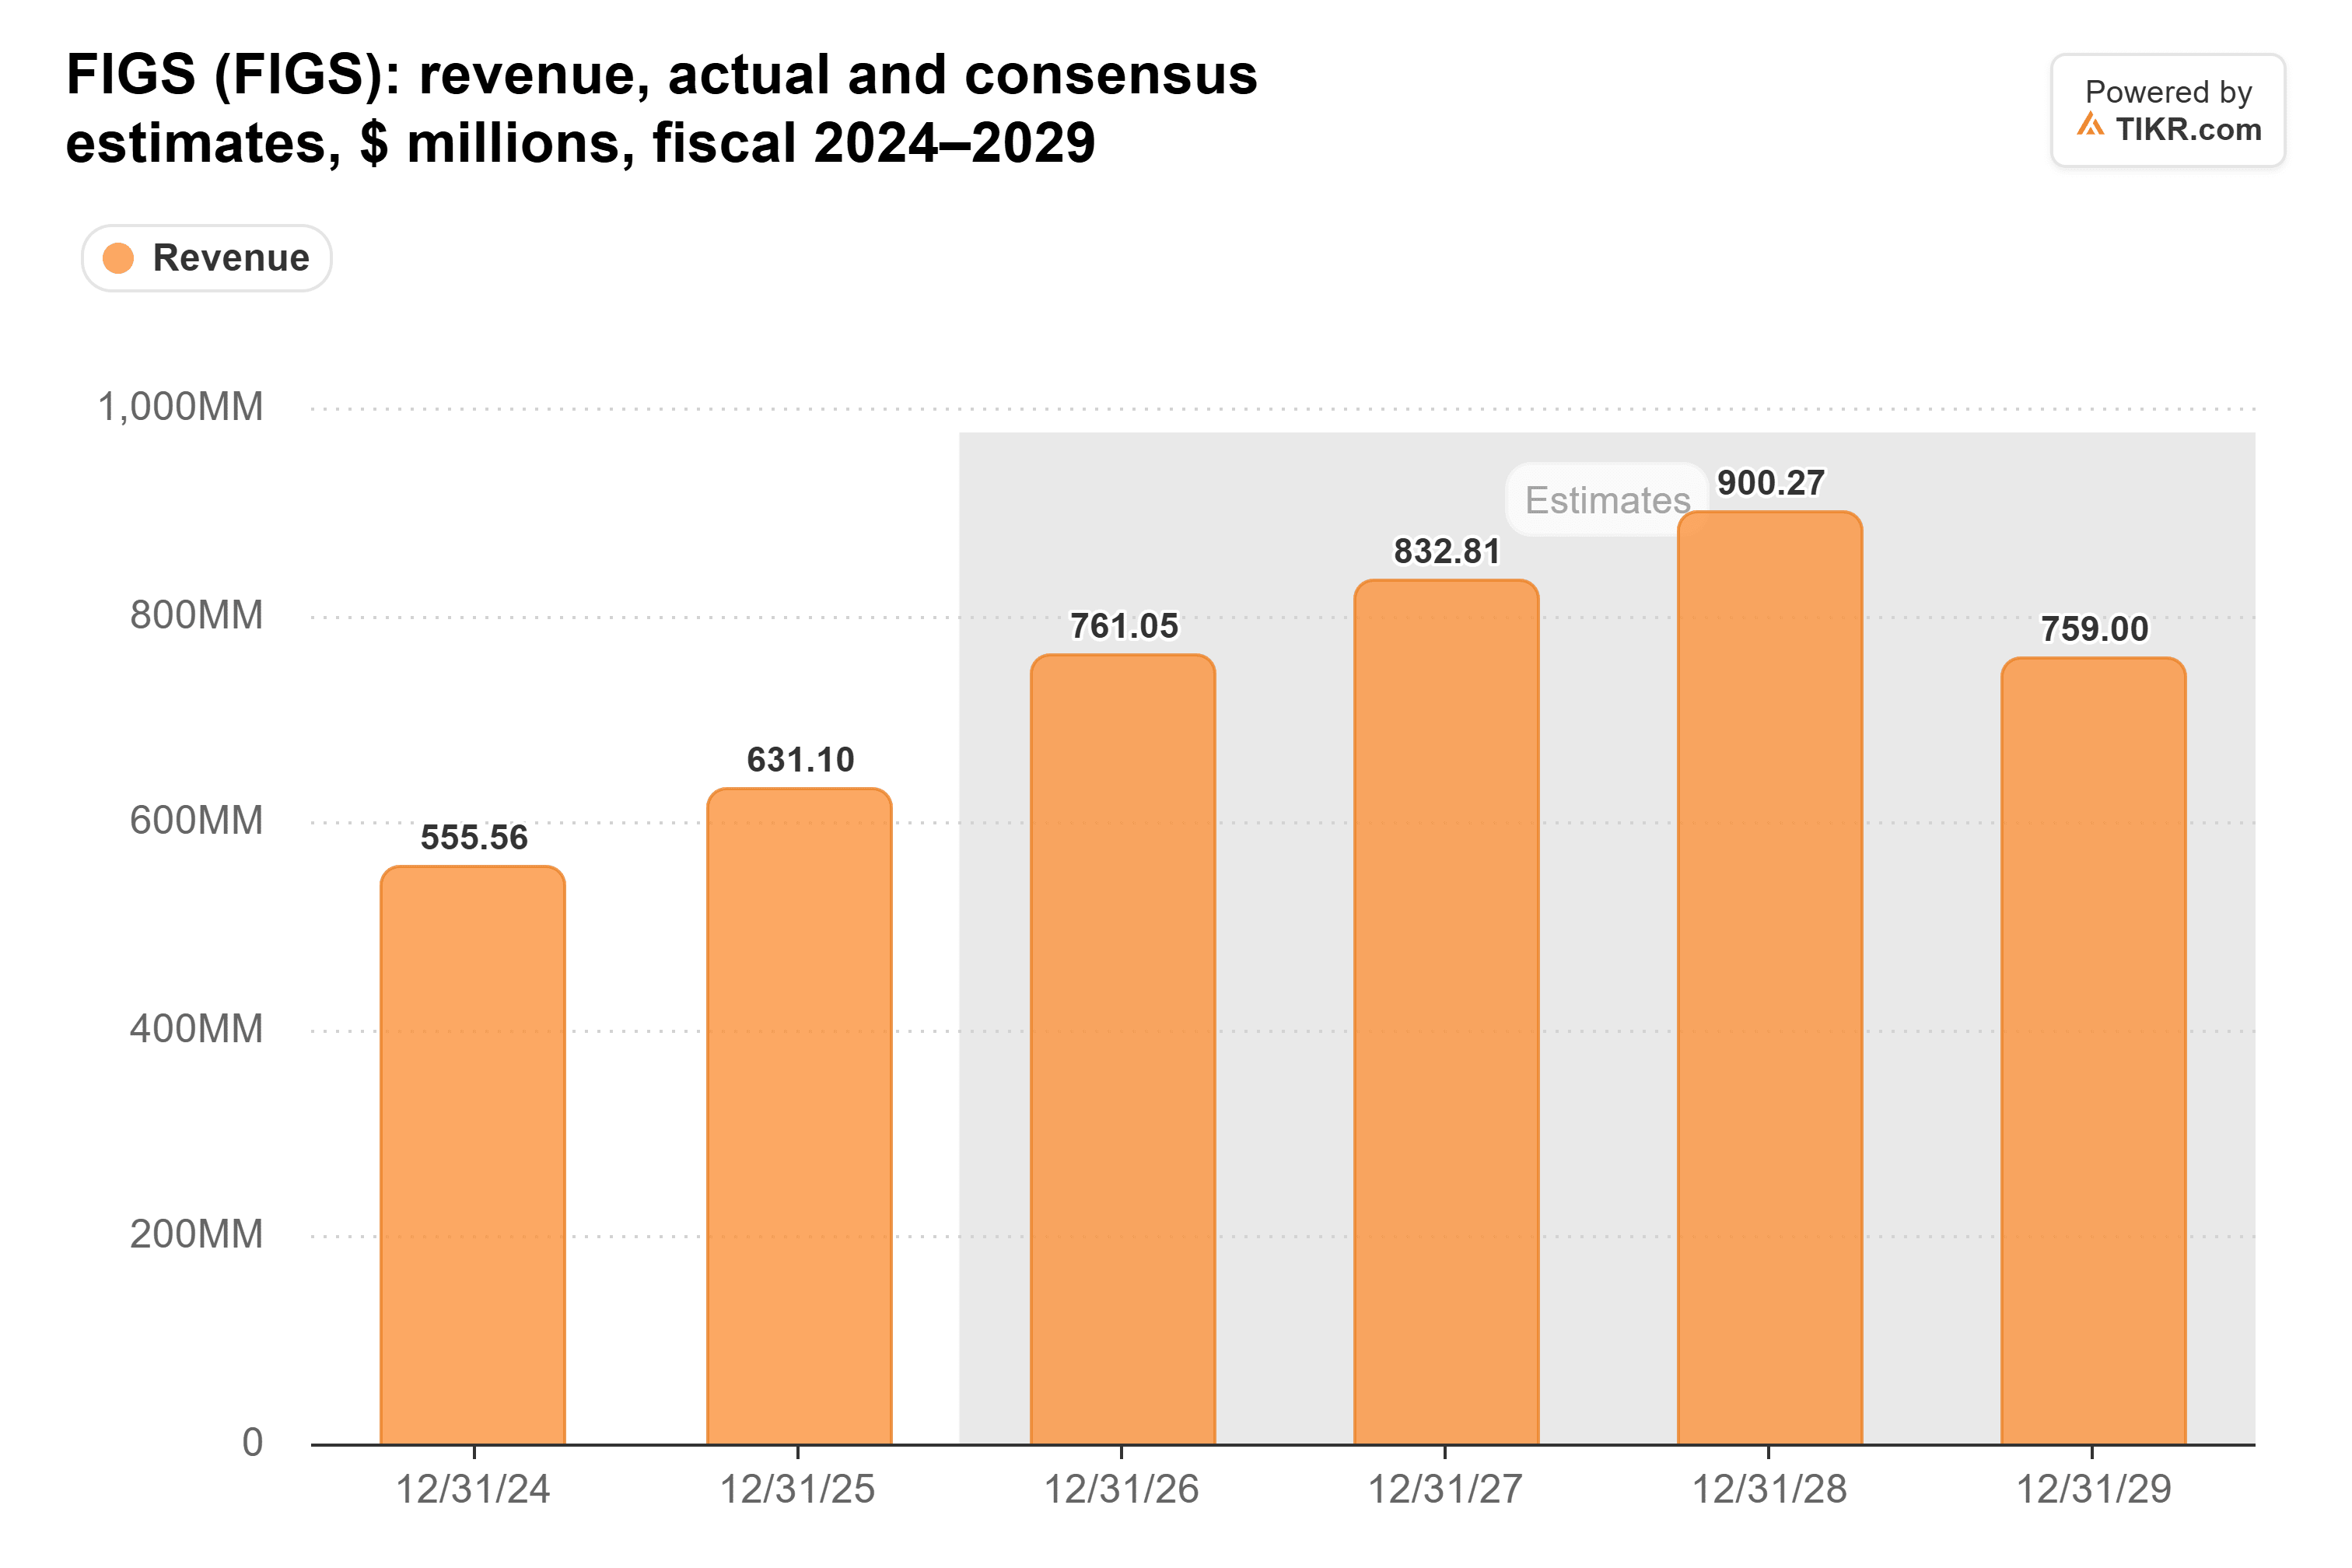
FIGS did $631.1 million of revenue in 2025, so about 20% growth puts 2026 near $757 million. With $356.5 million booked in the first half, that leaves about $401 million for the second half, or roughly 13% growth on last year’s back half.
On the second-quarter call, management guided to about 20% growth in the third quarter and about 10% in the fourth, when FIGS laps its 33% quarter. Analysts expect $761 million of revenue this year and $833 million in 2027, growth of about 9%.
The third-quarter report, after the close on Nov. 5, is the first check on that guide and on what the Jordan block costs.
The price is ahead of the Street
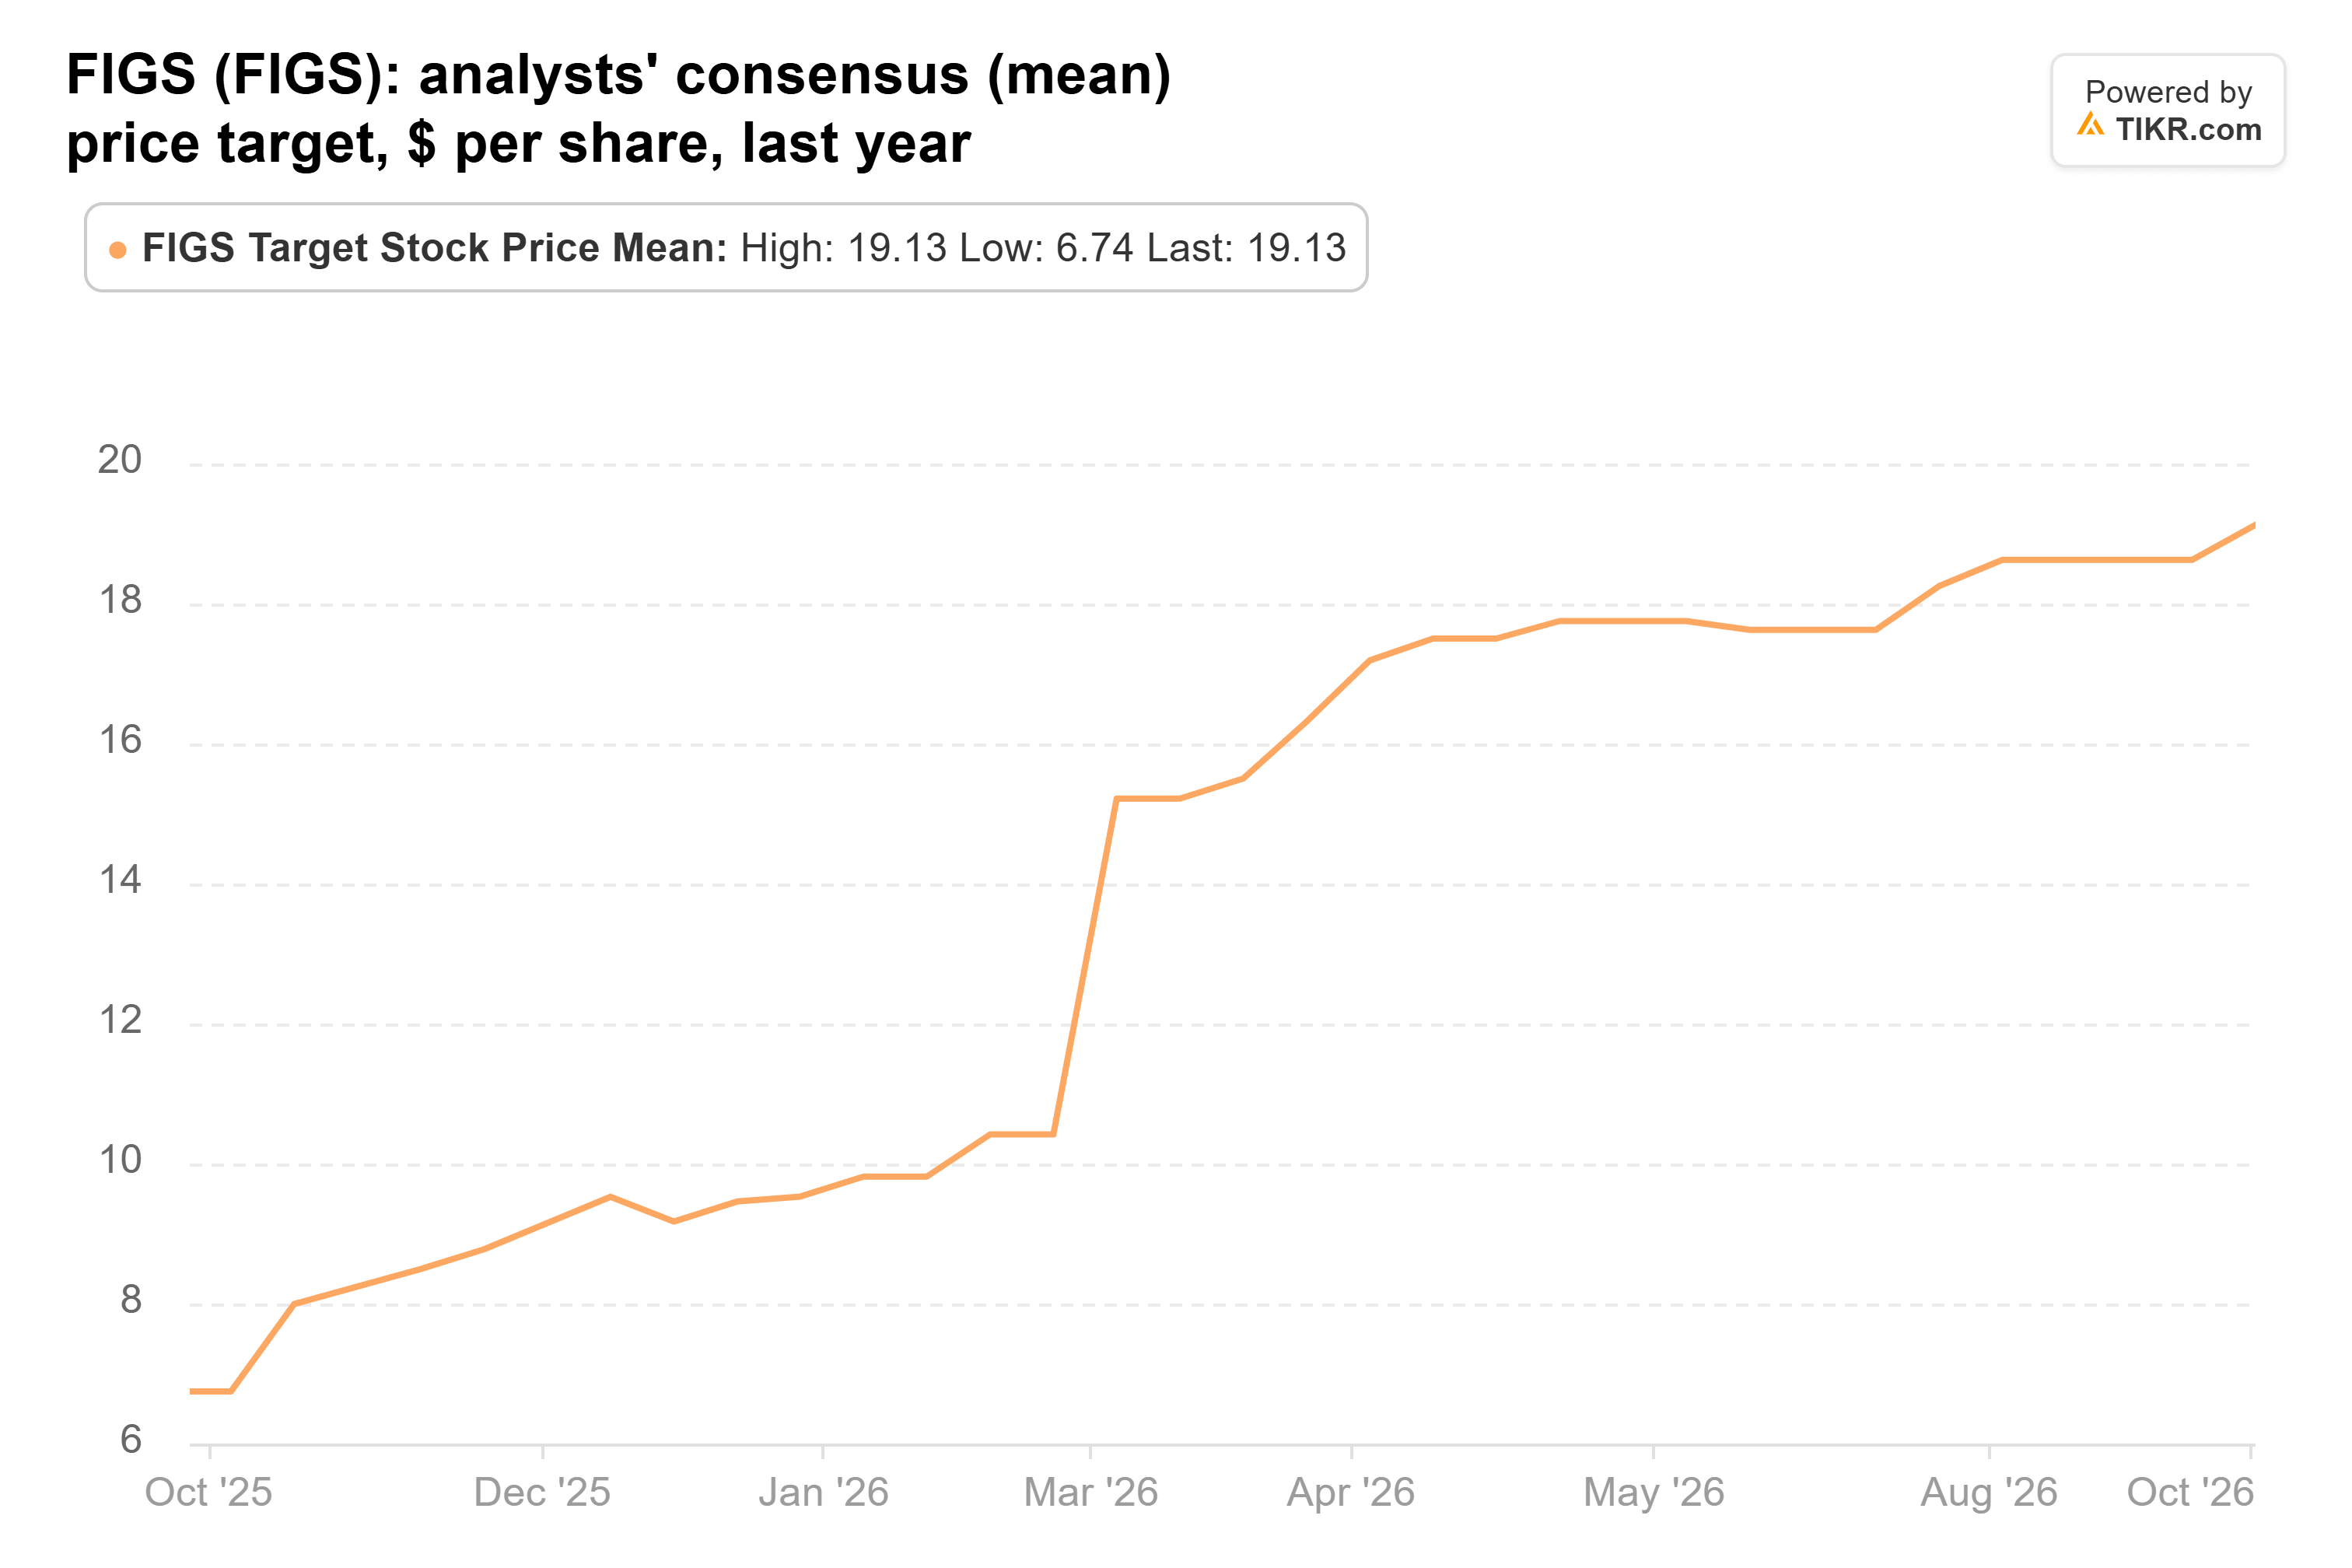
Analysts have chased the stock all year, lifting the average price target from about $7 last November to $19. The stock now trades above that, and the highest target is $22.
The stock is also up 55% in the past month (through Monday’s close), with no company news except the date of that report. That leaves FIGS at 59x forward earnings.

That’s below its five-year average of 79x, but that average comes from years when FIGS barely earned anything. At the end of June, the multiple was closer to 36x. And analysts expect earnings per share to grow just 6% in 2027.
My take: at 59x earnings, FIGS looks fully priced for now. I wouldn’t buy more before Nov. 5. I’d hold and let the third quarter show the back half beating that 13% bar.
Of course, FIGS has already raised its forecast twice this year. Another raise on Nov. 5 would reset the targets, and the case for buying more.
So what is FIGS stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what FIGS could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!