Key Takeaways
- UPS stock rose 6% today after third-quarter revenue grew 6.7% to $22.9 billion and the company raised its 2026 outlook.
- Cutting low-paying Amazon deliveries is lifting profit: U.S. revenue per piece rose 6.1% even as daily volume fell 3%.
- Free cash flow guidance rose to about $6.1 billion, which now covers the roughly $5.4 billion UPS plans to pay in dividends this year.
- Even after the jump, UPS’s forward P/E sits well below its five-year average.
United Parcel Service (UPS) jumped 6% today after it beat third-quarter estimates and raised its 2026 outlook. It did both while handling fewer packages.
How? “We’re dispelling the old belief that all packages were created equal and that volume solves all problems,” chief executive Carol Tomé told Reuters.
TIKR tracks 29 analysts on United Parcel Service. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on United Parcel Service, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See United Parcel Service’s Analyst Ratings
Fewer boxes, more profit
Third-quarter revenue rose 6.7% to $22.9 billion, ahead of the $22.28 billion analysts expected. Adjusted EPS of $1.69 beat the $1.62 consensus. (It was $1.74 a year ago, but that included $0.30 from a one-time sale-leaseback gain.)
The real story is the U.S. business. UPS finished cutting back its Amazon (AMZN) deliveries in the second quarter, and average daily domestic volume fell 3% from a year ago. Even so, domestic revenue grew 4.5% on a 6.1% jump in revenue per piece, which outran a 5.5% rise in cost per piece. Adjusted domestic operating profit climbed 14% to $1.03 billion.
International revenue per piece rose even faster, up 15%.
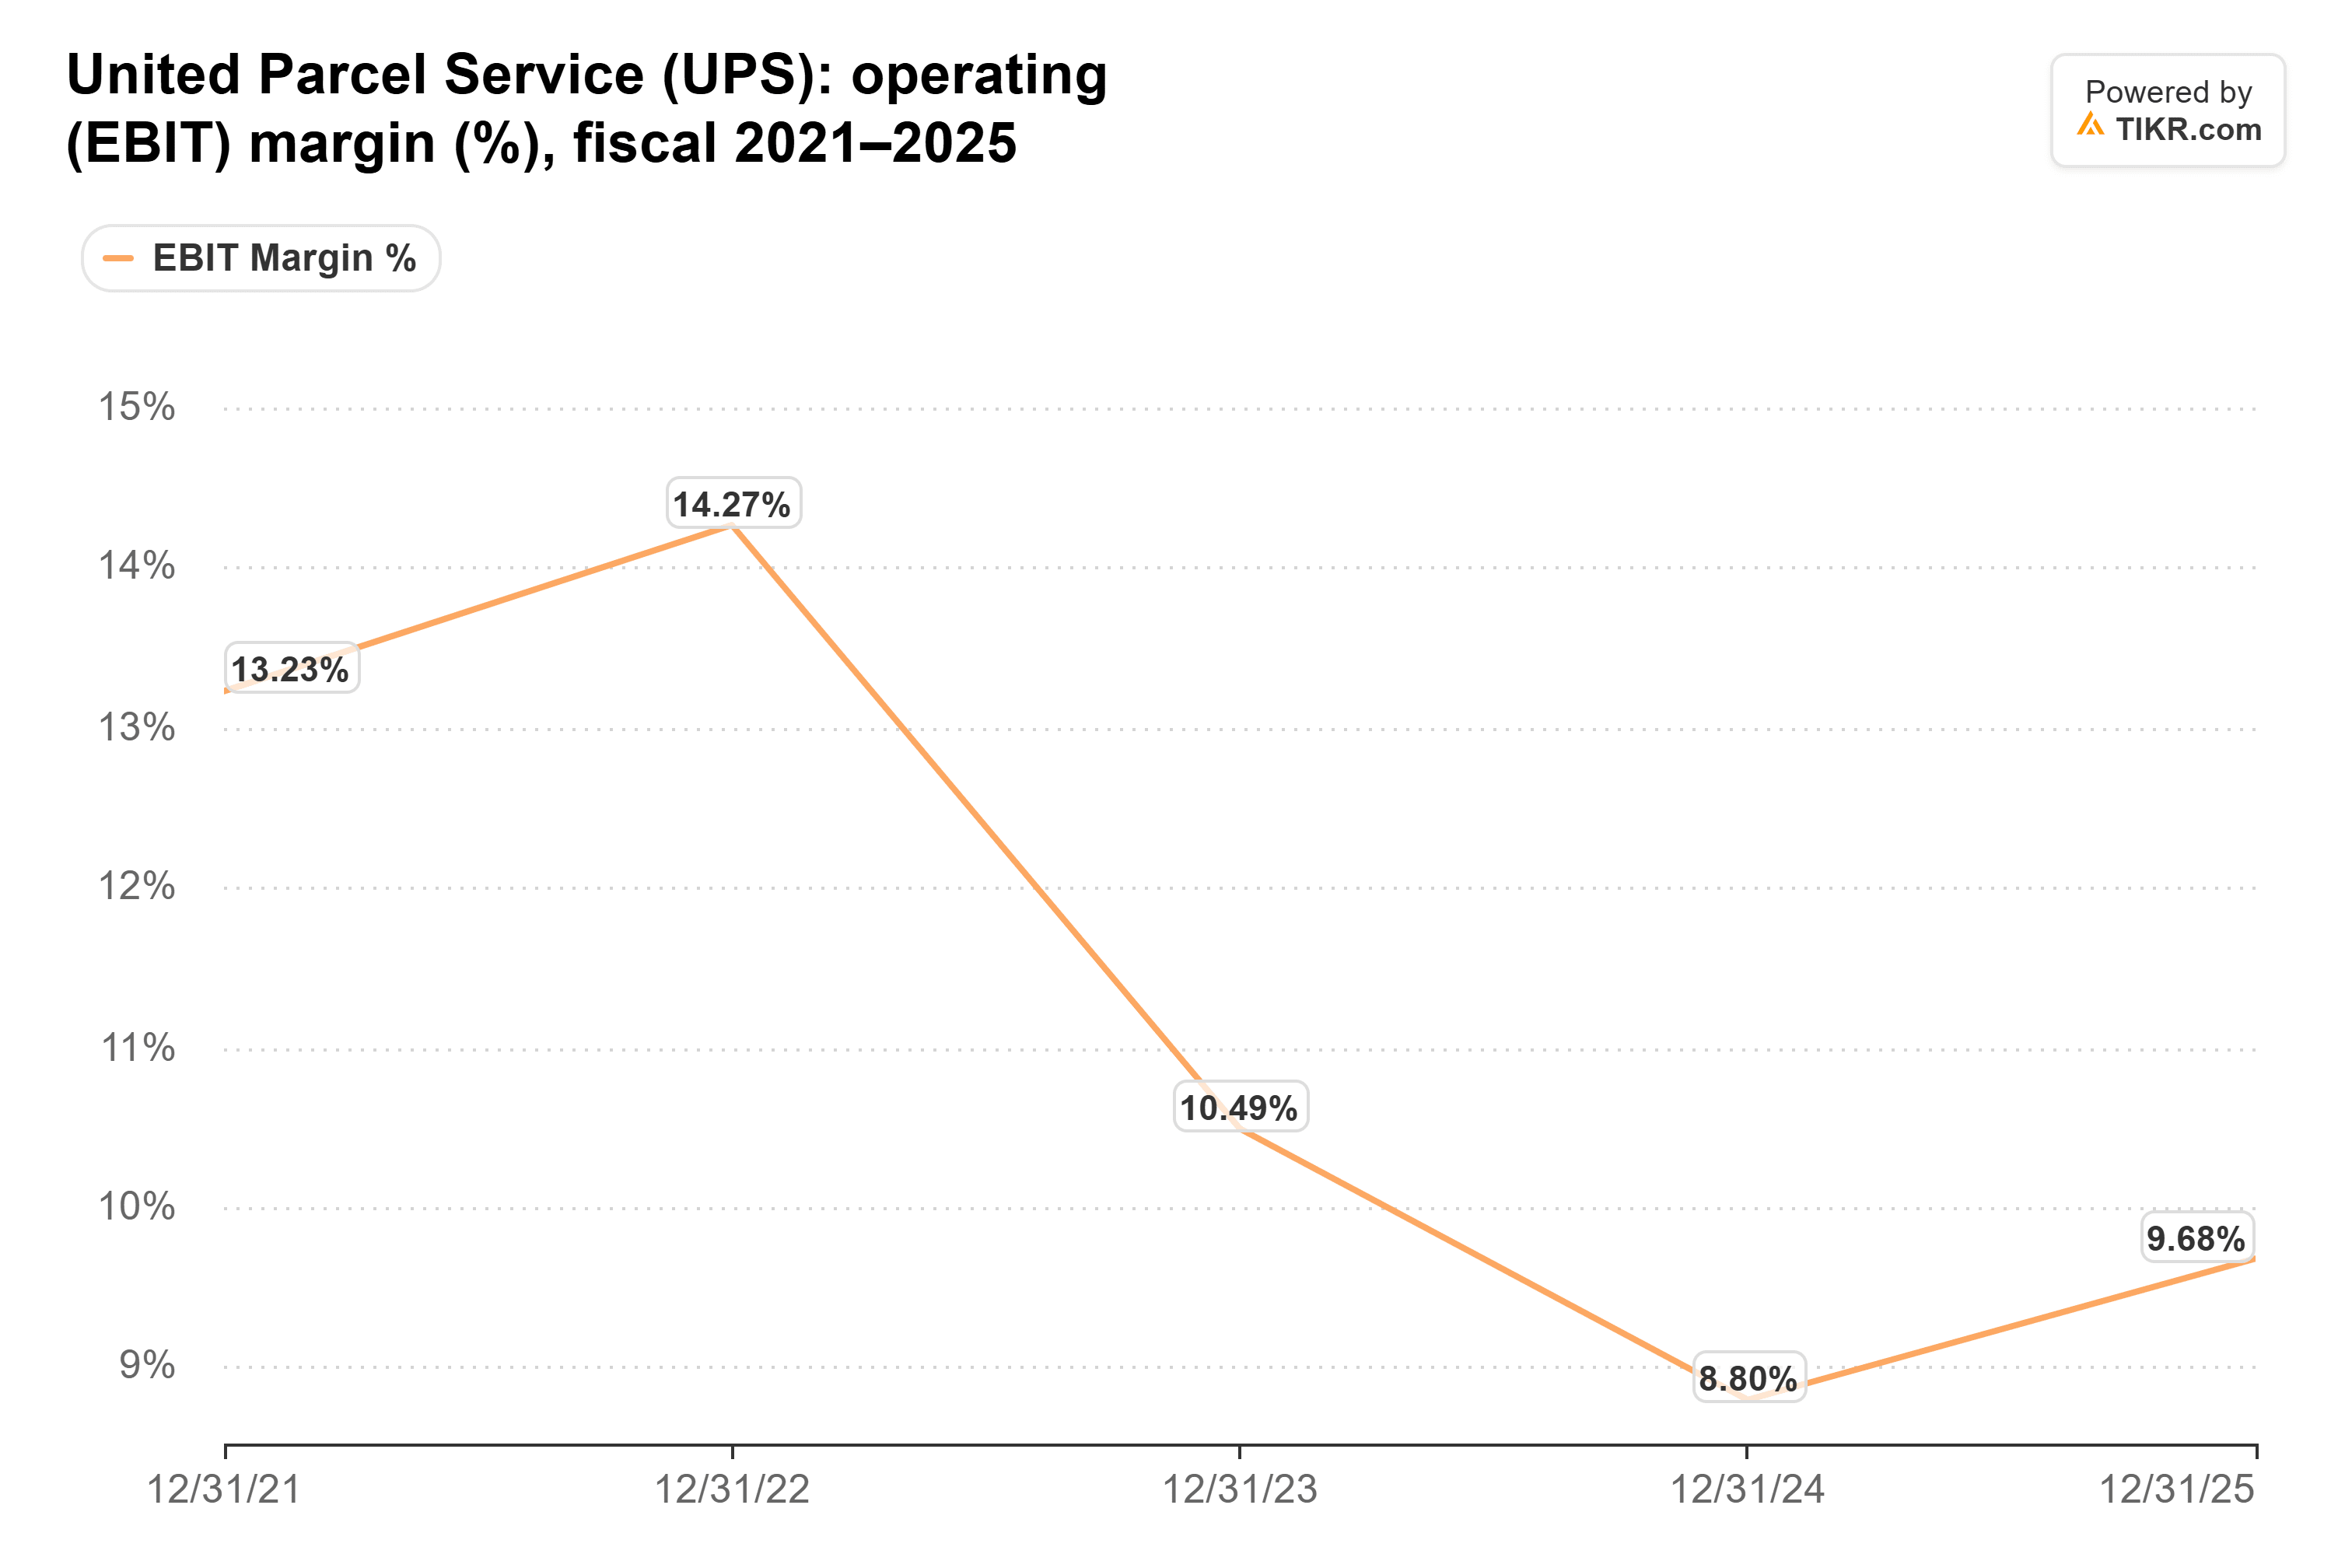
UPS needs that, since its operating margin fell from 14.3% in 2022 to 9.7% last year.
A raised outlook, again
UPS now expects about $92.6 billion of revenue this year, up from $91.2 billion. It also expects about $8.75 billion of adjusted operating profit and adjusted EPS of about $7.28, up from $7.22. And it plans to get there with fewer holiday packages: total daily volume should fall 1.3% in the fourth quarter, reportedly.
Analysts already had earnings growing from here, to $8.06 a share in 2027 and $8.70 in 2028.
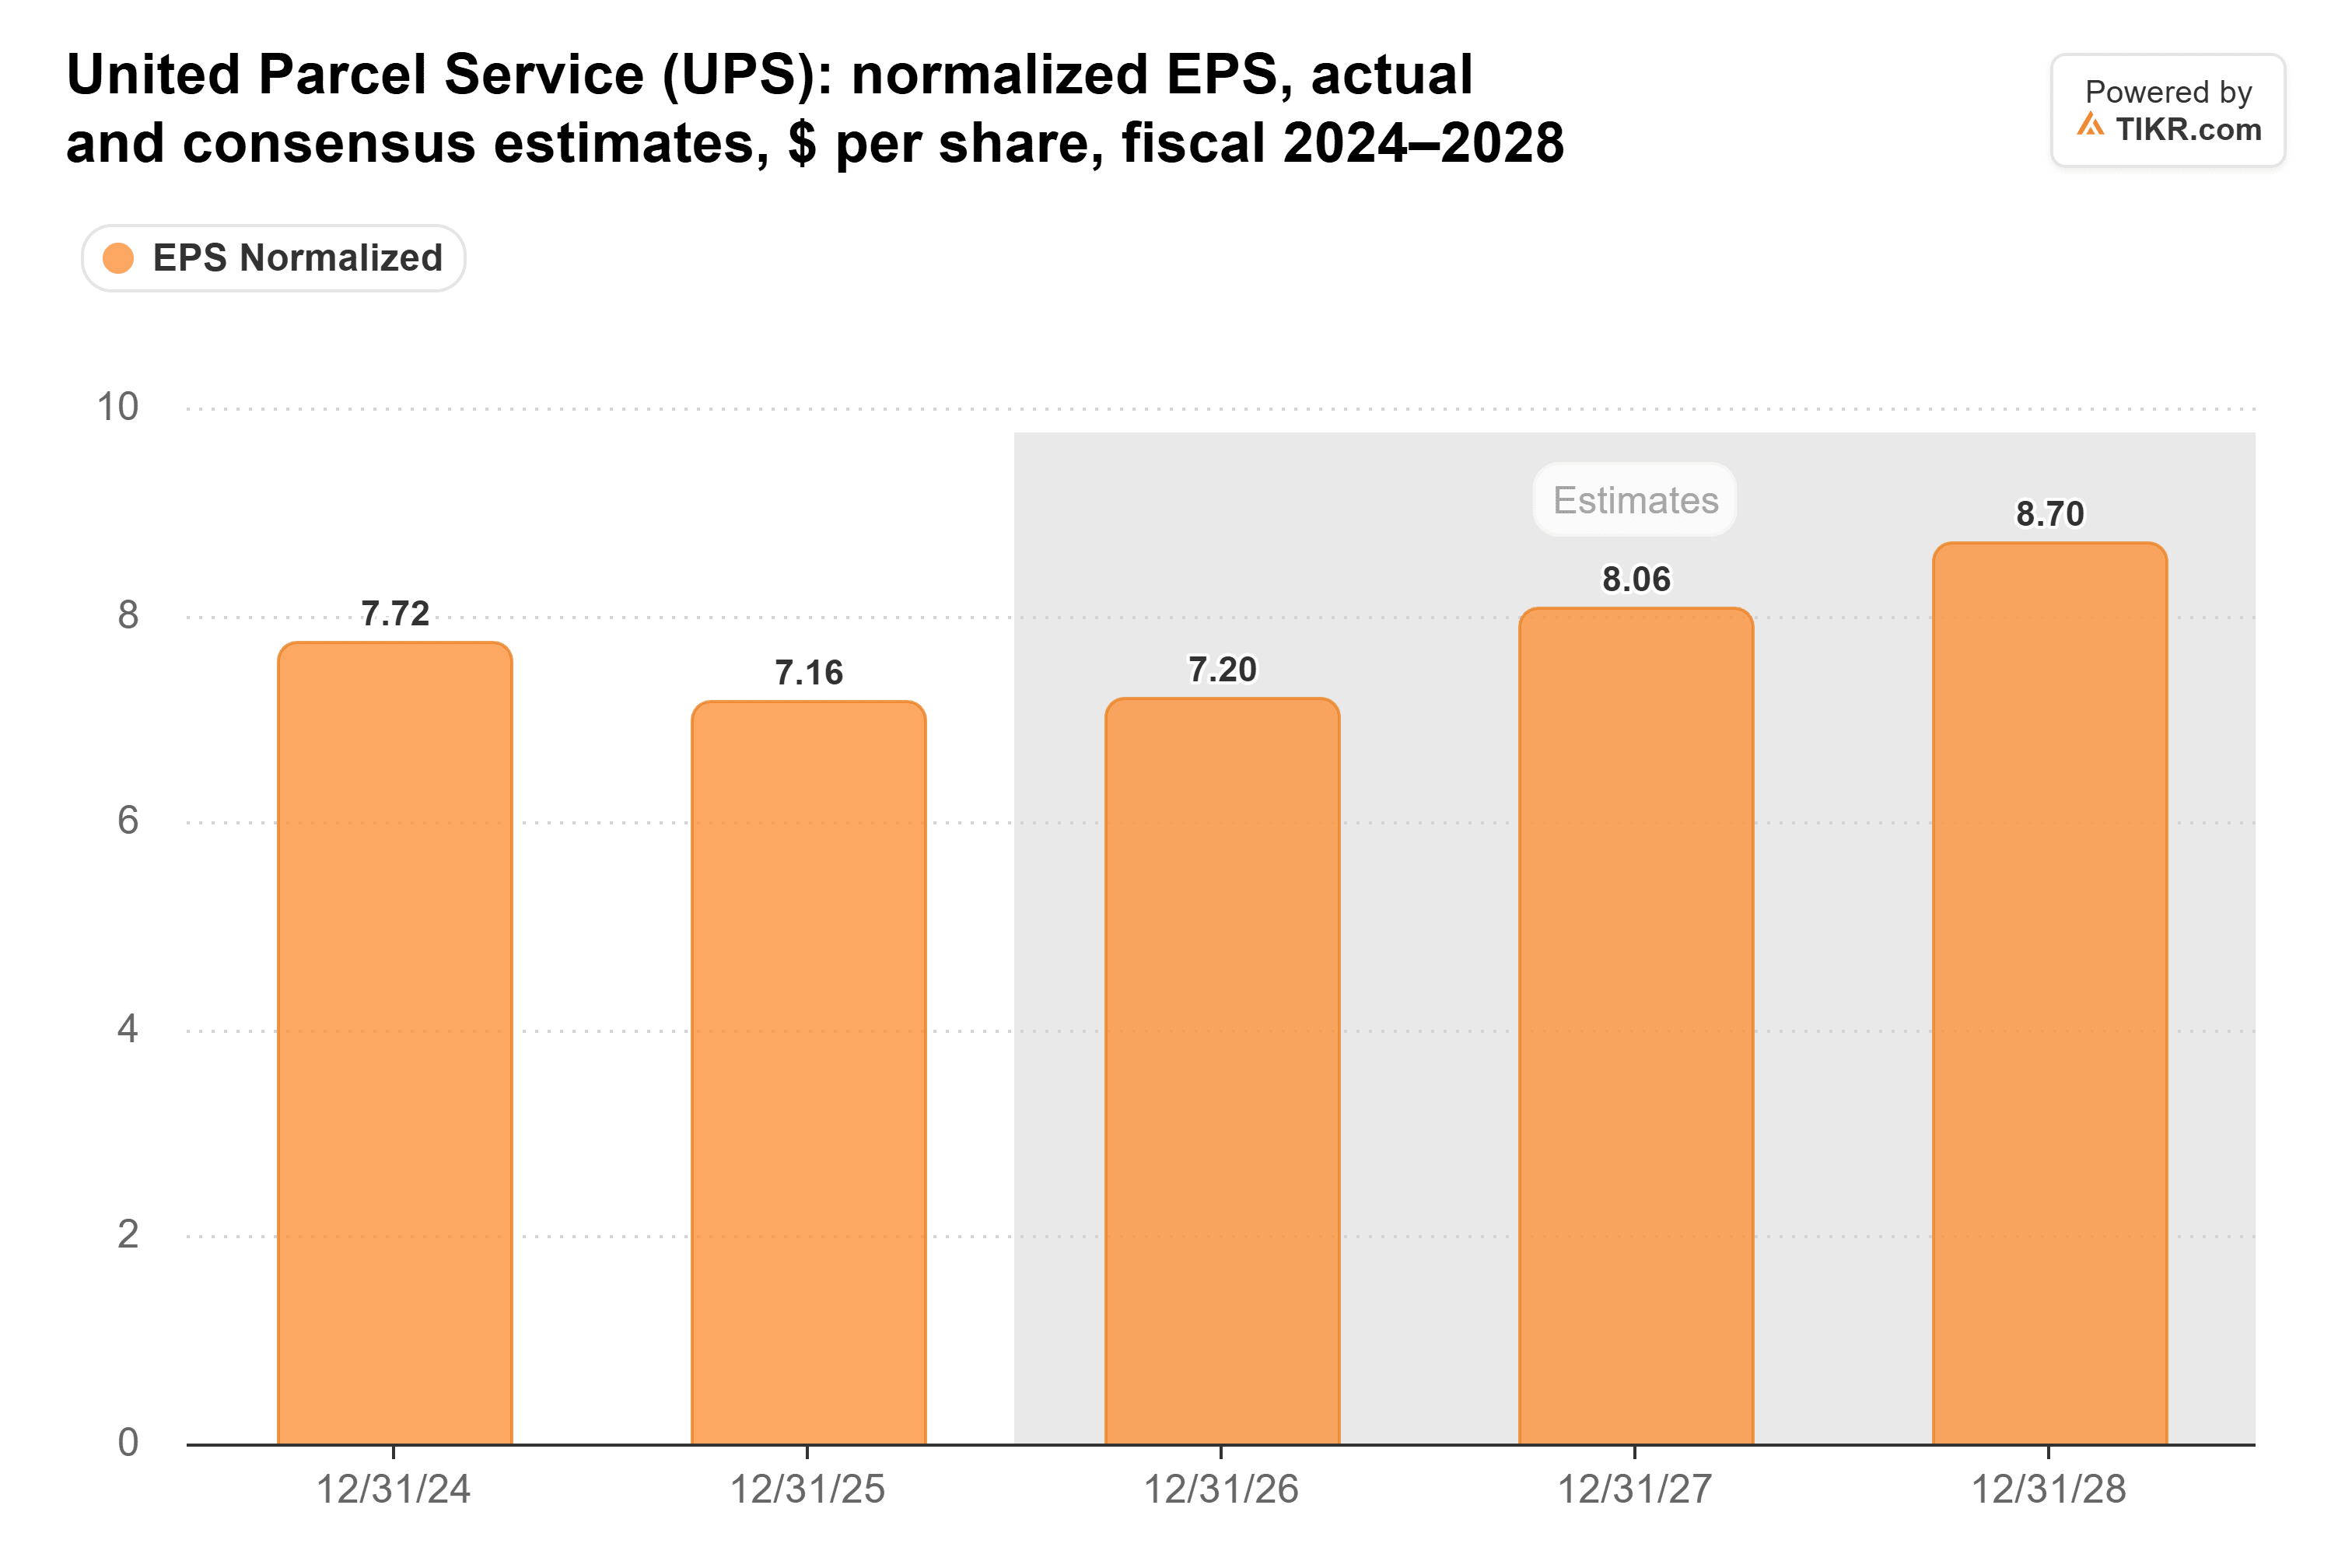
The new guidance is above their $7.20 for this year, so those estimates look more likely to rise than fall.
Free cash flow guidance went up too, to about $6.1 billion from $5.5 billion. That’s welcome news for a dividend that recently ate up 99% of free cash flow. UPS plans to pay around $5.4 billion this year, so the new target covers it, though without much room to spare.
Still cheap
Before today’s jump, UPS traded at 12.9x forward earnings, well below its 15.2x average over the past five years.
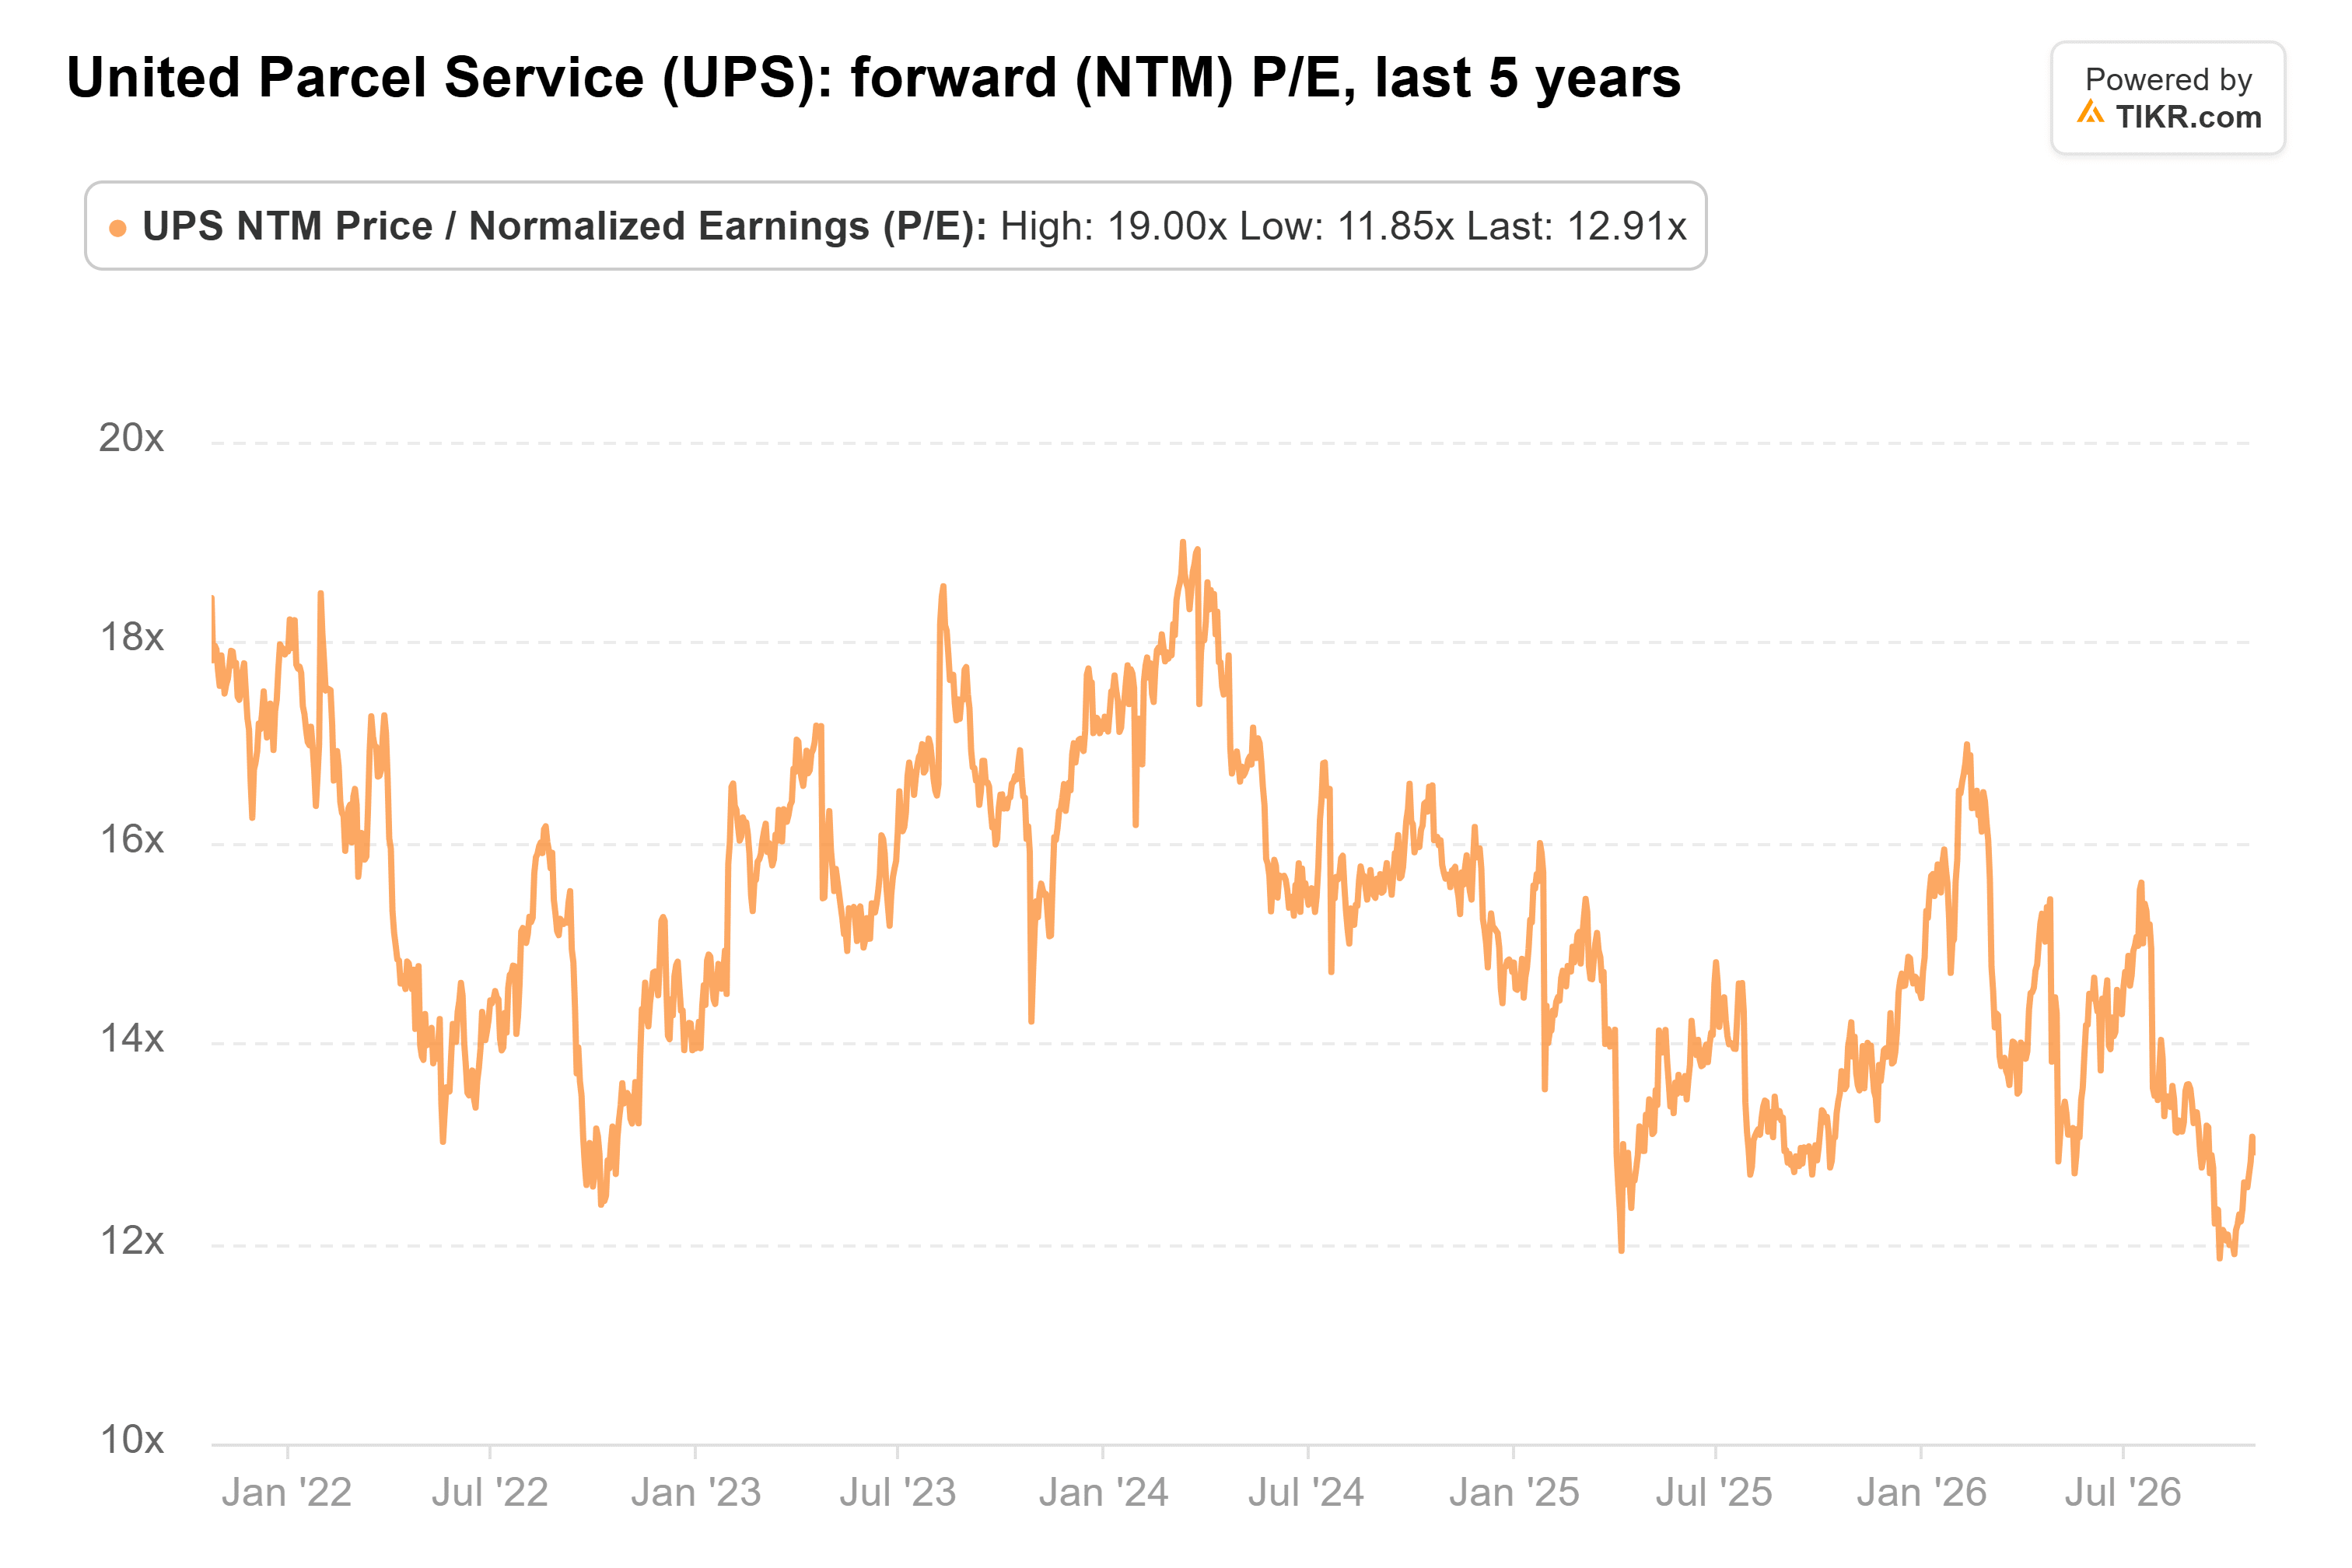
Even after the move, it’s closer to 14x.
My take: Tomé’s plan of fewer but better-paying packages is working, and at this multiple the market still isn’t paying much for it. Of course, the holiday quarter is the next test, with volume falling, and UPS’s Efficiency Reimagined cost program doesn’t wrap up until late 2027. Fourth-quarter results are due early next year.
So what is UPS stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what UPS could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!