Key Takeaways
- Instacart shares fell 6% today after Bloomberg reported that Uber had walked away from talks to buy the company.
- That leaves DoorDash as the one named suitor, and Rosenblatt expects a deal with a large rival to face regulatory scrutiny.
- Citi says the reported $16 billion to $17 billion sale price works out to about $65 a share.
- Instacart trades below its average forward P/E since its 2023 IPO while its free cash flow keeps rising, so it looks like a buy even without a deal.
Instacart (CART) shares fell 6% today, giving back much of Friday’s 9% jump on a report that the grocery-delivery company was exploring a sale. Bloomberg reported after Friday’s close that Uber (UBER) had walked away, and the two are no longer in talks.
Down to one named buyer
Late Friday, reported that Instacart had hired an investment bank and held early takeover talks with Uber and DoorDash (DASH). At a typical 30% to 40% premium, a deal could fetch roughly $16 billion to $17 billion, by the report’s estimate.
With Uber reportedly out, DoorDash is the one named suitor left.
Citi’s math says $65 a share
Citi analyst Ronald Josey, who keeps a Buy rating and a $58 price target, says that range works out to about $65 a share at the midpoint. That’s well above where the stock trades today.
Rosenblatt called Instacart a “prized asset despite being under attack by two industry goliaths,” Amazon and Walmart, and said other grocery companies could bid too. But it expects a deal with a large rival to draw regulatory scrutiny, since DoorDash and Uber compete directly with Instacart. Antitrust worries reportedly helped sink DoorDash’s 2021 talks to buy Instacart.
TIKR tracks 33 analysts on Instacart. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Instacart, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Instacart’s Analyst Ratings
Instacart doesn’t need a buyer
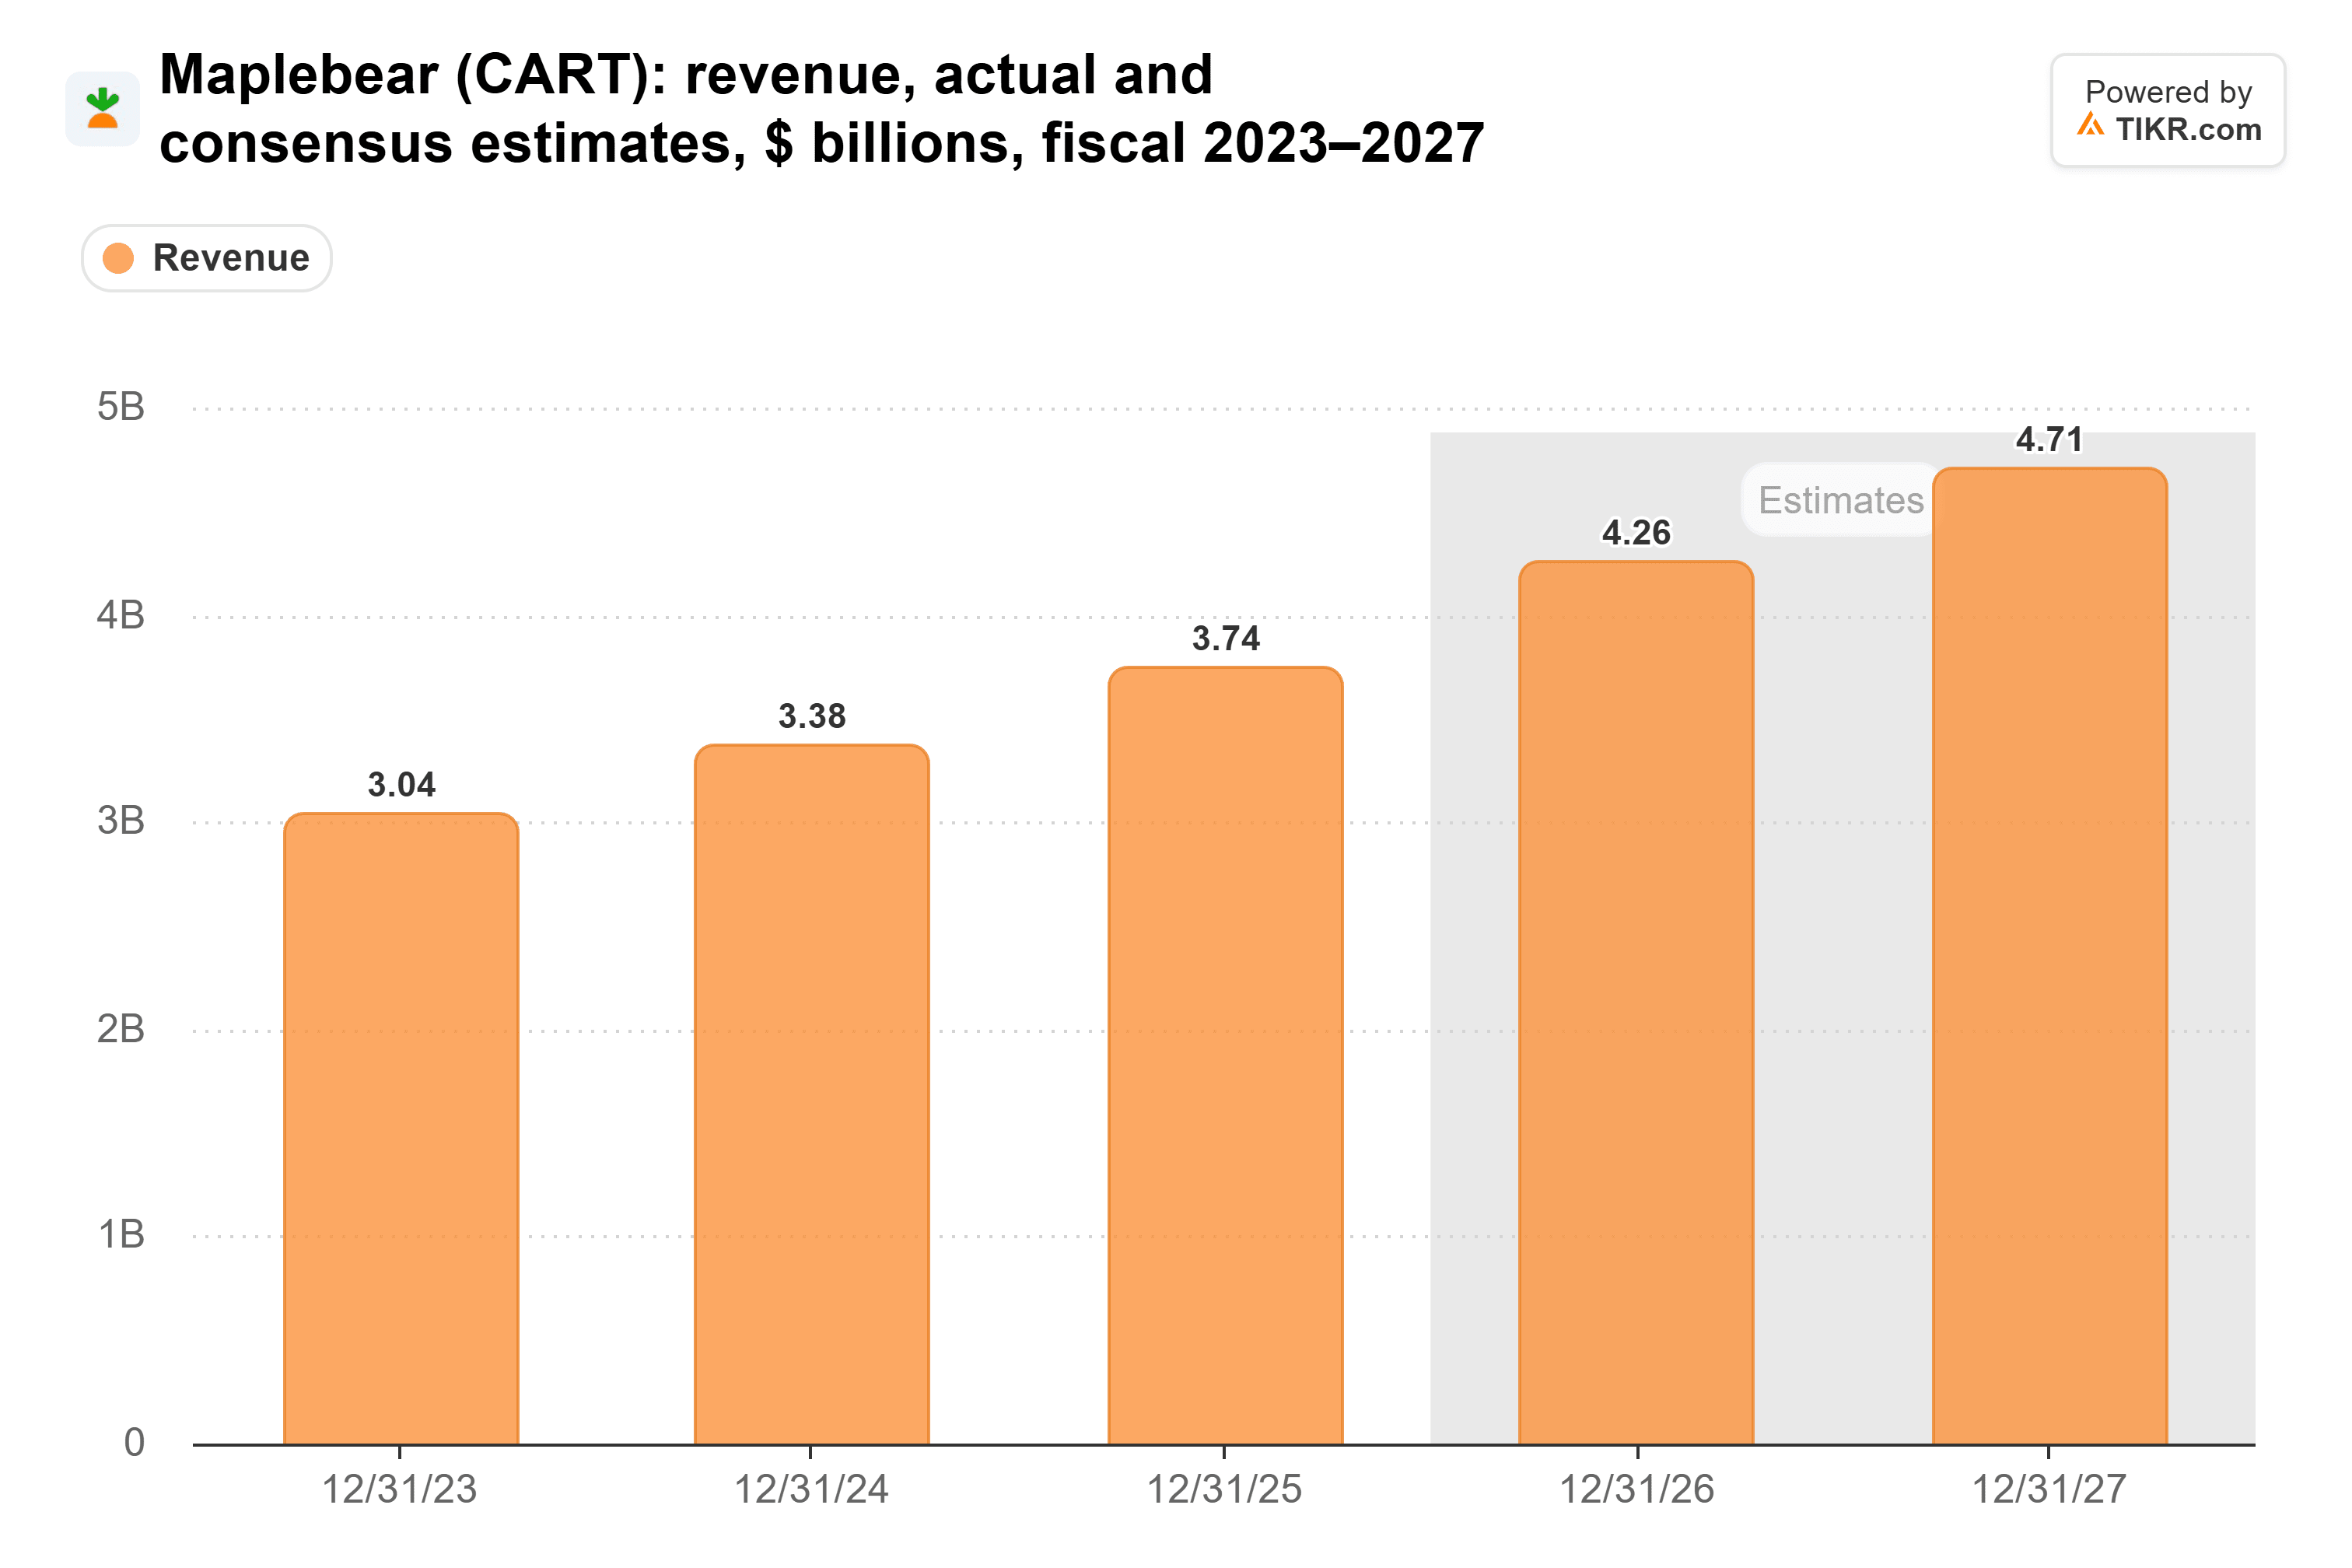
Without a deal, Instacart’s own numbers look solid. Free cash flow has grown every year since 2021, from negative $217 million to $910 million in 2025.

And Instacart generated $480 million of free cash flow in the second quarter alone. Management plans to spend most of this year’s free cash flow on buybacks.
Analysts expect sales to keep growing, to $4.71 billion in 2027 from $3.74 billion in 2025.
Yet the stock isn’t priced for much of a deal. At Friday’s close, Instacart traded at 12x forward earnings, below its 13x average since its 2023 IPO and far off its high of nearly 20x in May 2024.

After today’s drop, it’s cheaper still.
Uber’s exit is priced in
Uber walking away takes one bidder off the table, and today’s drop prices that in. My take: at this multiple, with free cash flow still rising, Instacart looks like a buy on its own numbers, and any deal would be a bonus.
Of course, Amazon and Walmart aren’t going anywhere. Third-quarter results, due in early November, will show whether Instacart can keep growing while it fends them off.
So what is Instacart stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Instacart could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!