Key Stats for Thermo Fisher Stock
- Current Price: $641.39
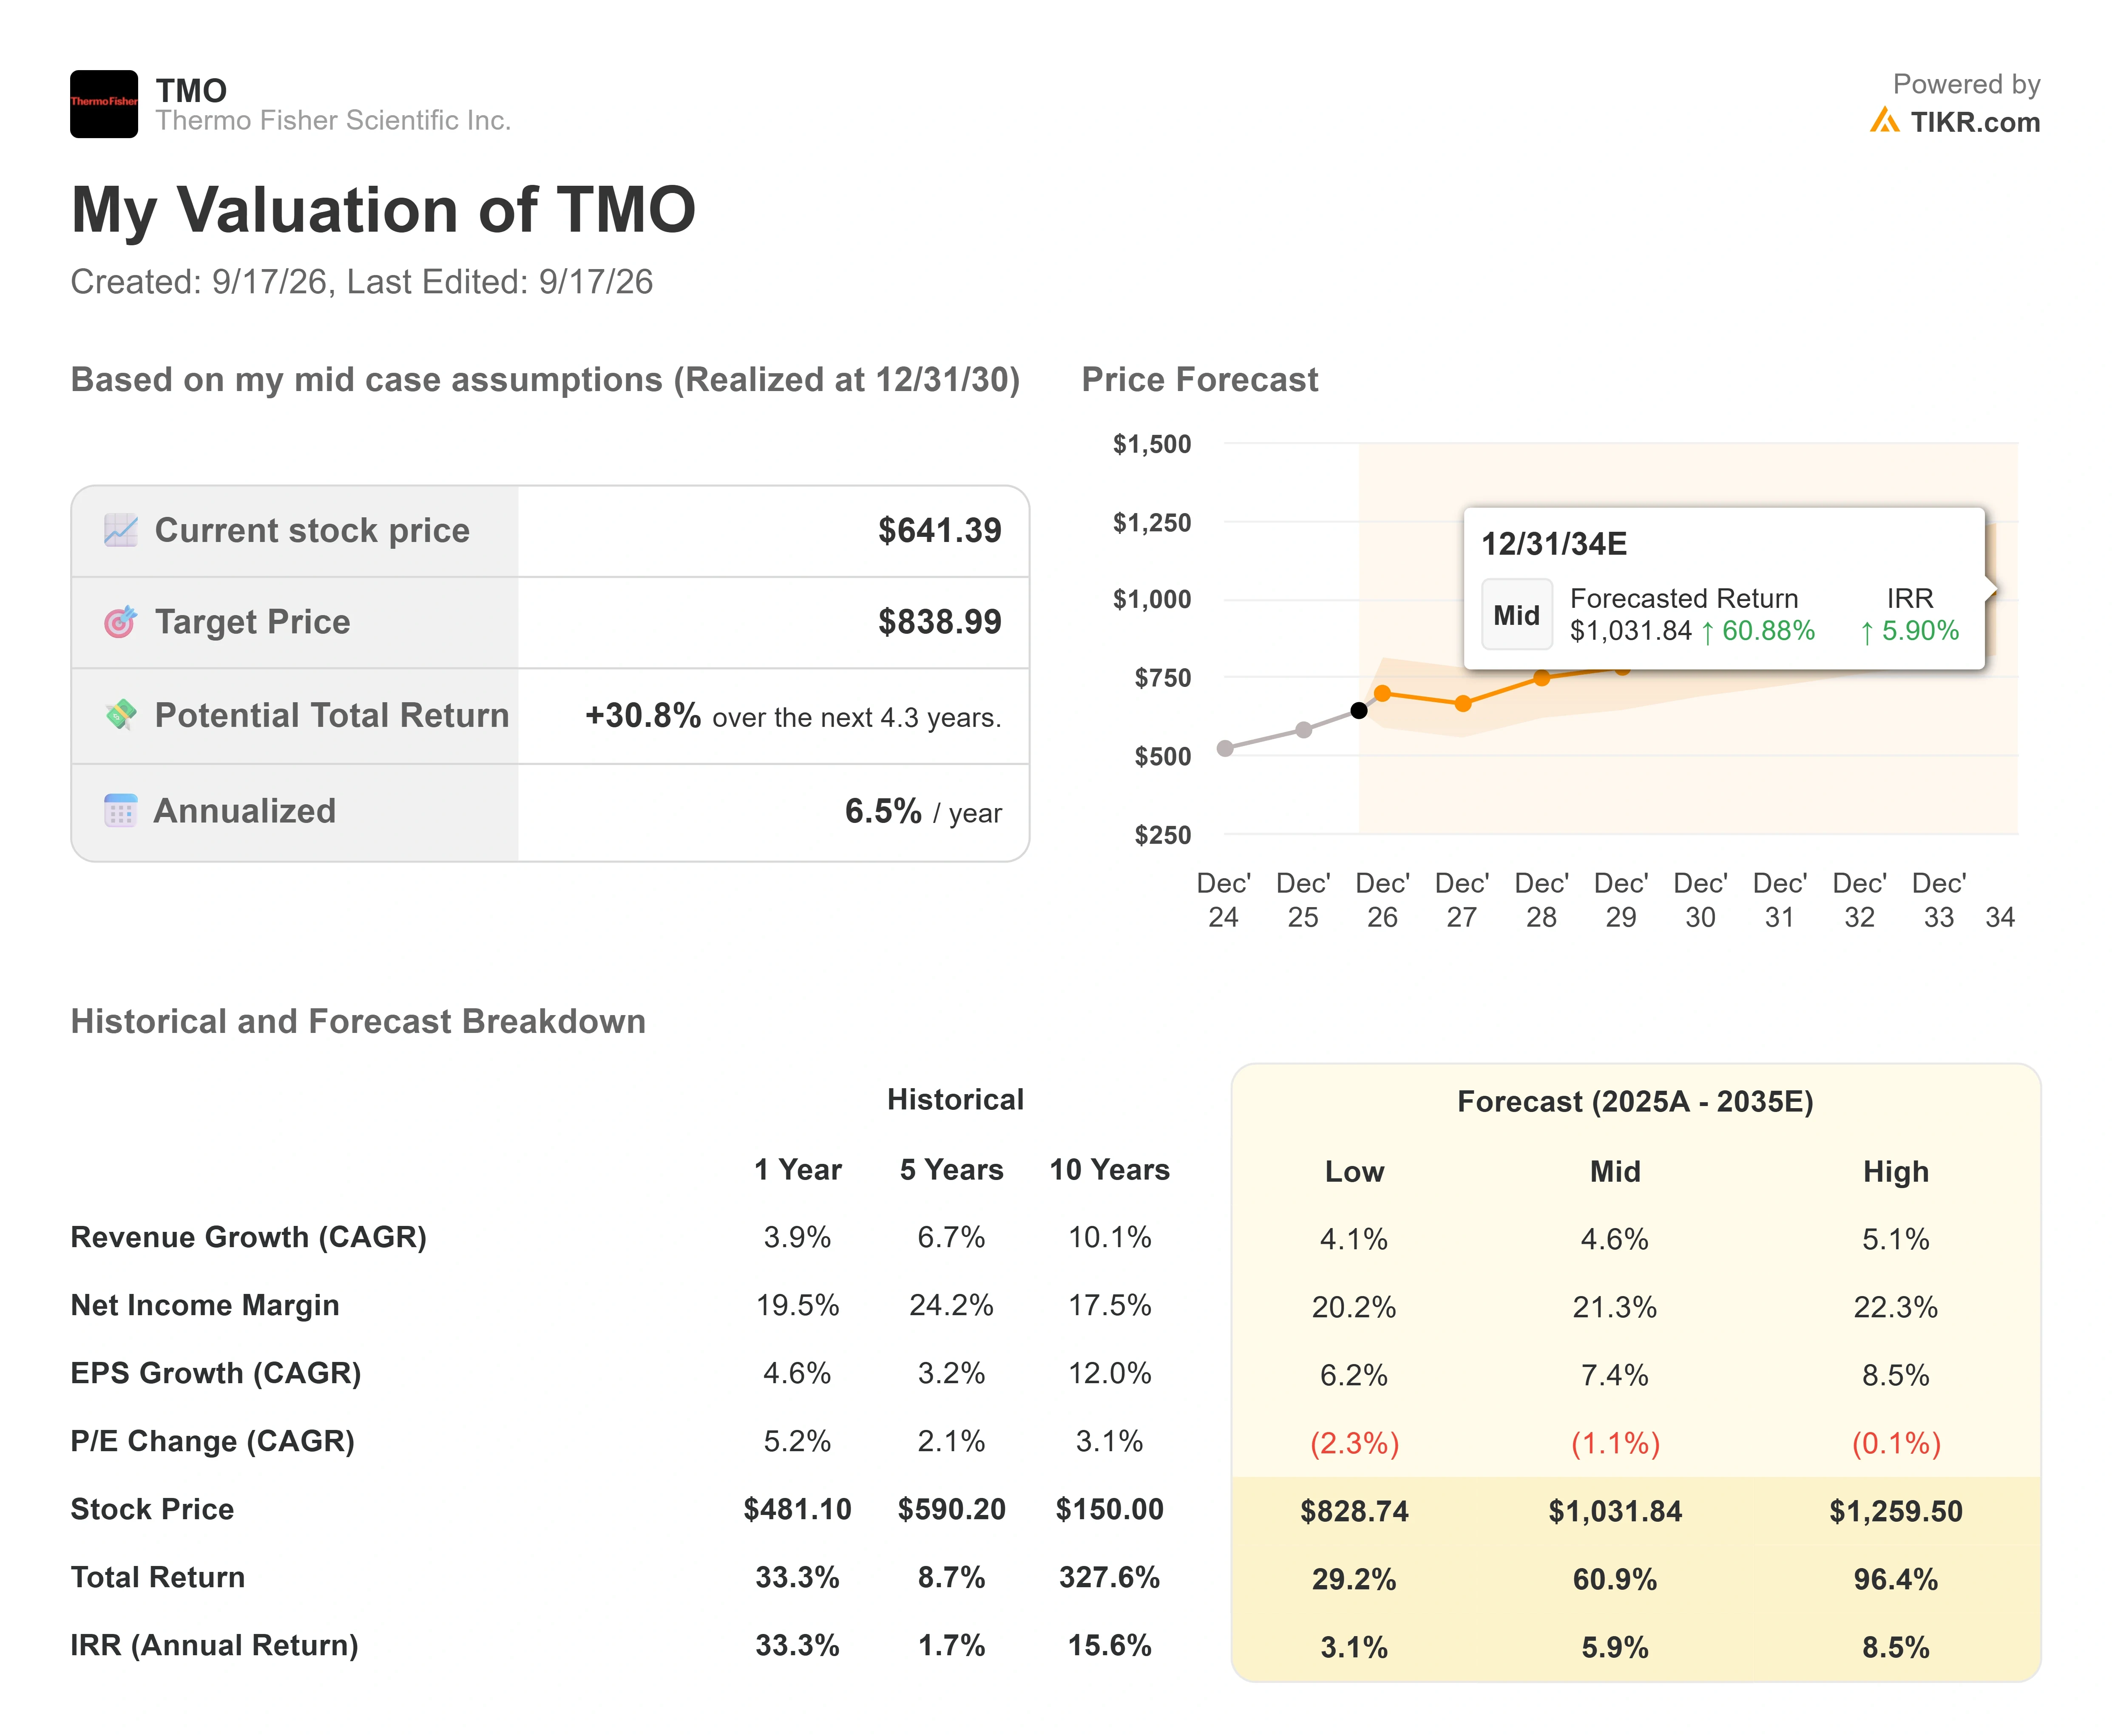
- Target Price (Mid): ~$839
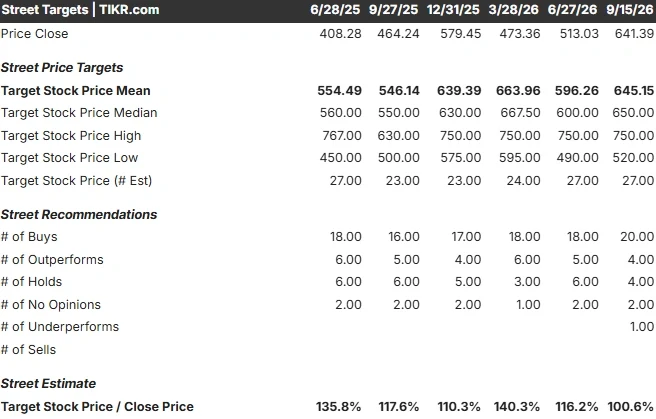
- Street Target: ~$645
- Potential Total Return: ~31%
- Annualized IRR: ~7% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
Thermo Fisher Scientific (TMO) has become the rare large-cap where three analysts studying the same company cannot agree on direction. On September 3, CLSA started coverage at Outperform with a $748 target. On September 9, UBS upgraded the stock to Buy from Neutral and lifted its target to $730 from $540, a move that came as the firm assumed coverage under a new analyst rather than as a mid-cycle change of heart. Bernstein, meanwhile, reiterated a Hold at $575. The clearest read on why the bulls are right came six days later, when CEO Marc Casper walked through the funding cycle in detail at a Morgan Stanley conference.
The Street mean sits at roughly $645, almost exactly that level, which tells you the average masks a real fight underneath it. The disagreement is not about the past quarter, which everyone concedes was strong. It is about whether the growth reacceleration management keeps describing is durable enough to justify paying up for the stock now.
The Bull Call Rests on 2027
The UBS call is worth reading carefully, because the $190 target jumped to $730 arrived through a transfer in analyst coverage, not a bank publicly reversing itself. Assuming coverage, let the new analyst reset the view in one step. The substance, as reported by TheStreet, leaned on the 2027 model rather than the recent print: a durable return to 5% to 6% organic growth, at least 50 to 70 basis points of operating margin expansion, and double-digit EPS growth, supported by improving pharma and biotech funding, bioprocessing, reshoring, AI-driven research spend, and stabilization in China and academic markets.
Second-quarter revenue reached $11.99 billion, up 10.5% year over year with 5% organic growth, two points ahead of the guidance management set a quarter earlier. Adjusted EPS came in at $6.03, up 12.5% and $0.32 ahead of the Street, and the company raised full-year guidance on both lines. Bernstein’s $575 holdout is the mirror image: with the stock at 24.42x NTM P/E, the upper end of its recent range, the recovery may already be priced.
See historical and forward estimates for Thermo Fisher stock (It’s free!) >>>
What Casper Just Said the Upgrade Is Betting On
The mechanism behind the bull case showed up at the Morgan Stanley Global Healthcare Conference on September 15, where Casper described biotech funding turning from sentiment into spending. “Usually, when funding happens, it usually takes 2 to 3 quarters, depending on the business, for that funding to flow,” he said, tracing money that moves first into clinical research, then into lab supplies through Fisher Scientific, then into high-value reagents.
Two under-followed drivers add to it. On China, after his second visit of the year in August, Casper said the innovative biotech industry there increasingly wants Western partners to de-risk licensing deals, the business returned to growth in Q2, and it could over time grow at least in line with the company average. Since guidance assumes little from China, that is upside the model does not carry.
Reshoring is the other: Casper laid out a three-phase ramp, from CDMO contracts that need no new plants, to expansions of existing facilities, to greenfield builds that drive one-time equipment and lab-stocking demand into 2027 and 2028. As the industry leader across instruments, reagents, and outsourced services, Thermo Fisher holds a wide economic moat that keeps customers inside its ecosystem as those dollars flow.
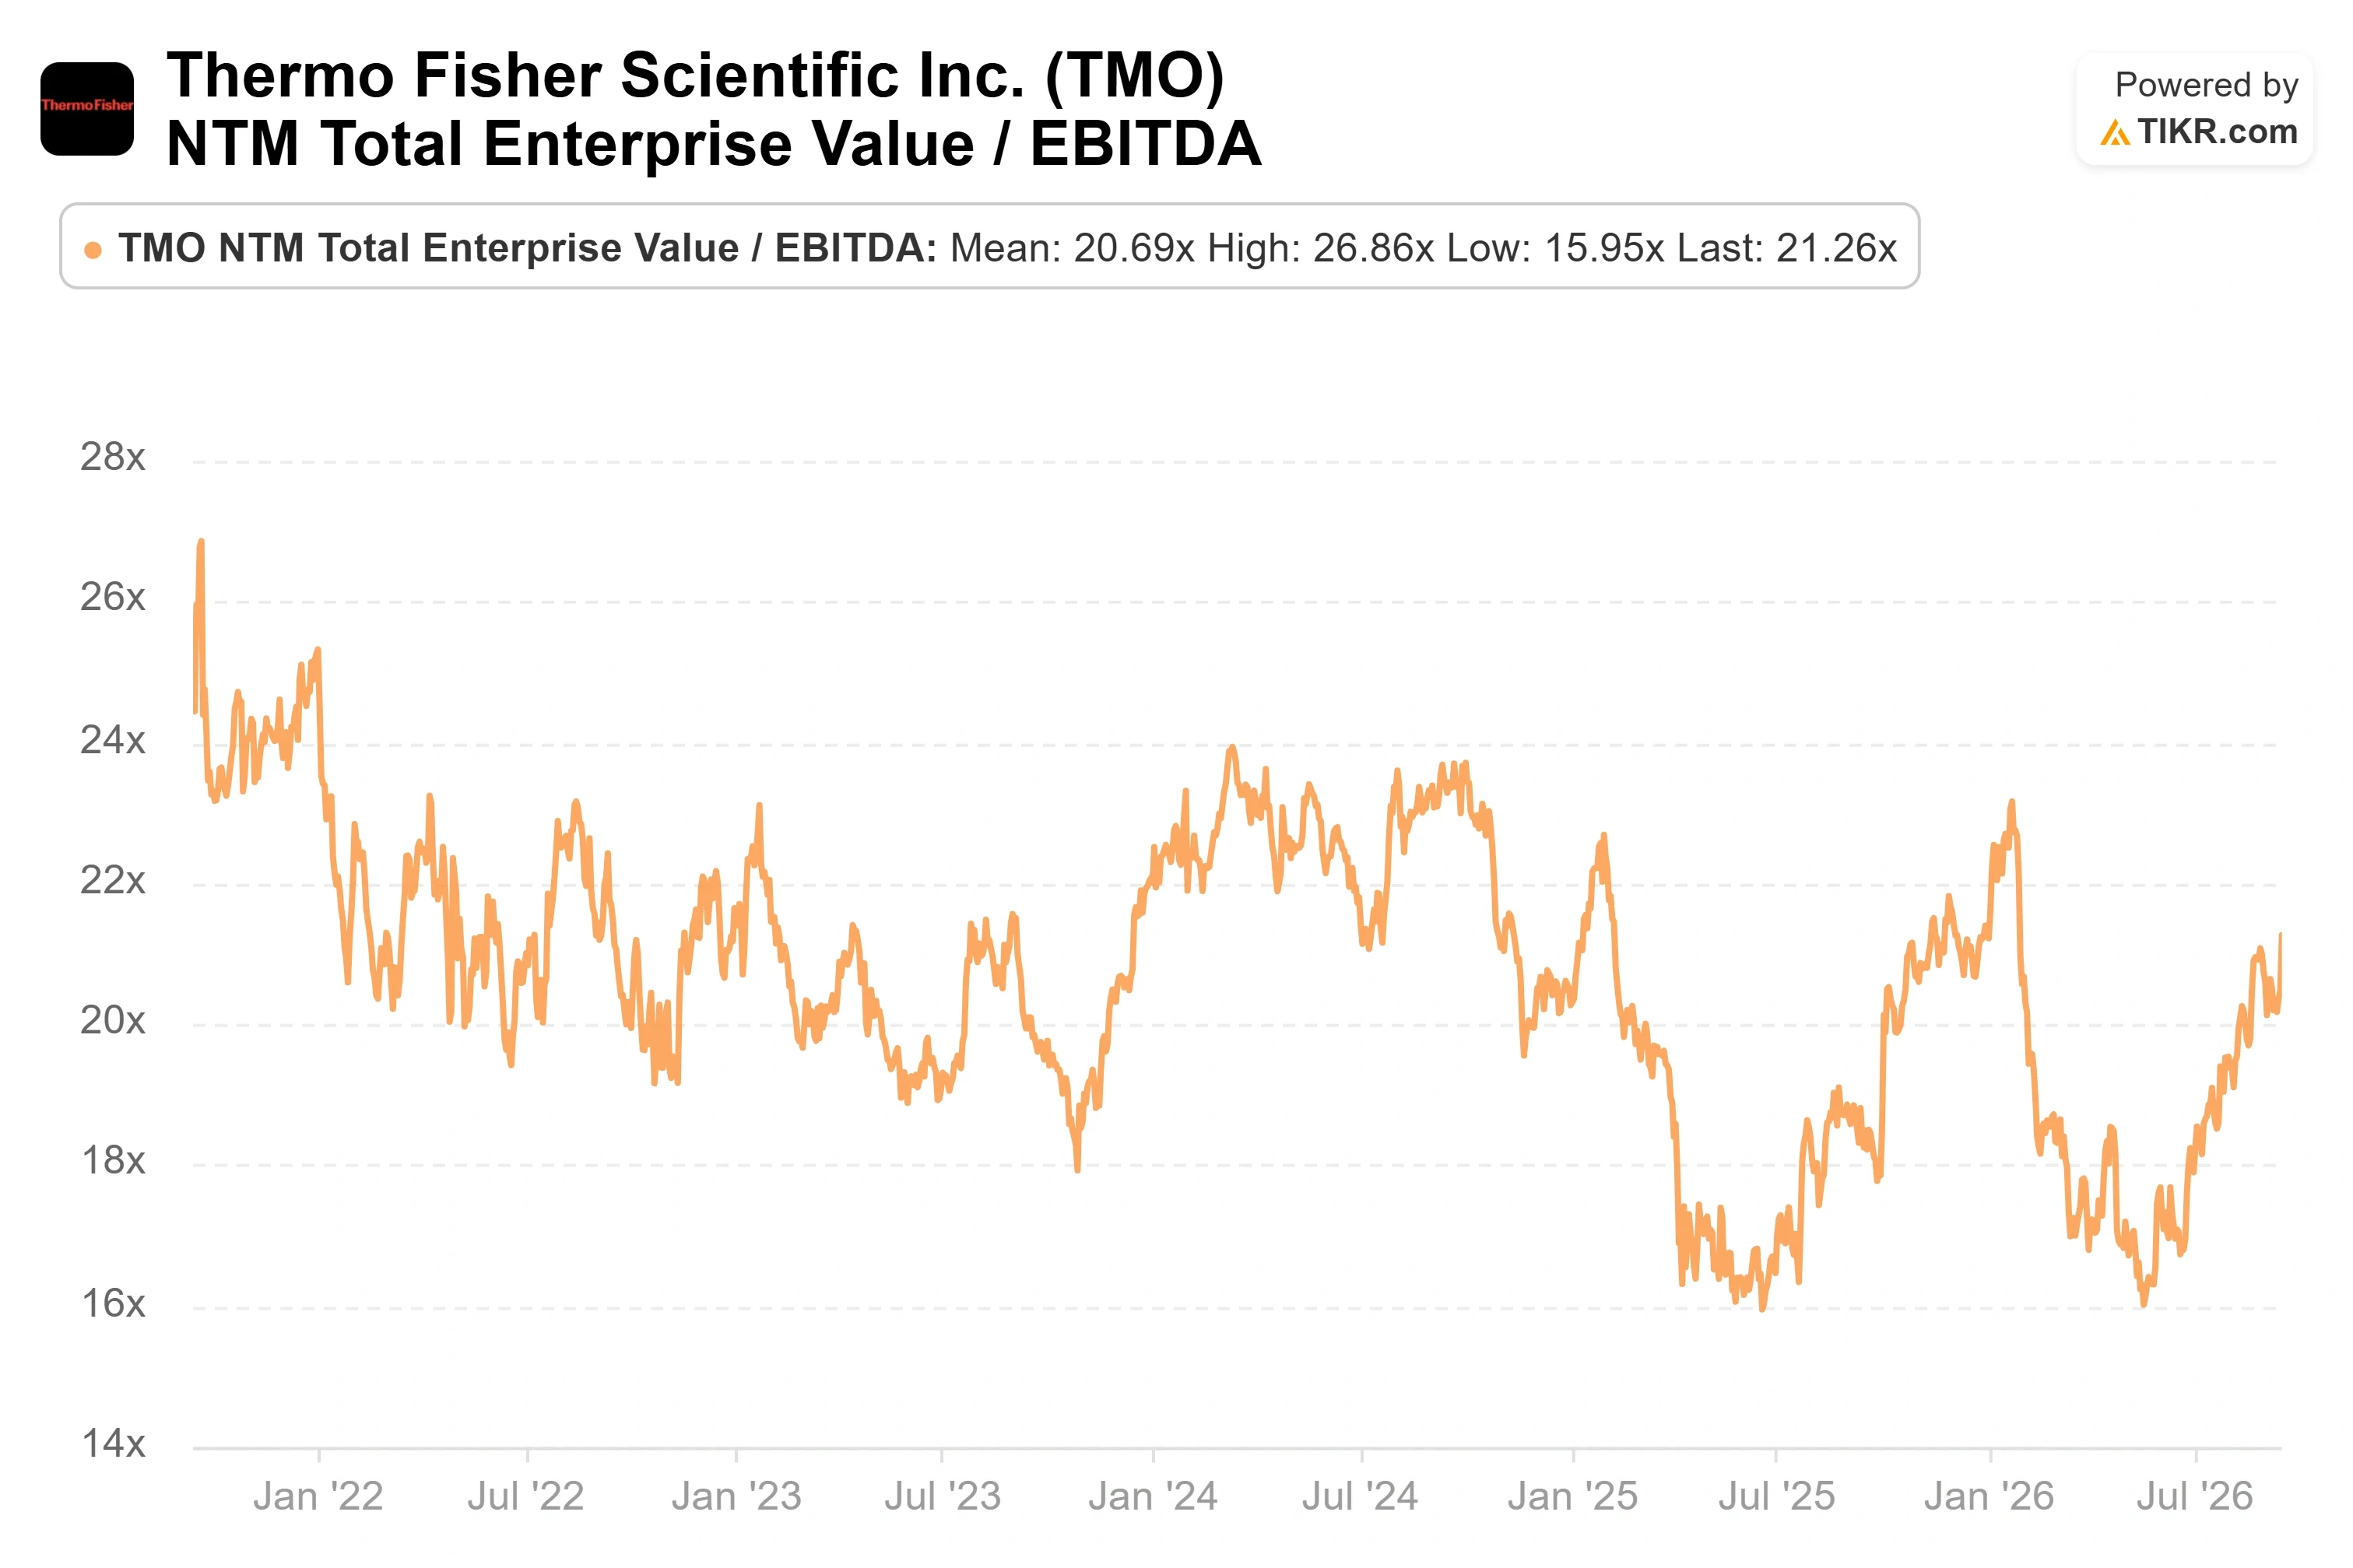
Thermo Fisher’s 21.26x NTM EV/EBITDA sits below Illumina at 24.53x and near Waters at 19.53x, while its 5.62x NTM EV/revenue lands mid-pack against IQVIA at 3.28x and Medpace at 5.83x. For the largest and most diversified franchise in the group, with organic growth recovering, that premium is defensible only if earnings keep climbing. The stock moves from here on profit growth, not on a higher multiple.
See how Visa Inc. performs against its peers in TIKR (It’s free!) >>>
TIKR Advanced Model Analysis
- Current Price: $641.39
- Target Price (Mid): ~$839
- Potential Total Return: ~31%
- Annualized IRR: ~7% / year
See analysts’ growth forecasts and price targets for Thermo Fisher stock (It’s free!) >>>
TIKR’s mid-case values Thermo Fisher at around $839, roughly 31% total upside, or about 7% annualized over the next 4.3 years. Two revenue drivers carry it: mid-single-digit organic growth reaccelerating toward the company’s 7% long-term target as biotech funding flows through, and the scaling contribution from the Clario and bioproduction franchises. The margin driver is adjusted operating margin expansion, with net income margin modeled to widen toward roughly 21%.
The upside is that China turns from a modeled non-contributor into a real tailwind while reshoring adds one-time demand through 2027 and 2028. The primary risk is the multiple: near the top of its historical range, any stumble in the growth reacceleration would compress the valuation faster than earnings can offset. That is why the Street mean of about $645 sits close to today’s price even as the longer-horizon model points higher.
Conclusion
The tie-breaker is the third-quarter print on October 28. Management guided the second half to roughly 4% organic growth, so a number holding at or above that level would validate the reacceleration CLSA and UBS are paying for, while a slip toward 2% to 3% would hand the argument to Bernstein. One more quarter of orders running ahead of revenue makes the bulls look early rather than late.
See what stocks billionaire investors are buying so you can follow the smart money with TIKR.
Should You Invest in Thermo Fisher?
The only way to really know is to look at the numbers yourself. TIKR gives you free access to the same institutional-quality financial data that professional analysts use to answer exactly that question.
Pull up Thermo Fisher, and you’ll see years of historical financials, what Wall Street analysts expect for revenue and earnings in the quarters ahead, how valuation multiples have moved over time, and whether price targets are trending up or down.
You can build a free watchlist to track Thermo Fisher alongside every other stock on your radar. No credit card required. Just the data you need to decide for yourself.
Analyze Thermo Fisher on TIKR Free →
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!