Key Stats for SBUX Stock
- Past week performance: Consolidating
- 52-week range: $78 to $111
- Valuation model target price: $118
- Implied upside: 21.8% over 2.0 years
Weigh Starbucks against your other holdings with TIKR’s Guided Valuation Model (It’s free) >>>
A Japan Sale Would Mark the Next Step in a Broader Reset
Starbucks (SBUX) is exploring the sale of a majority stake in its Japan business, Reuters reported this week. The deal could value the unit at roughly $3 billion. Shares have held mostly flat over the past week near $97, but the news adds another chapter to a portfolio overhaul that has defined 2026.
Japan is Starbucks’ largest company-operated market outside the U.S., with 1,883 stores accounting for nearly 9% of its global footprint. Starbucks acquired the business outright from local partner Sazaby League in 2014 for about $914 million. A sale now would echo what happened in China earlier this year, when Starbucks finalized a joint venture with Boyu Capital in April, giving Boyu 60% ownership of its China stores.
Both moves point toward the same goal. Starbucks wants lighter capital exposure in markets where it has already built scale, freeing up cash for its core U.S. turnaround. That turnaround has shown real progress, since Q3 results in late July delivered global comparable sales growth of 7.9% and adjusted EPS of $0.85, beating estimates by roughly 30%.
Management raised full-year EPS guidance to a range of $2.55 to $2.65 after that report. A Reuters analysis this week captured the shift in investor focus well, noting that CEO Brian Niccol has brought customers back to stores, but investors now want to see those gains show up in margin.
Niccol told analysts on the Q3 call that operational improvements across store design and staffing are starting to lift throughput. Going forward, the Japan decision will likely be read as a signal of how aggressively Starbucks intends to pursue that margin story.
Follow Starbucks’ margin recovery quarter by quarter (It’s free) >>>
Is SBUX Stock Undervalued?
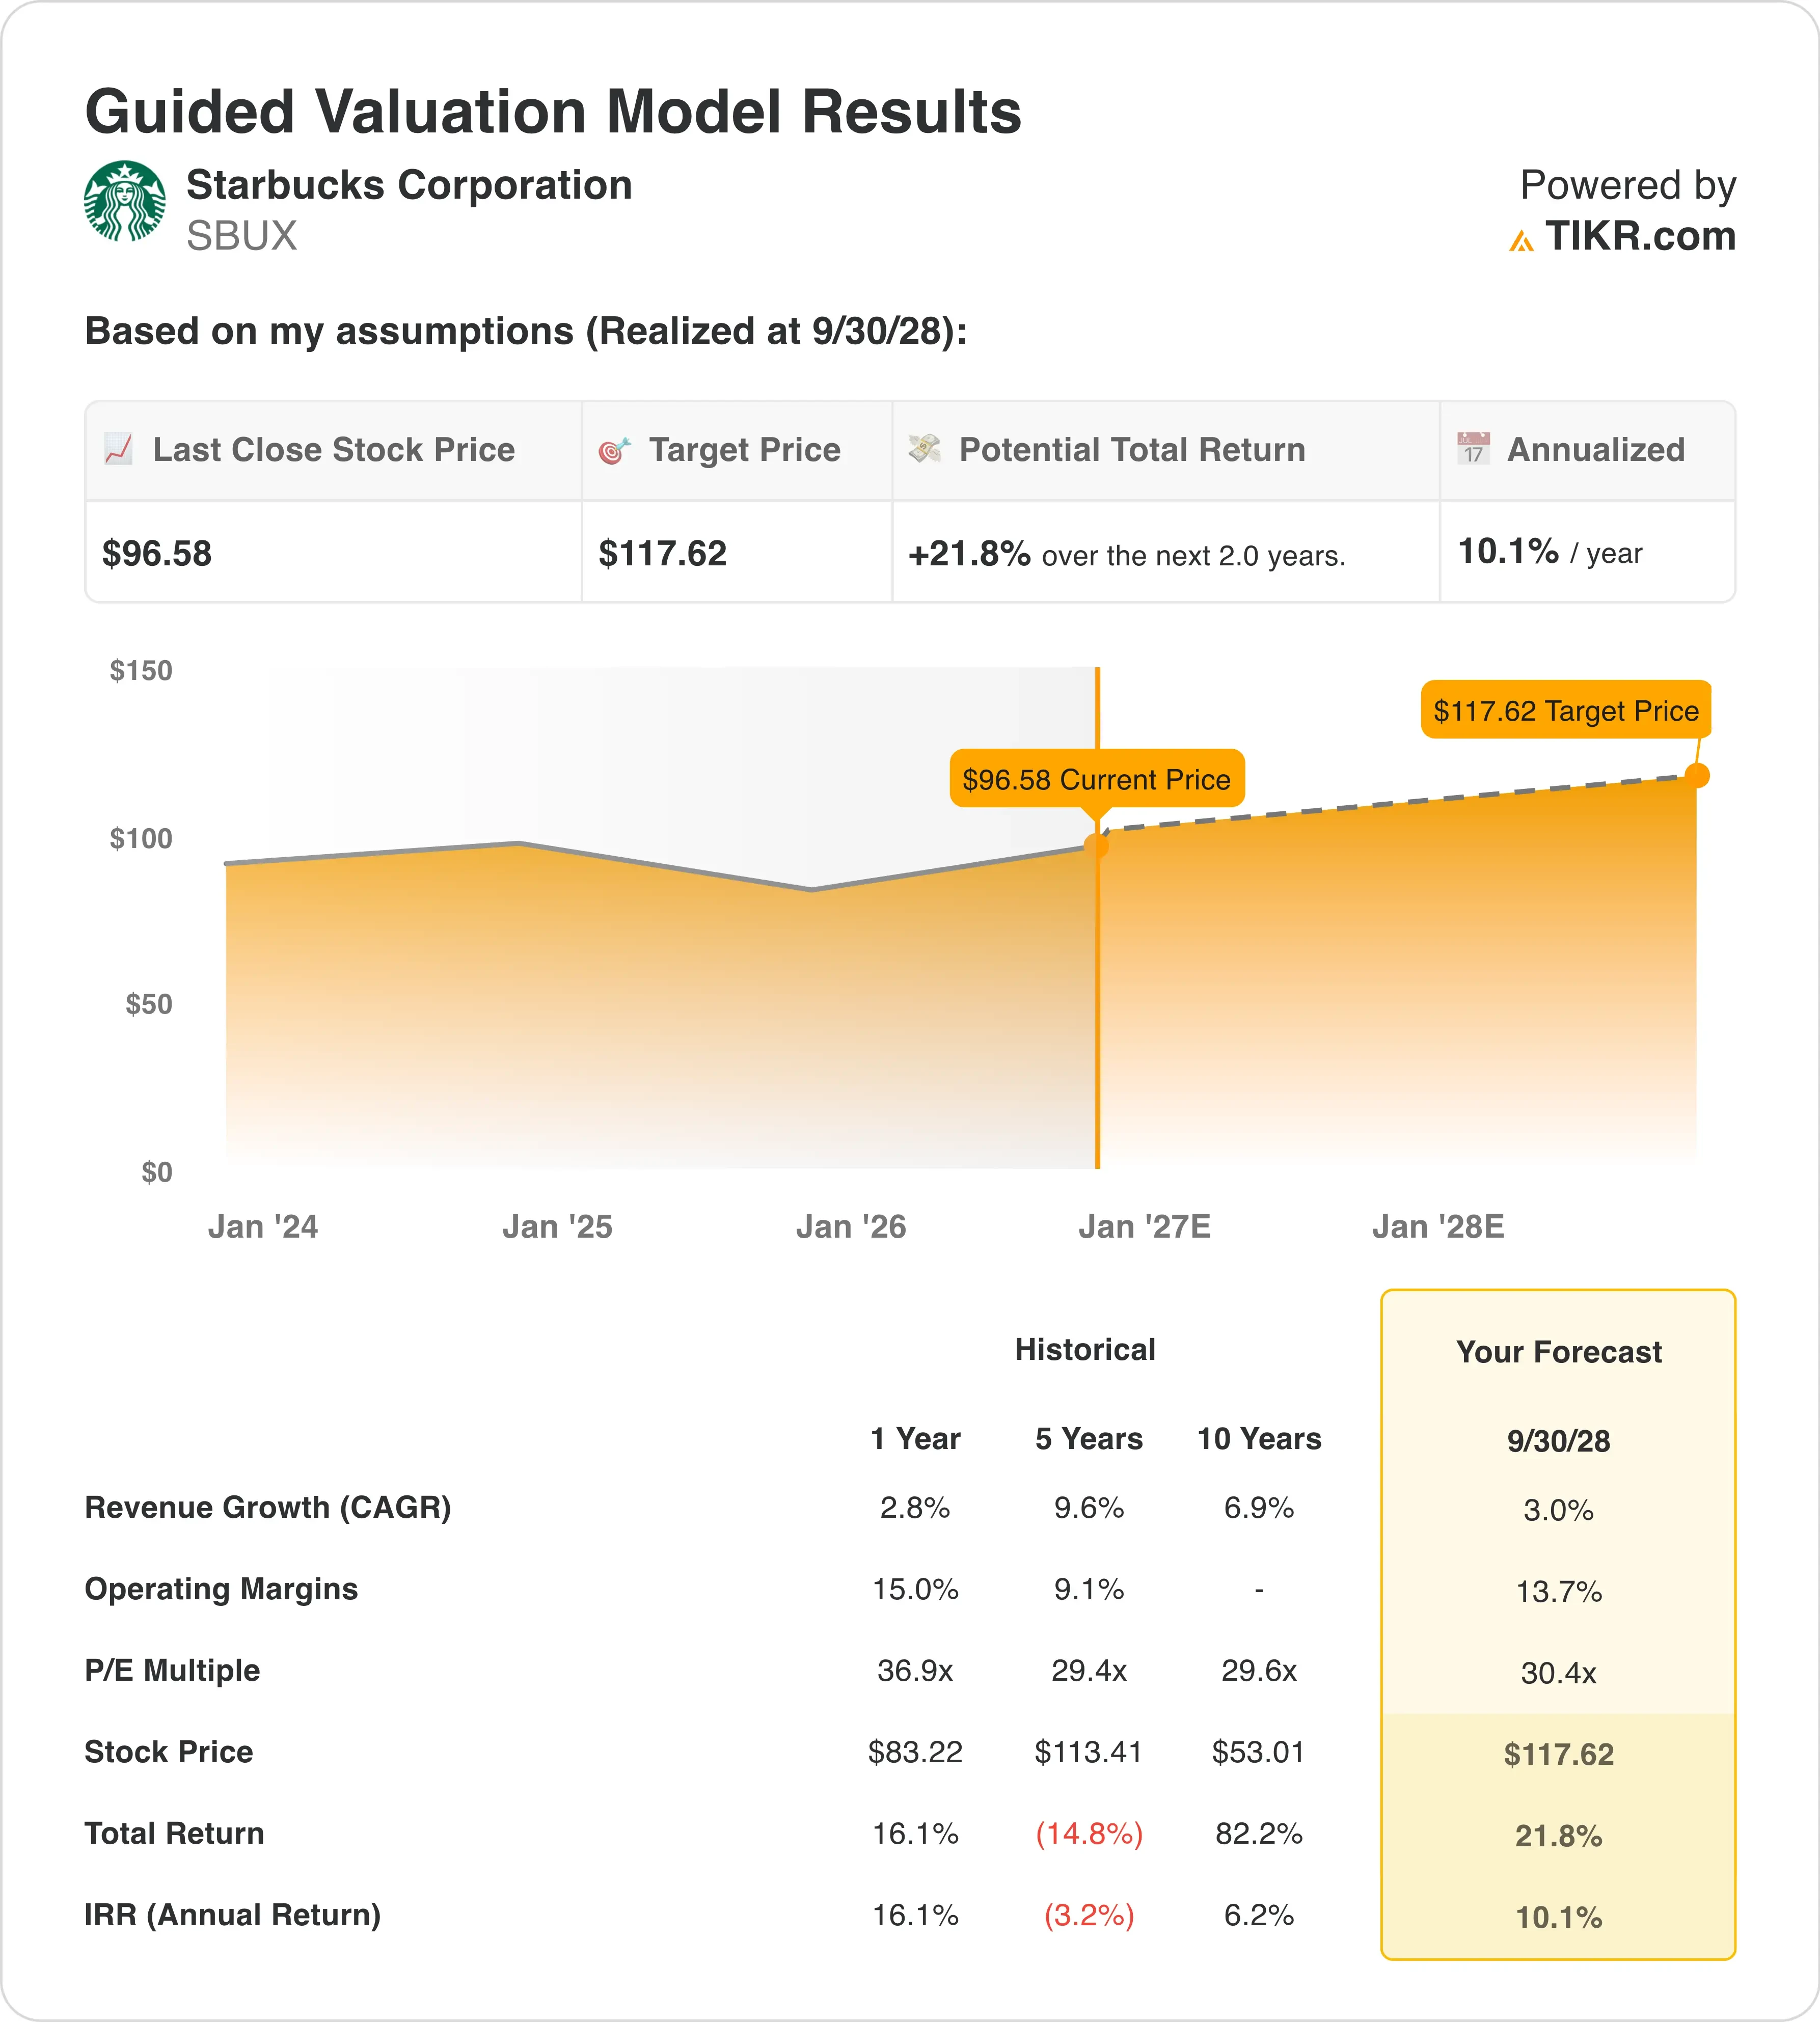
Under valuation model assumptions realized through 9/30/28, the stock is modeled using:
- Revenue Growth (CAGR): 3.0%
- Operating Margins: 13.7%
- Exit P/E Multiple: 30.4x
Based on these inputs, the model estimates a $118 target price, implying 21.8% total upside from the current share price and a 10.1% annualized return over the next 2.0 years.
That annualized return sits in moderately attractive territory. It stays above the 5% mark that signals weak upside but below the 15% level that would flag a clear bargain. Revenue growth of 3% is modest, but the real opportunity sits in the margin line, since Starbucks’ operating margin has compressed sharply from its historical range in the low twenties down to the low teens.

Every point of margin recovery Niccol’s team captures directly supports the model’s upside case. The Japan and China moves both remove lower-margin, capital-intensive store operations from the consolidated results, which should lift blended margins even before any further operational gains.
A 30.4x forward multiple is not cheap for a company growing revenue this slowly, so execution risk remains real. But the model suggests the market has not yet given Starbucks full credit for the margin recovery management has already started to show.
Estimate a company’s fair value instantly (Free with TIKR) >>>
Starbucks Against McDonald’s and Luckin Coffee
McDonald’s (MCD) remains the clearest benchmark for a mature, high-margin restaurant operator, and the gap is stark. McDonald’s runs a roughly 95% franchised model, which produces an operating margin near 44%. Starbucks trails at roughly 8% to 9% on a trailing basis, since it remains heavily company-operated and absorbs labor and coffee cost inflation directly.

That structural difference shows up in valuation too. McDonald’s trades around a 22x forward P/E, while Starbucks commands a richer 32.8x NTM multiple, reflecting the market’s willingness to pay for turnaround optionality rather than current profitability.
Luckin Coffee (LKNCY) represents a different kind of pressure, concentrated in China. Luckin has expanded aggressively through low-price, high-frequency store formats, and that growth has come at the cost of thin self-operated margins, which fell sharply during its most intense expansion phases. Starbucks has taken a steadier approach in China, still posting comparable sales growth near 7% even as Luckin undercuts it on price.
That contrast offers useful context for the Japan decision. Starbucks appears to be choosing capital discipline over direct ownership in markets where local rivals compete hard on price.
Track whether stronger comps translate into sustained margin expansion >>
What’s Driving SBUX Stock Going Forward?
The most immediate catalyst is how the Japan process unfolds. Sources say a formal sale process could begin as soon as Q4, and the eventual valuation will show how markets price Starbucks’ international assets relative to its core U.S. business.
Fiscal Q4 earnings, expected around October 27, will be the next major test of whether the margin recovery Niccol promised is actually showing up. That comes after management raised full-year guidance to $2.55 to $2.65 per share.
Labor relations remain an ongoing overhang. A federal appeals court narrowed an NLRB case against Starbucks earlier this month, but union organizing has continued across U.S. stores, and any escalation could complicate the labor cost side of the margin story.
Longer term, investors will watch whether capital freed up from Japan and China gets redeployed into U.S. store remodels, since that reinvestment is central to sustaining the traffic recovery Niccol has already delivered.
Track Starbucks’ next earnings date and model your own scenario (Free with TIKR) >>>
Should You Invest in Starbucks?
The only way to really know is to look at the numbers yourself. TIKR gives you free access to the same institutional-quality financial data that professional analysts use to answer exactly that question.
Pull up SBUX, and you’ll see years of historical financials, what Wall Street analysts expect for revenue and earnings in the quarters ahead, how valuation multiples have moved over time, and whether price targets are trending up or down.
You can build a free watchlist to track SBUX alongside every other stock on your radar. No credit card required. Just the data you need to decide for yourself.
Analyze SBUX stock on TIKR Free→
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!