Key Stats for LITE Stock
- Past week performance: +9.6%
- 52-week range: $145 to $1,086
- Valuation model target price: $1,653
- Implied upside: 97.1% over 2.8 years
Model Lumentum’s growth curve yourself with TIKR’s Guided Valuation Model (It’s free) >>>
AI Optics Demand Keeps Outrunning Forecasts
Lumentum (LITE) jumped roughly 10% this week as chip stocks broadly rallied on bullish sector commentary from Citi. Rival optics supplier IQE’s earnings reinforced the same message investors have heard all year, since AI data center demand for optical parts keeps exceeding supply. Shares now trade near $919, well above their 52-week low of $145.

The rally builds on an already strong quarter. Lumentum’s Q4 fiscal 2026 results, reported in mid-August, showed revenue more than doubling to $1.01 billion, up 109% year over year, alongside adjusted EPS of $3.23. Non-GAAP gross margin expanded to 50.4%, a jump of more than 1,200 basis points from the prior year, and operating margin reached 36.6%.
Guidance for the current quarter was even more aggressive. Management guided revenue to $1.225 billion to $1.275 billion, implying roughly 130% growth, with adjusted EPS between $4.05 and $4.35. Executives said on the call that laser chips and high-speed transceivers remain effectively sold out for the foreseeable future.
That supply crunch traces back to a March partnership with Nvidia (NVDA), which included a $2 billion equity investment and multi-year purchase commitments for advanced optical components. If LITE stock keeps delivering growth like this, the gap between price and the model’s target could close faster than expected.
Size up Lumentum’s margins against the rest of the optics sector (It’s free) >>>
Is Lumentum Stock Still Cheap After This Run?
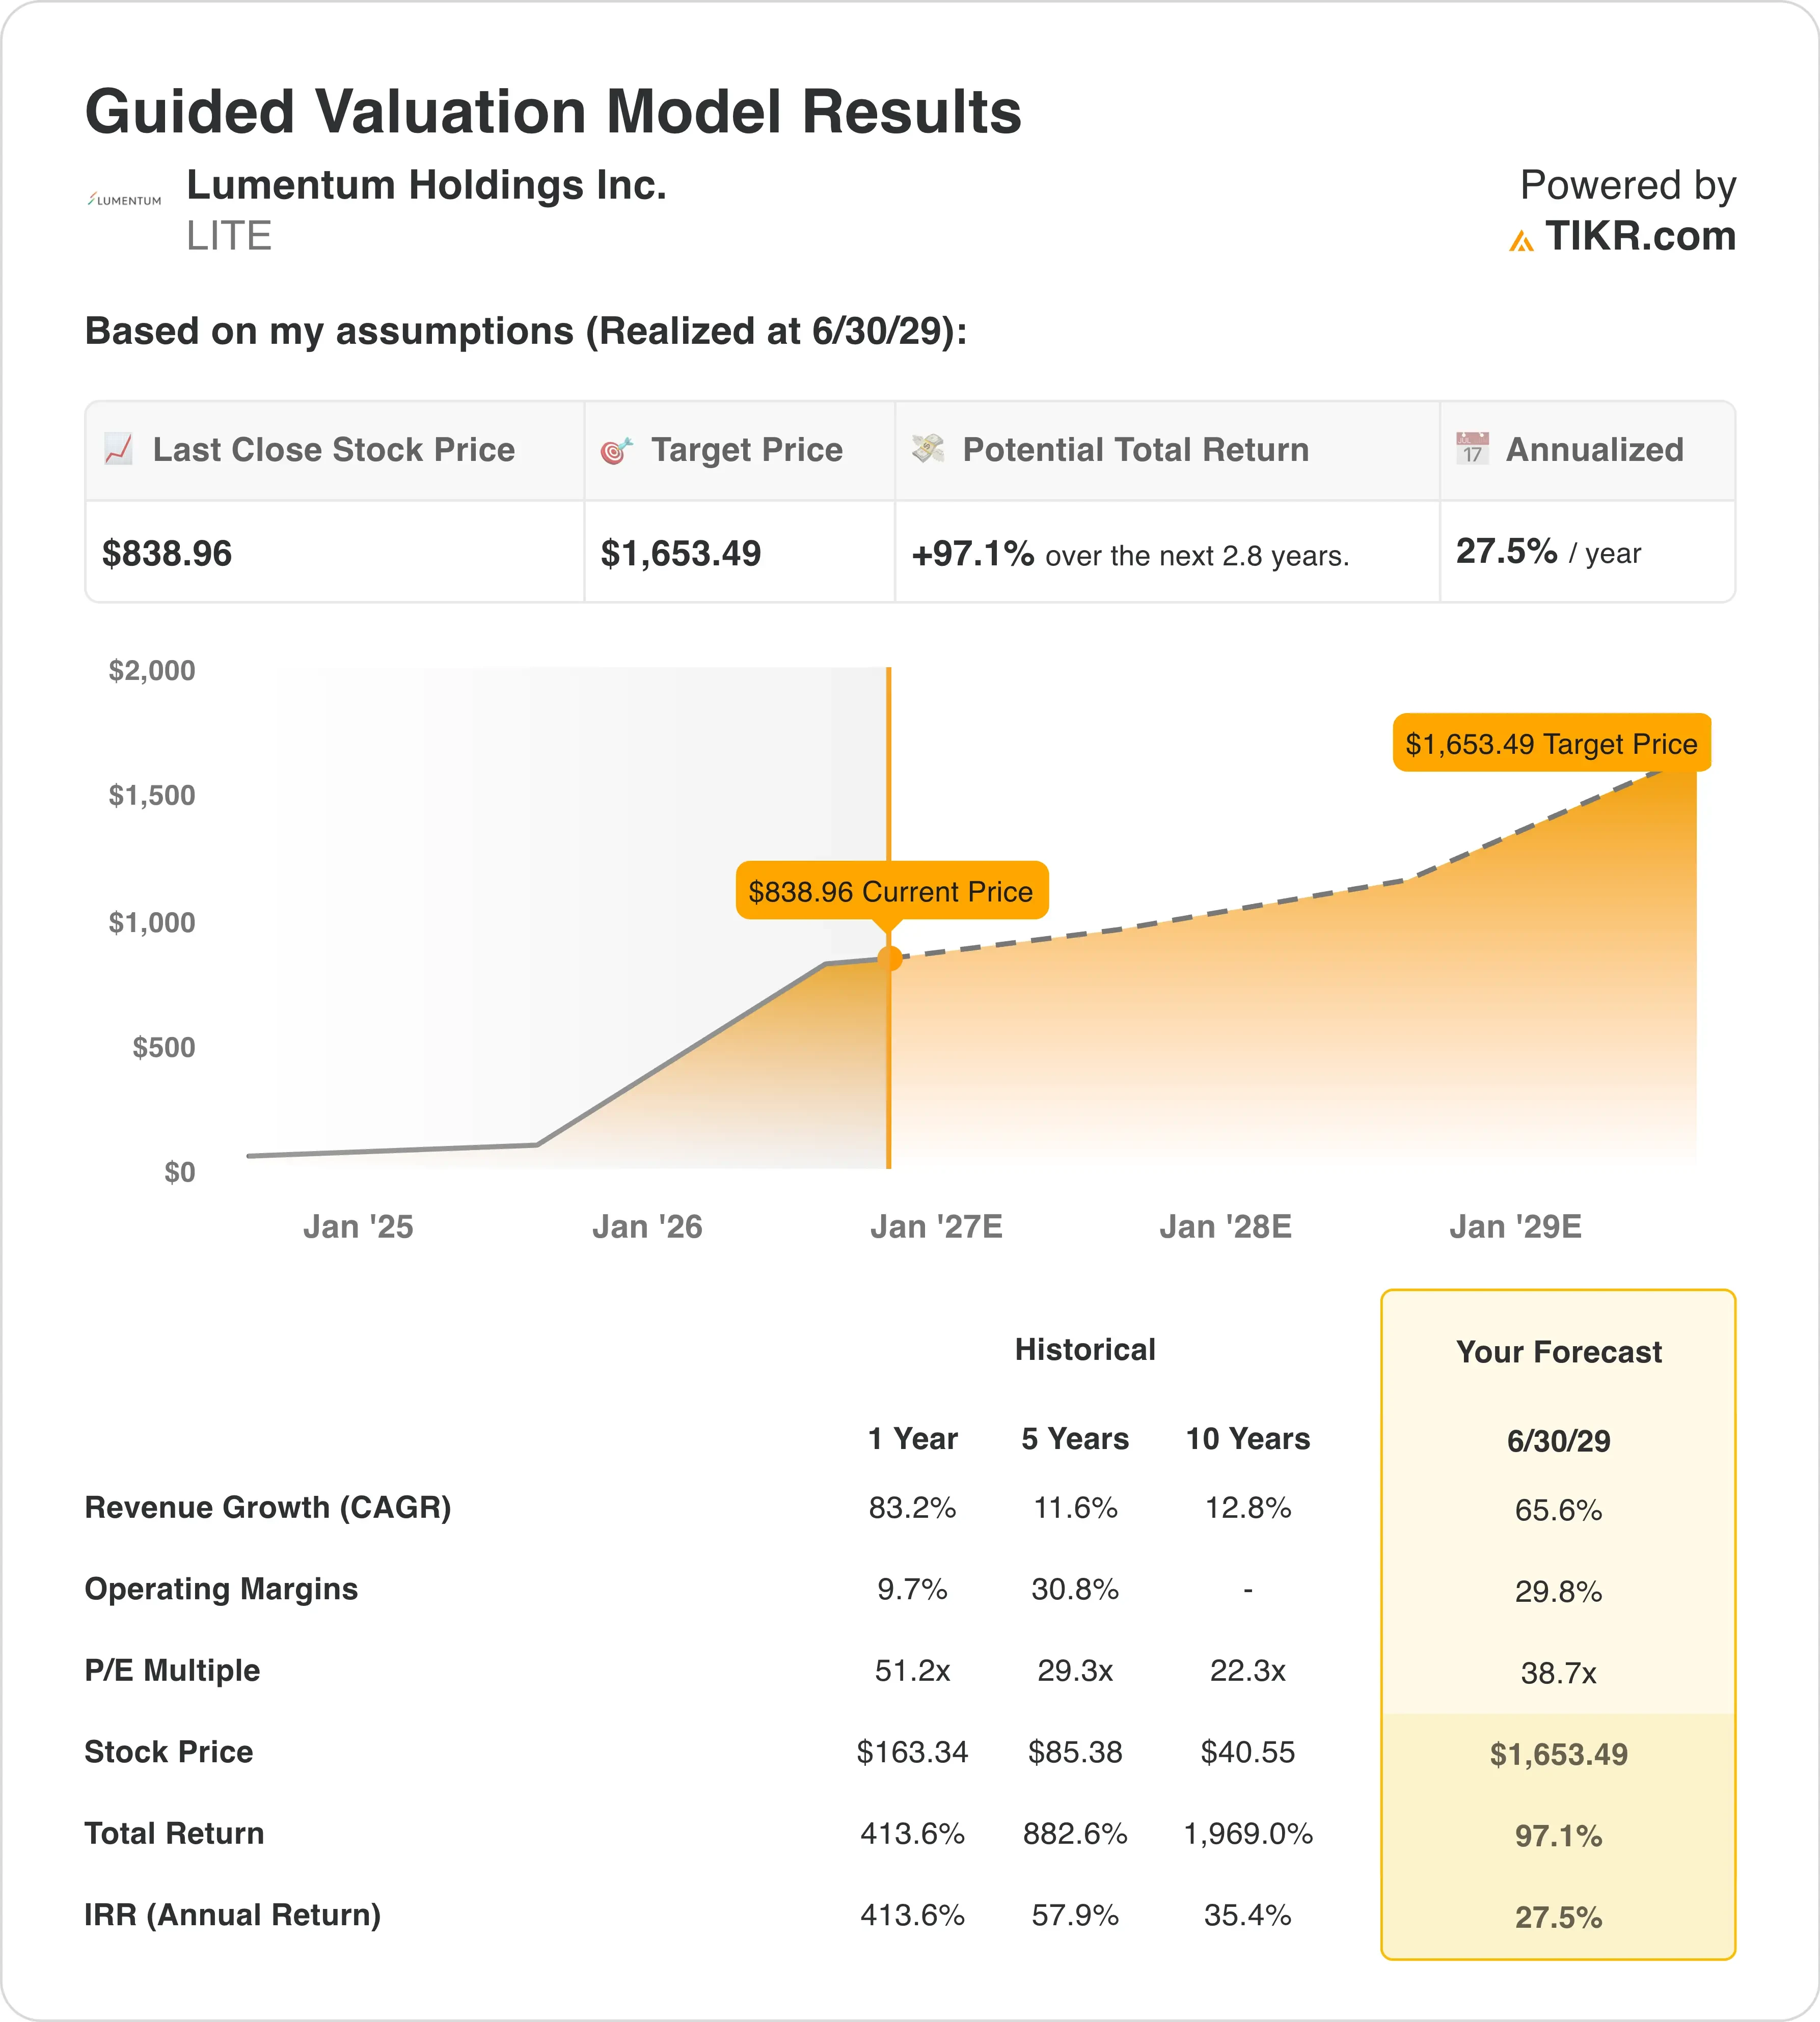
Under valuation model assumptions realized through 6/30/29, the stock is modeled using:
- Revenue Growth (CAGR): 65.6%
- Operating Margins: 29.8%
- Exit P/E Multiple: 38.7x
Based on these inputs, the model estimates a $1,653 target price, implying 97.1% total upside from the current share price and a 27.5% annualized return over the next 2.8 years.
That annualized figure clears the 15% threshold the model treats as genuinely undervalued, even after this year’s run. Revenue growth above 65% is rare for a company of Lumentum’s size, and the market has not fully priced in how long that curve could last.

Margins are doing the heavy lifting too. An operating margin near 30% reflects real pricing power, not just volume growth, because Lumentum’s laser chips face limited competition at the highest speeds. That pricing power separates this story from a typical cyclical chip rally.
A 38.7x forward multiple still requires clean execution, since sentiment in this sector can swing fast. But relative to the growth management just guided to, the model suggests real room remains before the stock catches up to its own fundamentals.
Track Lumentum’s next earnings date and updated guidance (Free with TIKR) >>>
Lumentum Versus Coherent in the Optics Arms Race
Coherent (COHR) is Lumentum’s most direct rival in AI data center optics, and the two companies have taken different paths to the same demand surge. Coherent’s Q4 fiscal 2026 revenue reached roughly $2.05 billion, up about 34% year over year, while Lumentum’s smaller $1.01 billion in revenue grew far faster, up 109%.
Margins tell the more interesting story. Lumentum’s non-GAAP gross margin of 50.4% sits well above Coherent’s roughly 40.2%, because Lumentum concentrates on the highest-margin laser chips inside optical modules. Coherent instead builds the full module stack across a more diversified industrial mix.

Forward multiples reflect that split too, with Coherent trading near 43x and Lumentum closer to 38.7x on the model’s basis. Coherent has its own Nvidia relationship, including a separate $2 billion investment announced in March, so both companies are riding the same wave from different angles.
For investors, the choice comes down to risk tolerance. Lumentum offers cleaner AI exposure and higher margins, while Coherent offers broader diversification if hyperscaler spending ever slows.
What’s Driving LITE Stock Going Forward?
The next major catalyst is Q1 fiscal 2027 earnings, expected in early November. Investors will watch whether the guided 130% revenue growth actually materializes, since laser chip supply already runs tight.
Lumentum’s optical circuit switch backlog, which exceeded $400 million as of its last update, represents another growth lever beyond transceivers. As hyperscalers redesign networks for AI training clusters, Lumentum holds an early lead in that category.
The Nvidia partnership remains the central pillar of the bull case. Capacity access rights and expanded U.S. manufacturing tied to that deal should support Lumentum’s ability to keep scaling output, which is the main constraint on even faster growth.
Investors should also watch broader AI capex trends across hyperscalers, because Lumentum’s entire growth story depends on that spending continuing through 2027 and beyond.
Estimate a company’s fair value instantly (Free with TIKR) >>>
Should You Invest in Lumentum?
The only way to really know is to look at the numbers yourself. TIKR gives you free access to the same institutional-quality financial data that professional analysts use to answer exactly that question.
Pull up LITE, and you’ll see years of historical financials, what Wall Street analysts expect for revenue and earnings in the quarters ahead, how valuation multiples have moved over time, and whether price targets are trending up or down.
You can build a free watchlist to track LITE alongside every other stock on your radar. No credit card required. Just the data you need to decide for yourself.
Analyze LITE stock on TIKR Free→
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!