

Key Takeaways
- Penalty-Driven EBIT Loss: A RMB5.18B onetime penalty pushed Q2 EBIT to a RMB1.46B loss, a 138% miss vs. the RMB3.82B Street estimate, even as adjusted EPS of RMB7.27 beat Street by 27%.
- International Growth Accelerates: Trip.com’s international OTA revenue grew over 50% YoY in Q2, while first and business class bookings rose over 70% YoY in H1 2026.
- Inbound Travel Ambition: Management targets 200M inbound travelers within five years.
- CFO Calls Charge Onetime: CFO Cindy Wang said the RMB5.18B expense and RMB122M contra-revenue “do not reflect the underlying performance of our business in the second quarter.”
Trip.com’s Q2 Earnings Show a GAAP Loss That Masks a Real Beat Underneath
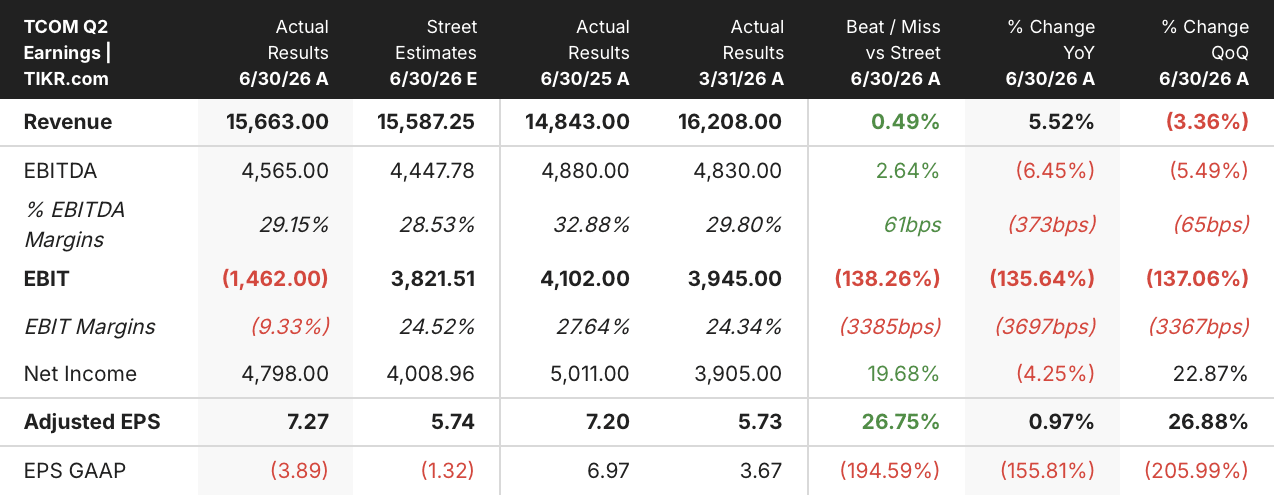
Trip.com Group Limited (TCOM) posted second quarter 2026 revenue of RMB15.66 billion on September 15, up 5.5% from a year earlier and 0.5% ahead of the RMB15.59 billion Street estimate. Beneath that modest top-line beat sat a far sharper swing: EBIT flipped to a RMB1.46 billion loss, a 138% miss against the RMB3.82 billion analysts had modeled, driven by a one-time regulatory penalty.
That penalty traces to the administrative decision Trip.com received in July from China’s State Administration for Market Regulation. It ran RMB5.18 billion through expenses and another RMB122 million through contra-revenue in the quarter alone. EBIT margin collapsed to negative 9.33% from 27.64% a year earlier, a 3,697 basis point swing that looks disastrous read on its own. Strip the charge out, though, and the picture flips: adjusted net income of RMB4.80 billion beat the RMB4.01 billion Street estimate by 20%, and adjusted EPS of RMB7.27 cleared the RMB5.74 estimate by 27%.
CFO Cindy Wang addressed the disconnect directly on the Q2 earnings call: “From an accounting perspective, we recognized expenses of RMB 5.18 billion and contra-revenue of RMB 122 million in the second quarter. These are onetime items and do not reflect the underlying performance of our business in the second quarter.” She also flagged near-term volatility as partners adjust to the new multitiered distribution framework replacing the discontinued Tier 1 and Tier 2 programs.
Outside the penalty, the business kept accelerating. Trip.com’s international OTA platform grew revenue more than 50% year over year, and first and business class bookings climbed over 70% in the first half of 2026 alone. Inbound travel posted high double digit growth, with management targeting 200 million inbound travelers over the next five years. TripGenie, the company’s AI assistant, saw order volume rise 400% year over year, and 60% of those interactions are now booking related.
The mix tells the real story. A domestic distribution model under regulatory rework is giving way to a faster-growing, higher-margin international and AI-driven business, and this quarter’s GAAP loss traces to a settlement, not to slowing demand.
TIKR Values TCOM Stock at $68, Pricing In an International-Led Rebound
TIKR’s mid-case model values Trip.com Group at $68 by December 2030, implying 74% total return from the current price of $39, or 14% annualized over 4.3 years.
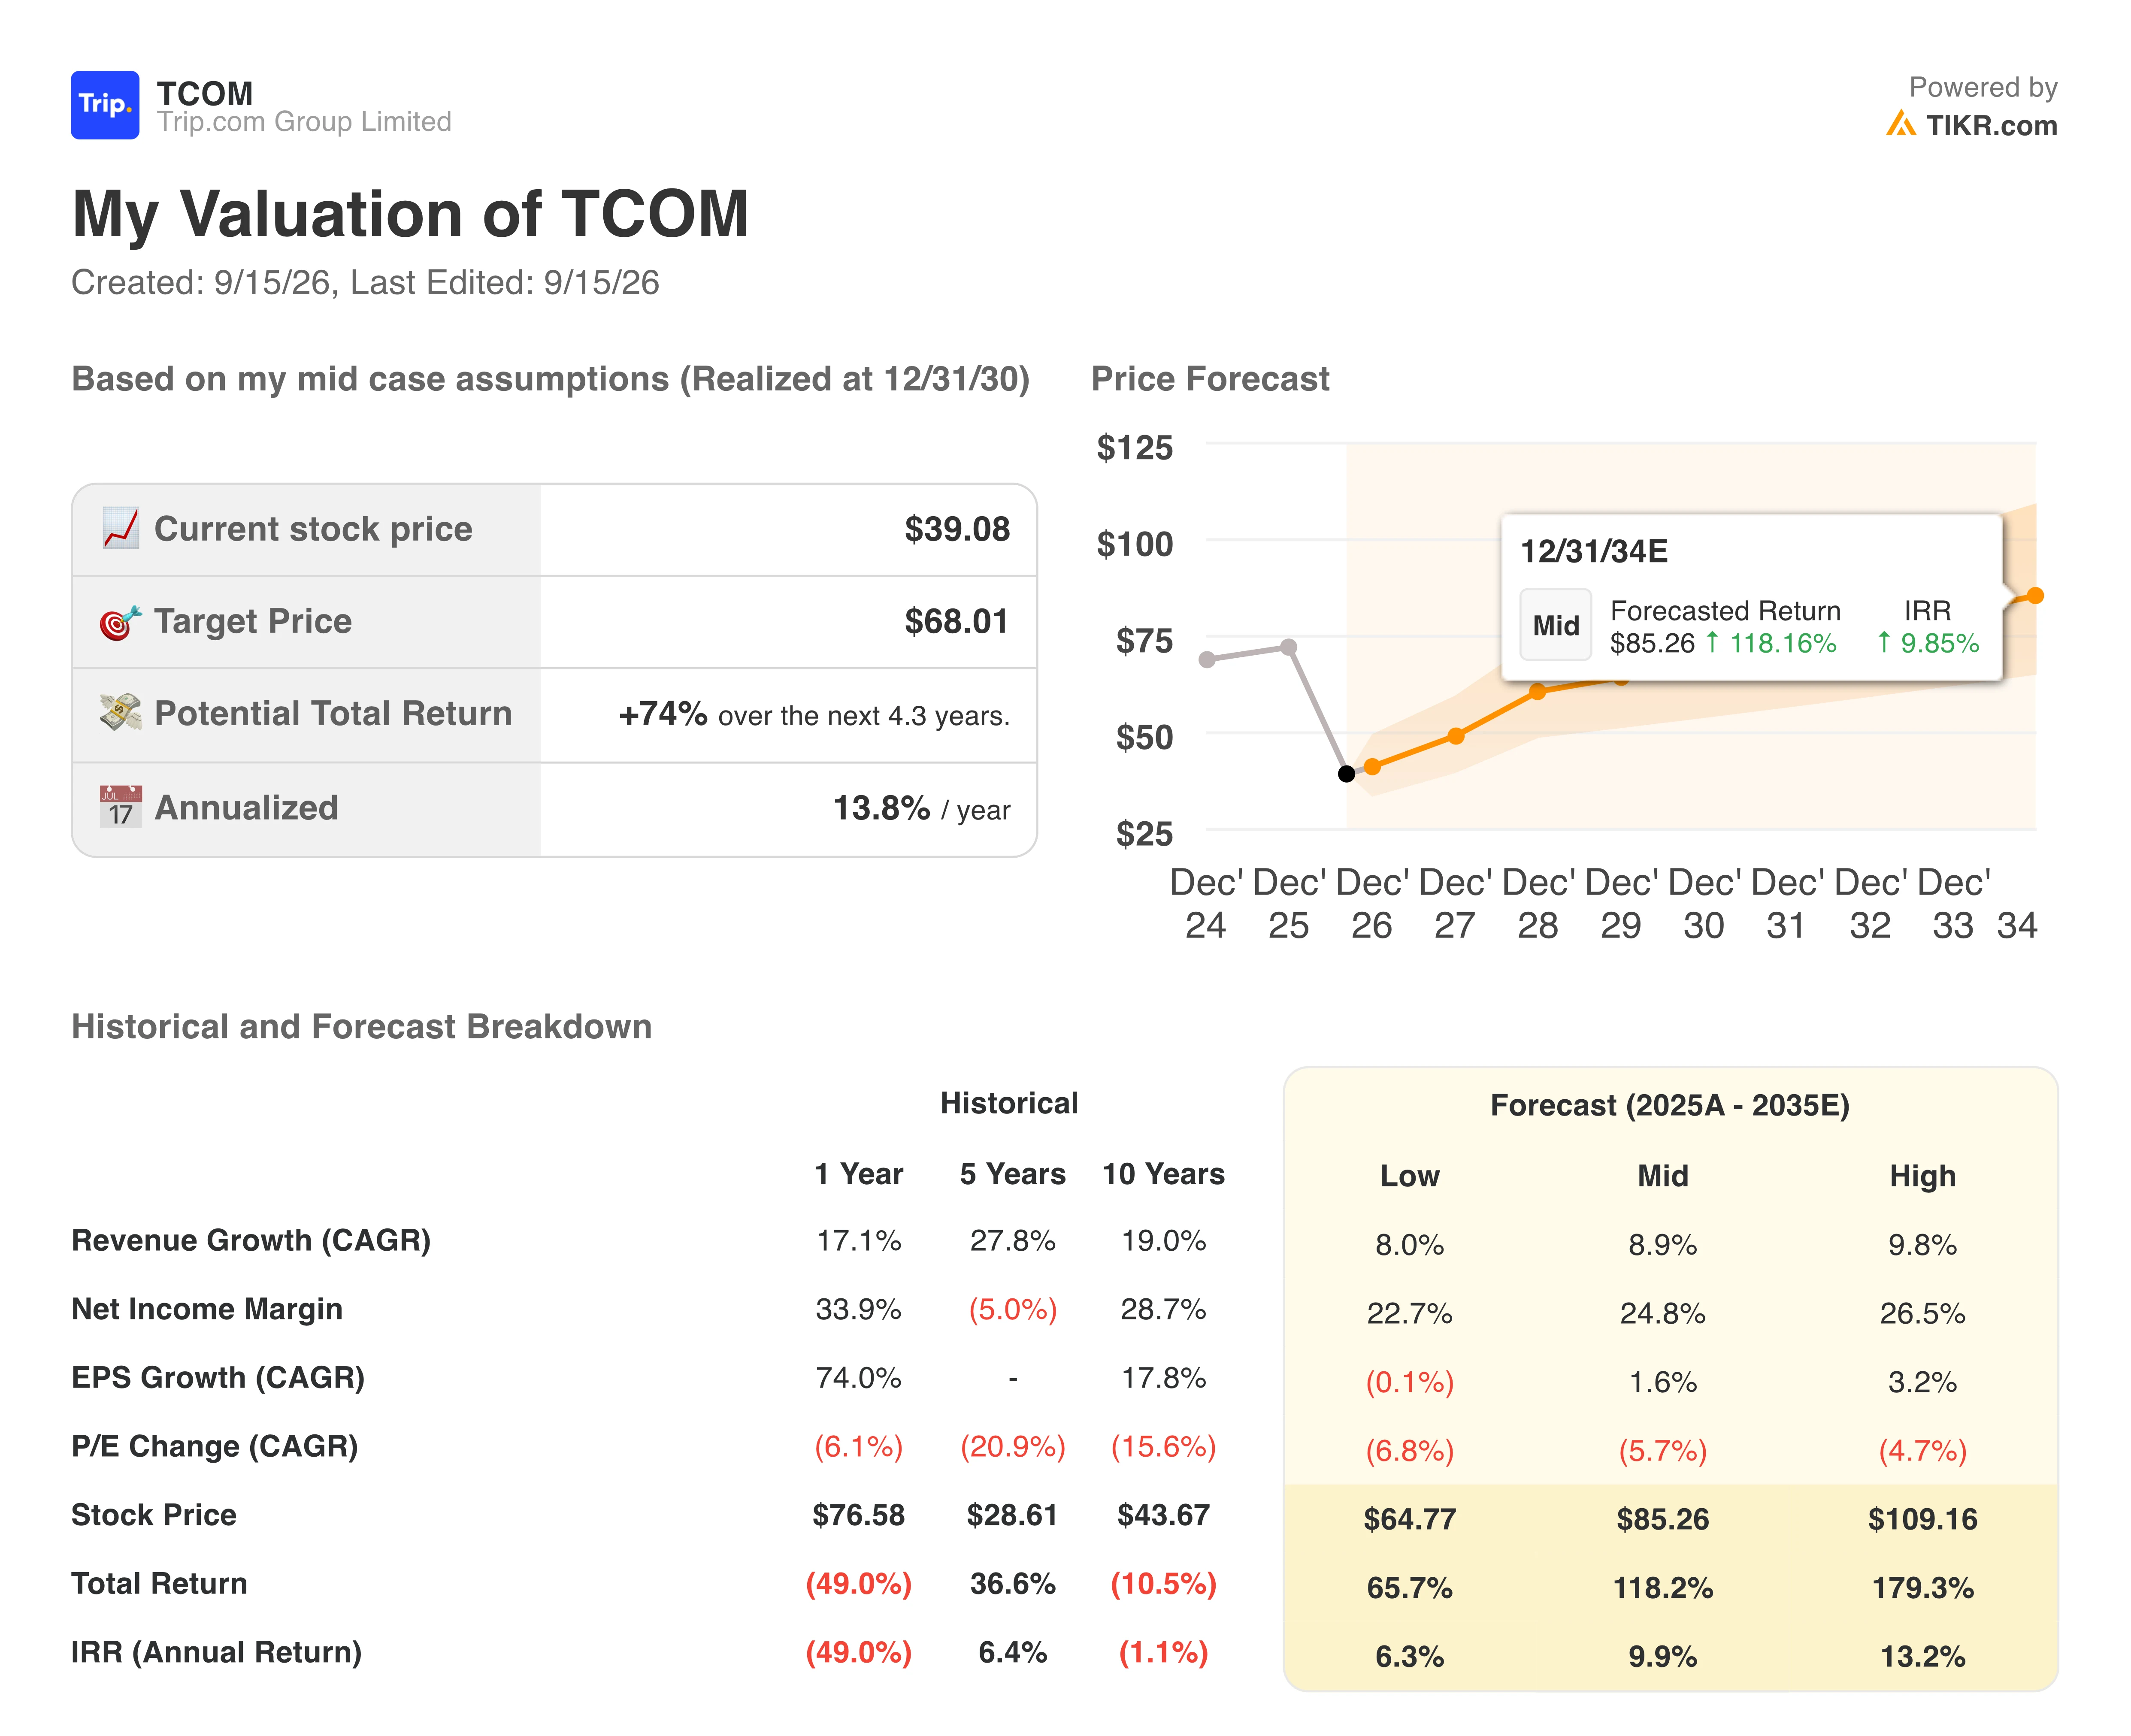
That gap between a $39 stock and a $68 target signals the market is still pricing Trip.com’s regulatory headline well ahead of its structural growth story.
The case rests on the international engine already running well ahead of the core business: an OTA platform growing more than 50% a year gives the group a second growth line running independent of the domestic distribution rework still working through the system. As that mix shift continues and the SAMR charge rolls off the year-over-year comparison, the earnings power the adjusted print already showed becomes harder for the market to ignore.
Should You Invest in Trip.com Group Limited?
The only way to really know is to look at the numbers yourself. TIKR gives you free access to the same institutional-quality financial data that professional analysts use to answer exactly that question.
Pull up Trip.com Group Limited stock and you’ll see years of historical financials, what Wall Street analysts expect for revenue and earnings in the quarters ahead, how valuation multiples have moved over time, and whether price targets are trending up or down.
You can build a free watchlist to track Trip.com Group Limited alongside every other stock on your radar. No credit card required. Just the data you need to decide for yourself.
Access Professional Tools to Analyze TCOM stock on TIKR for Free →
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!


