Key Takeaways
- Post-Earnings Reversal: Altria’s Q2 adjusted EPS of $1.48 missed consensus by two cents and sent shares down as much as 9% to $68, their worst single day since June 2022, even as management raised the low end of full-year guidance to $5.61 to $5.72 per share and the board lifted the quarterly dividend to $1.11 within a month.
- Coverage Confirmed: The payout ratio eased to 77% in the quarter ended June 30, 2026 from 81.54% the prior quarter, and free cash flow of $660 million was nearly four times the $170 million generated in the same quarter a year earlier.
- Regulatory Wildcard: Altria sued the FDA on September 2 to force an overhaul of the tobacco product review system, targeting the same review backlog that has slowed the oral tobacco segment, whose adjusted operating income fell 8% in Q2 on on! PLUS launch spending.
- Consensus Already There: The Street’s mean price target sat at $70.00 against a $69.81 close on September 15, just 0.3% apart, with Barclays’ $58 target the lone outlier dragging down the low end of the range.
Altria Stock’s Selloff Didn’t Match What Came Next
Altria’s (MO) second quarter looked like a disappointment. Adjusted diluted earnings per share rose 2.8% year over year to $1.48, short of the $1.50 analysts expected, and the stock fell as much as 9.1% to $68.08 on July 30, its steepest single-day drop since June 2022. Management pointed to value-pressured smokers trading down and a tough prior-year oral tobacco comparison.
What followed complicates the simple “miss and fade” reading. On the same Q2 2026 earnings call, CFO Heather Newman raised the low end of full-year adjusted EPS guidance to a $5.61 to $5.72 range, citing four consecutive quarters of moderating cigarette industry decline. Then, within a month, the board lifted the quarterly dividend to $1.11 per share, director Kathryn McQuade bought $101,430 of stock in the open market, and Altria added Refresco chief executive Steven Presley, a packaged-goods veteran, to its board.
On September 2, the company sued the FDA outright, seeking to force a faster, more predictable review process for its smoke-free pipeline. None of that reads like a management team bracing for a weaker business.
Testing Altria’s Dividend Raise Against Its Cash Flow
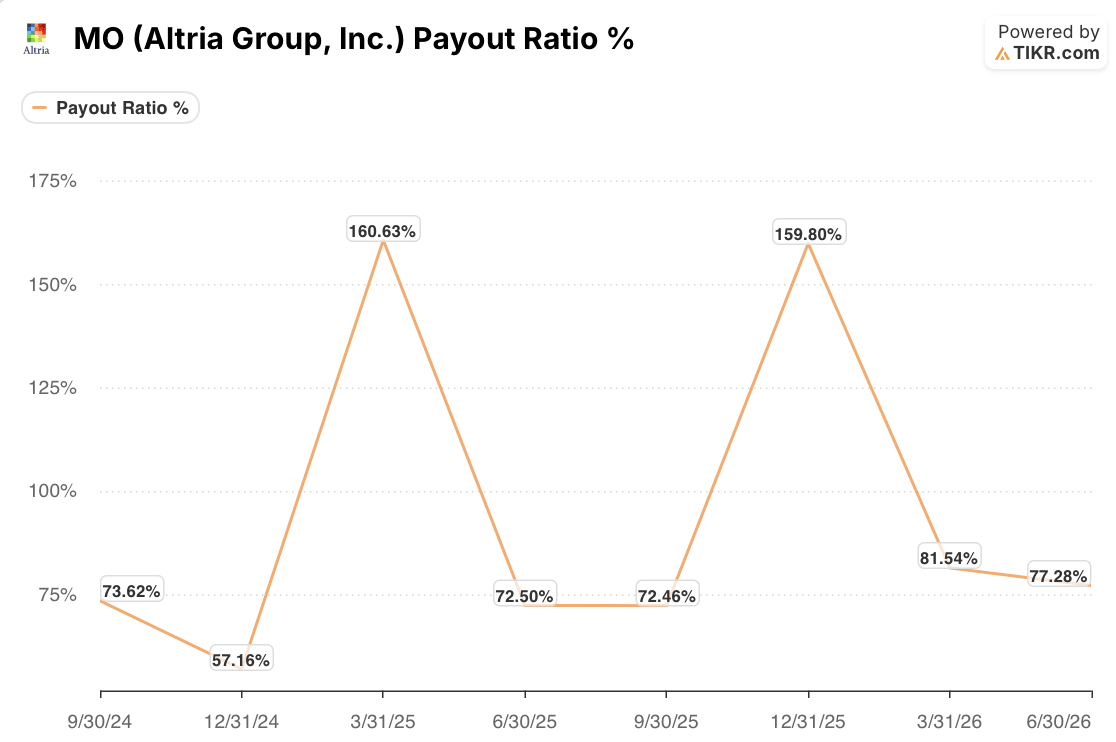
A dividend increase from a company whose stock just dropped 9% is only a genuine signal if the payout is actually funded.
Altria’s payout ratio has spiked above 150% twice in the past two years, in quarters that look like one-time GAAP distortions rather than the operating trend. Set those two quarters aside and the ratio ran 72.50%, 72.46%, 81.54%, and 77.28% across the four most recent ordinary quarters, a modest step up over the year that eased in the most recent quarter, the same one in which the dividend went up.
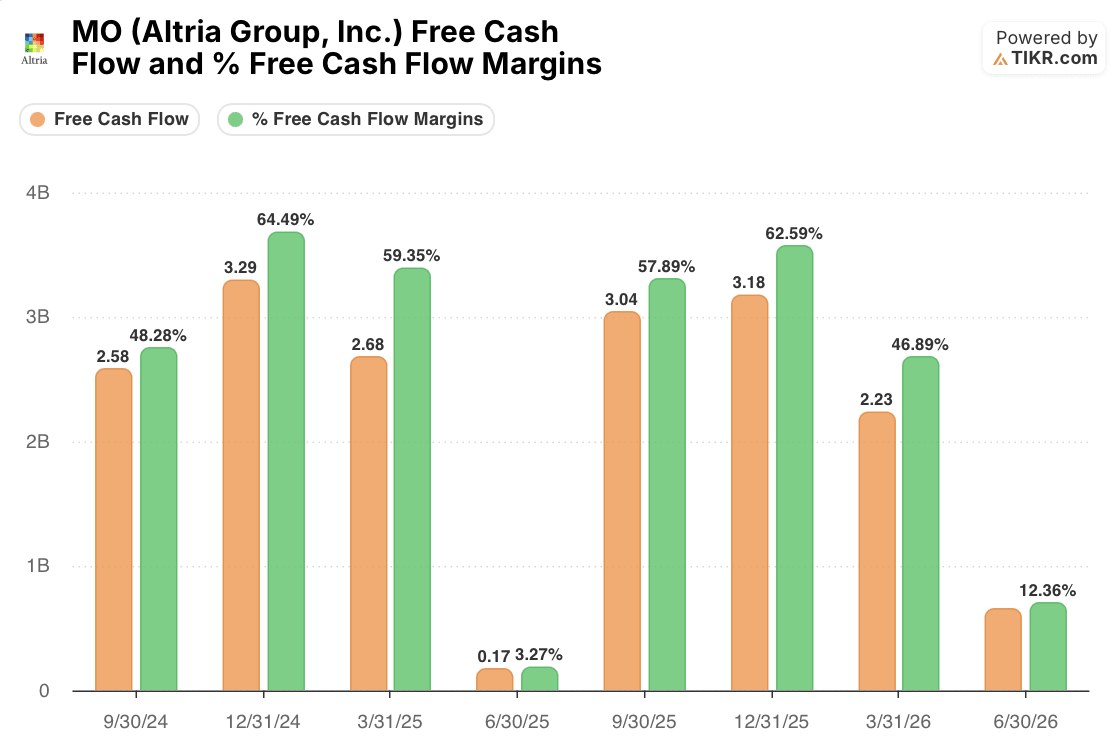
Free cash flow backs that up. The quarter ended June 30, 2026 generated $660 million in free cash flow at a 12.36% margin, versus just $170 million and a 3.27% margin in the same quarter a year earlier, a roughly fourfold improvement in what has consistently been Altria’s weakest seasonal cash-flow quarter.
Summing the four quarters supplied (September 2025 through June 2026) puts trailing twelve-month free cash flow at approximately $9.1 billion, comfortably above the roughly $7.2 billion annualized pace implied by the $3.6 billion Altria paid in dividends during the first half of 2026, a run rate that only goes higher now that the quarterly payment has stepped up to $1.11. A 1.9 times net debt to EBITDA ratio, in line with management’s own 2 times target, adds further room. The dividend raise looks paid for, not aspirational.
The FDA Lawsuit Targets Exactly What’s Been Dragging on Oral Tobacco
The dividend’s durability answers whether Altria can keep paying. It doesn’t answer whether the business can grow, and that question runs through the FDA litigation. Oral tobacco segment adjusted operating income fell 8% in the second quarter and 4.2% in the first half, a decline management attributes to on! PLUS launch spending and a tough 2025 comparison tied to a competitor’s supply disruption. Segment margins held at a still-healthy 66.7%, and retail share was stable at 29%, but the investment phase is real.
That is the backdrop against which Altria filed suit. The complaint argues the FDA has never met its own 180-day statutory deadline for reviewing new tobacco products, a backlog the company says has buried products like on! in regulatory delay while unauthorized competitors gain share.
A faster process would matter to Altria’s near-term plans: a national rollout of 12-milligram on! PLUS in the third quarter, two flavor extensions due in the fourth quarter, and a planned re-entry for NJOY ACE now that the patent dispute that pulled it from shelves has been resolved. None of that requires the lawsuit to succeed, but a favorable outcome would remove a real constraint on scaling the products meant to offset cigarette volumes, still down an estimated 5% industry-wide even as the decline moderates.
The Dividend Looks Funded. The Upside Case Still Needs the FDA to Move.
Put together, the insider buying, dividend increase, and board addition read like a management team that looked at its own cash flow and concluded the selloff overstated the risk. The numbers largely support that: coverage is improving, not deteriorating, and the balance sheet has room to spare.
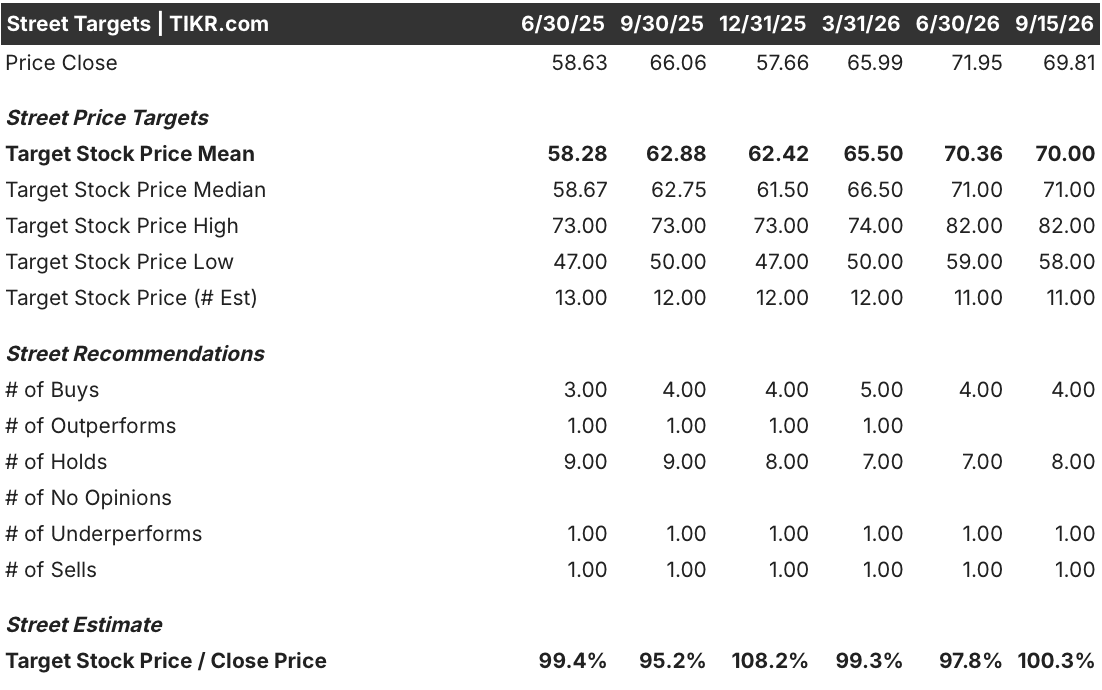
What the numbers don’t support is a mispricing story. The Street’s mean price target sat at $70.00 against Altria’s $69.81 close on September 15, essentially identical, and the median target of $71.00 implies barely more upside. Of the ratings TIKR tracks, four are buys, eight are holds, and two are more bearish, with Barclays’ $58 cut from late July still anchoring the low end of the $58 to $82 range rather than reflecting a broader bearish shift. Analysts, in other words, have already caught up to the recovery from July’s low; this isn’t a case of insiders seeing value the Street has missed.
The more honest framing is that the confidence signals check out as confirmation, not discovery. The dividend is backed by real cash generation, lowering the risk of a cut that would pressure the multiple. The open question is whether the FDA litigation and the on! PLUS pipeline convert into an oral tobacco margin recovery fast enough to offset cigarette volume erosion.
The next data point worth watching is the third-quarter oral tobacco segment’s adjusted operating income trend, which will show whether the launch-spending pressure behind the 8% decline is easing as the 12-milligram rollout scales nationally.
Should You Invest in Altria Group, Inc.?
The only way to really know is to look at the numbers yourself. TIKR gives you free access to the same institutional-quality financial data that professional analysts use to answer exactly that question.
Pull up Altria Group, Inc. stock and you’ll see years of historical financials, what Wall Street analysts expect for revenue and earnings in the quarters ahead, how valuation multiples have moved over time, and whether price targets are trending up or down.
You can build a free watchlist to track Altria Group, Inc. alongside every other stock on your radar. No credit card required. Just the data you need to decide for yourself.
Access Professional Tools to Analyze MO stock on TIKR for Free →
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!