Key Stats for EQT Stock
- Past week performance: -5%
- 52-week range: $48 to $68
- Valuation model target price: $77
- Implied upside: 45.8% over 2.3 years
Rank EQT’s margins against the rest of the gas sector using TIKR’s Guided Valuation Model (It’s free) >>>
Gas Prices Wobbled, But Expansion Plans Kept Moving
EQT (EQT) fell roughly 5% this week, closing near $50, as natural gas prices stayed under pressure amid ample storage and steady Appalachian output. The pullback came even as EQT kept executing on plans to reclaim its spot as America’s largest natural gas producer.
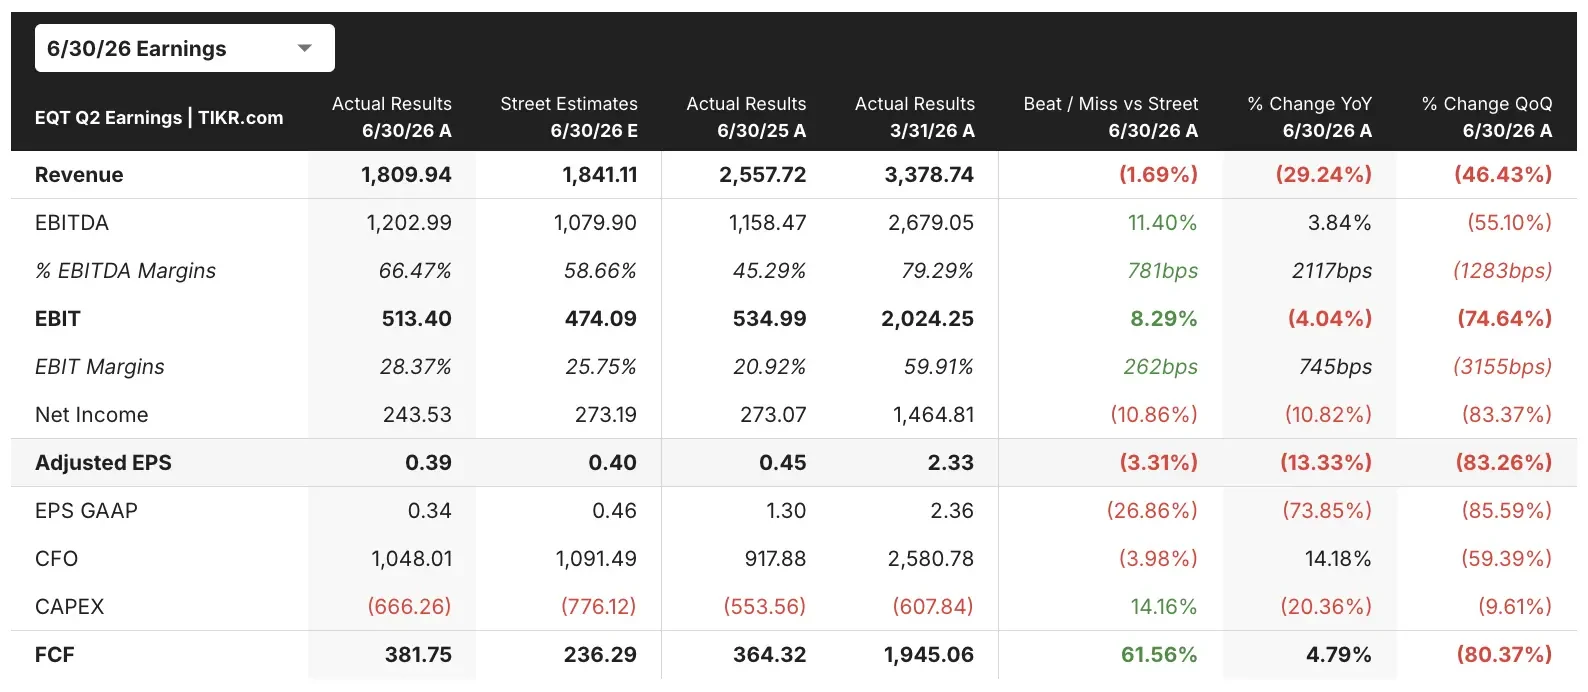
That backdrop follows a mixed Q2 report in July, when EQT missed adjusted EPS estimates at $0.39 per share on weaker realized gas prices. But management used the same report to raise full-year 2026 sales volume guidance to 2,375 to 2,450 billion cubic feet equivalent, while trimming capital spending guidance by $25 million.
Two developments this quarter reinforce EQT’s longer-term case. In August, power developer CPV secured a 10-year gas netback agreement with EQT to supply the 2,100-megawatt Shay Energy Center, locking in demand tied to gas-fired power for data centers. And EQT’s planned MVP Boost project, a 500-million-cubic-foot expansion of the Mountain Valley Pipeline, remains on track after the related MVP Southgate expansion received FERC approval in June.
Management has framed these moves as central to retaking the top production spot from rival Expand Energy. Executives noted on recent calls that EQT’s cost structure and pipeline access give it flexibility peers cannot easily match. If EQT stock keeps executing on this timeline, the current gas price weakness may prove temporary.
Stack EQT up against Expand Energy and Range Resources (It’s free) >>>
Is EQT Stock Undervalued After This Pullback?
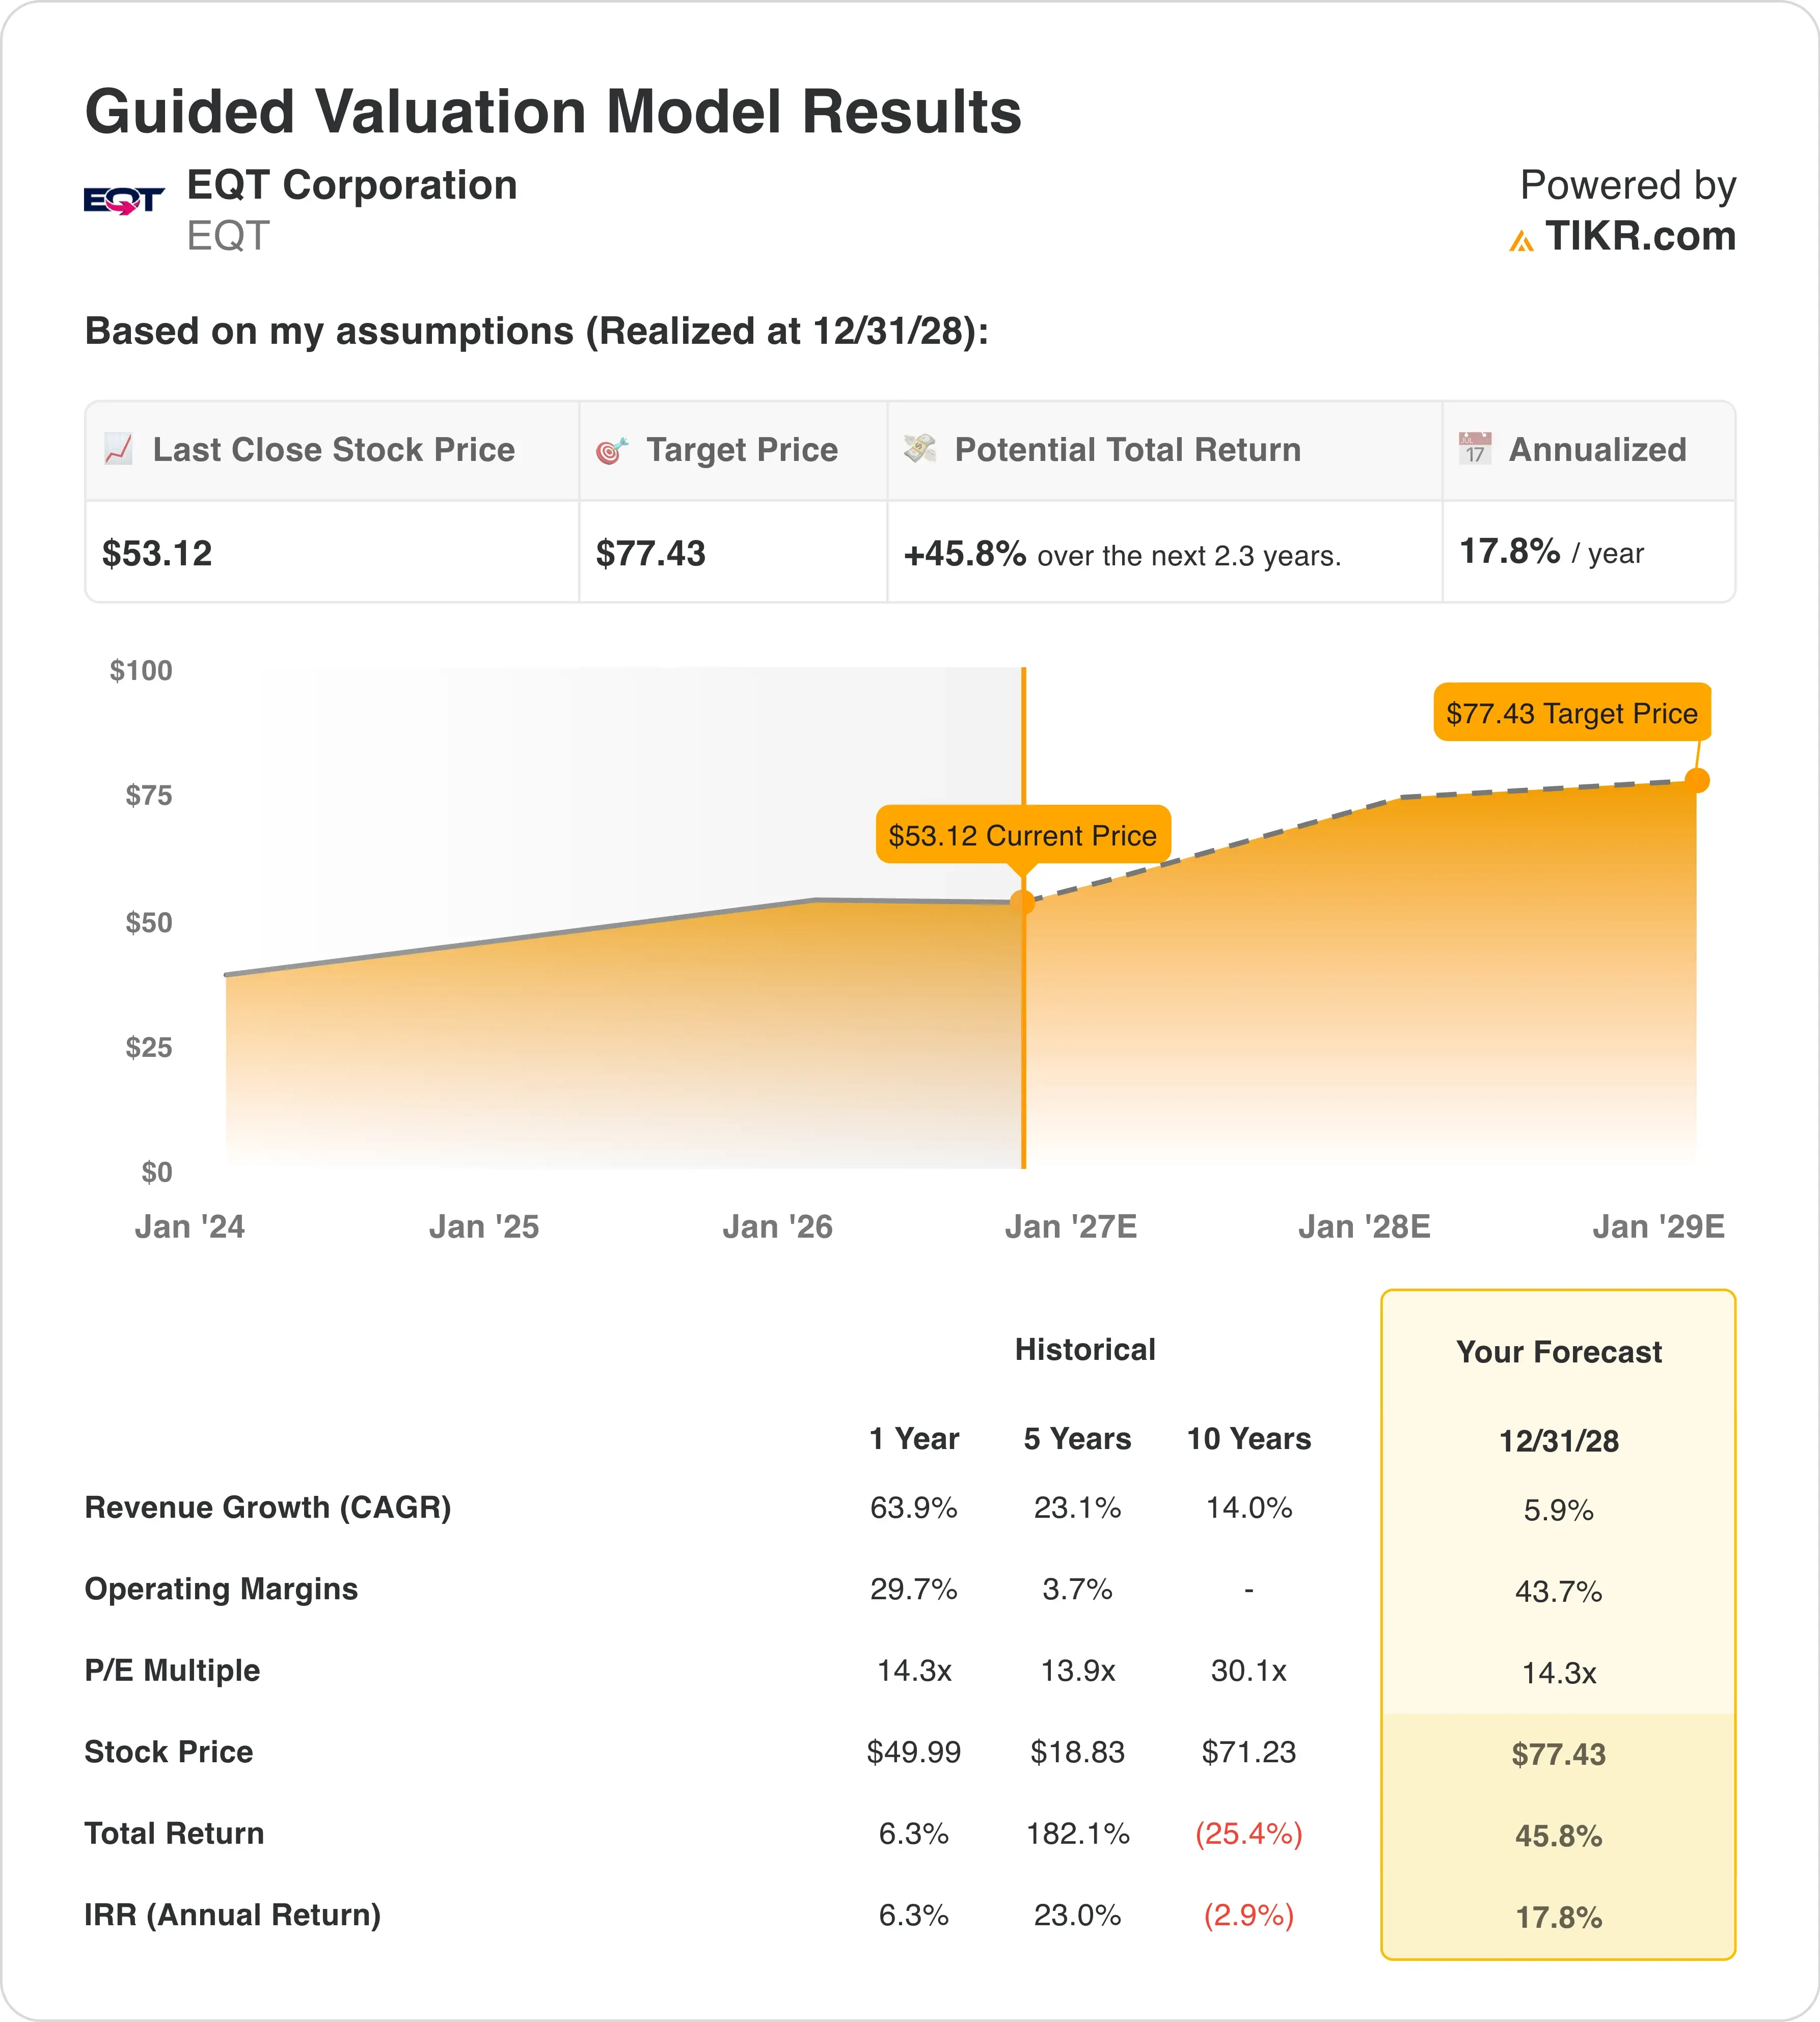
Under valuation model assumptions realized through 12/31/28, the stock is modeled using:
- Revenue Growth (CAGR): 5.9%
- Operating Margins: 43.7%
- Exit P/E Multiple: 14.3x
Based on these inputs, the model estimates a $77 target price, implying 45.8% total upside from the current share price and a 17.8% annualized return over the next 2.3 years.
That annualized return clears the 15% threshold the model treats as genuinely undervalued. It stands out because EQT achieves it without aggressive revenue growth assumptions. Revenue growth of just 5.9% reflects a company prioritizing free cash flow and shareholder returns over volume for its own sake.
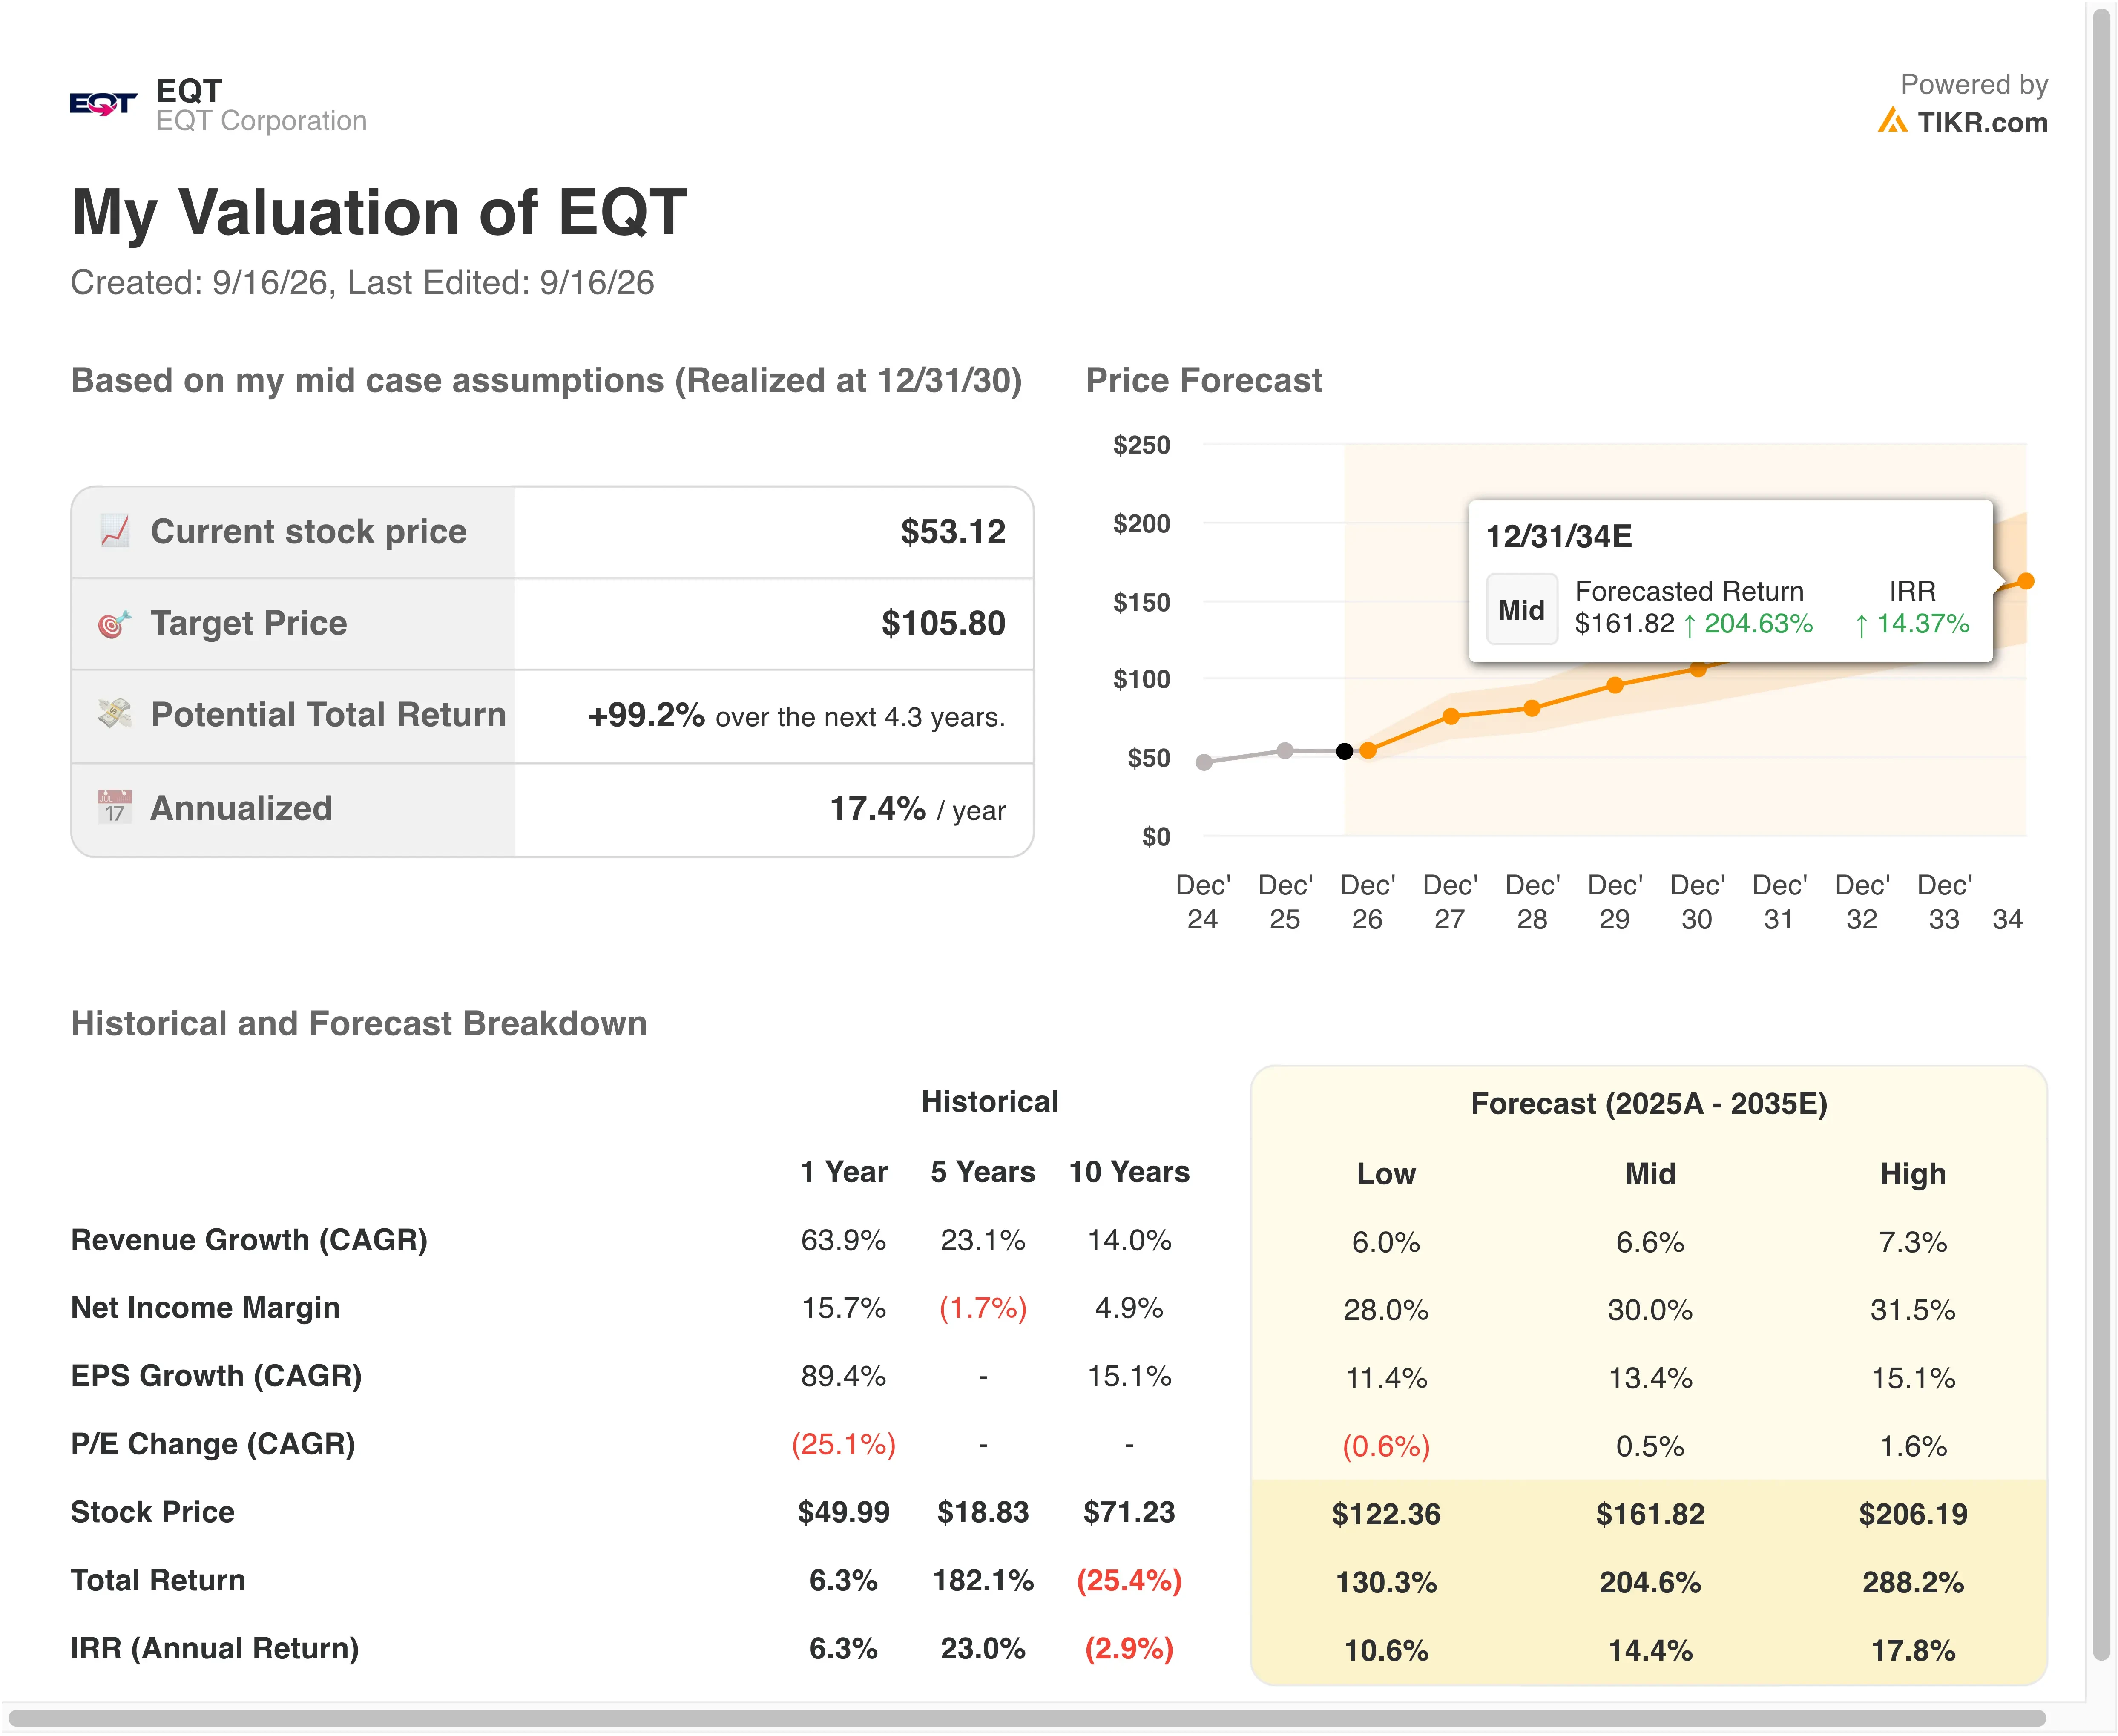
Margins are where EQT’s advantage really shows. An operating margin near 44% is exceptional for an exploration and production company, and it reflects the scale EQT has built across its Marcellus Shale position. That efficiency lets the stock generate strong annualized returns even at a conservative 14.3x exit multiple.
The current pullback, driven by soft gas prices rather than any company-specific problem, has widened the gap between EQT’s share price and the model’s target. For investors willing to look past short-term commodity swings, that gap is exactly what the model is designed to flag.
Estimate a company’s fair value instantly (Free with TIKR) >>>
EQT Against Expand Energy and Range Resources
Expand Energy (EXE) currently holds the title EQT is chasing, as the largest U.S. natural gas producer by volume following its 2024 merger of Chesapeake Energy and Southwestern Energy. Expand guided 2026 production to roughly 7.4 to 7.6 billion cubic feet equivalent per day on capital spending of $2.75 billion to $2.95 billion.
But EQT’s MVP Boost expansion, adding up to 2.5 billion cubic feet per day of new capacity, could put it well ahead of Expand if the larger rival does not keep pace. EQT also holds a clear efficiency edge, with one recent analysis putting its EBITDA margin near 78%, a level peers including Range Resources and Antero Resources (AR) have not matched.
Range Resources (RRC) competes on a smaller scale, guiding annual capital spending of $650 million to $700 million between 2025 and 2027 to grow daily production from about 2.4 to 2.6 billion cubic feet equivalent. Range’s measured approach mirrors EQT’s own capital discipline, though EQT’s larger reserve base of roughly 25 trillion cubic feet gives it more runway.
The competitive dynamic comes down to who can convert pipeline capacity into production fastest. EQT’s combination of low breakeven costs and expanding takeaway capacity positions it well in that race.
Watch buybacks, contracted demand, and production growth >>>
What’s Driving EQT Stock Going Forward?
The MVP Boost project remains the single biggest catalyst ahead. Successfully bringing that 500-million-cubic-foot expansion online would materially close the production gap with Expand Energy and support the volume growth built into the model.
Q3 earnings, expected around October 20, will show whether the raised full-year volume guidance is tracking as planned. They will also show whether realized gas prices have stabilized enough to support current margin assumptions.
Data center power demand is becoming an increasingly important driver for EQT specifically, as the CPV netback agreement demonstrates. More deals of that kind could reduce EQT’s exposure to volatile spot gas prices over time.
Investors should also watch storage and weather trends heading into winter, since colder-than-expected conditions could quickly reverse the soft pricing that pressured the stock this week.
Run your own EQT production growth scenario (Free with TIKR) >>>
Should You Invest in EQT?
The only way to really know is to look at the numbers yourself. TIKR gives you free access to the same institutional-quality financial data that professional analysts use to answer exactly that question.
Pull up EQT, and you’ll see years of historical financials, what Wall Street analysts expect for revenue and earnings in the quarters ahead, how valuation multiples have moved over time, and whether price targets are trending up or down.
You can build a free watchlist to track EQT alongside every other stock on your radar. No credit card required. Just the data you need to decide for yourself.
Analyze EQT stock on TIKR Free→
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!