Key Takeaways
- SoFi stock rose 11% in the past week (through Tuesday’s close) after third-quarter revenue rose 44% to $1.39 billion, well ahead of estimates.
- SoFi’s 2027 outlook of $0.90 of EPS, 48% above its raised 2026 guide, looks achievable and should pull analysts’ estimates higher.
- SoFi traded at 2.0x tangible book the day before the report, well below its 2.7x five-year average.
- Rates are the main risk to the personal loans SoFi holds on its own books. The Fed’s decision on Oct. 28 is the next test.
SoFi Technologies (SOFI) stock is up 11% in the past week (through Tuesday’s close). All of it came Tuesday, when shares jumped 13% after third-quarter results landed before the open.
The stock hit a 52-week low in mid-October and is still down 40% in 2026. So the question going in was whether SoFi could hold its 2026 guide.
It did, and then some.
SoFi delivered the quarter its guide needed
To reach the roughly $0.60 it guided to for 2026, SoFi needed about $0.18 of adjusted EPS a quarter in the second half. It earned exactly that:
- Revenue of $1.39 billion, up 44% and about 10% above the $1.26 billion consensus
- Adjusted EPS of $0.18, a penny ahead of estimates
- Fee-based revenue of $570.6 million, 42% of the total and up 21% from the second quarter
SoFi raised its 2026 guide to $5.04 billion of adjusted net revenue and $0.61 of EPS. As CEO Anthony Noto pointed out on X, “Our original 2026 guidance assumed two rate cuts.” SoFi got a hike instead.
Analysts’ 2027 numbers look too low
Then SoFi gave its 2027 outlook: about $6.4 billion of adjusted net revenue and $0.90 of EPS. That’s 48% more than this year’s guide, and well above what analysts expected for 2027 going in…
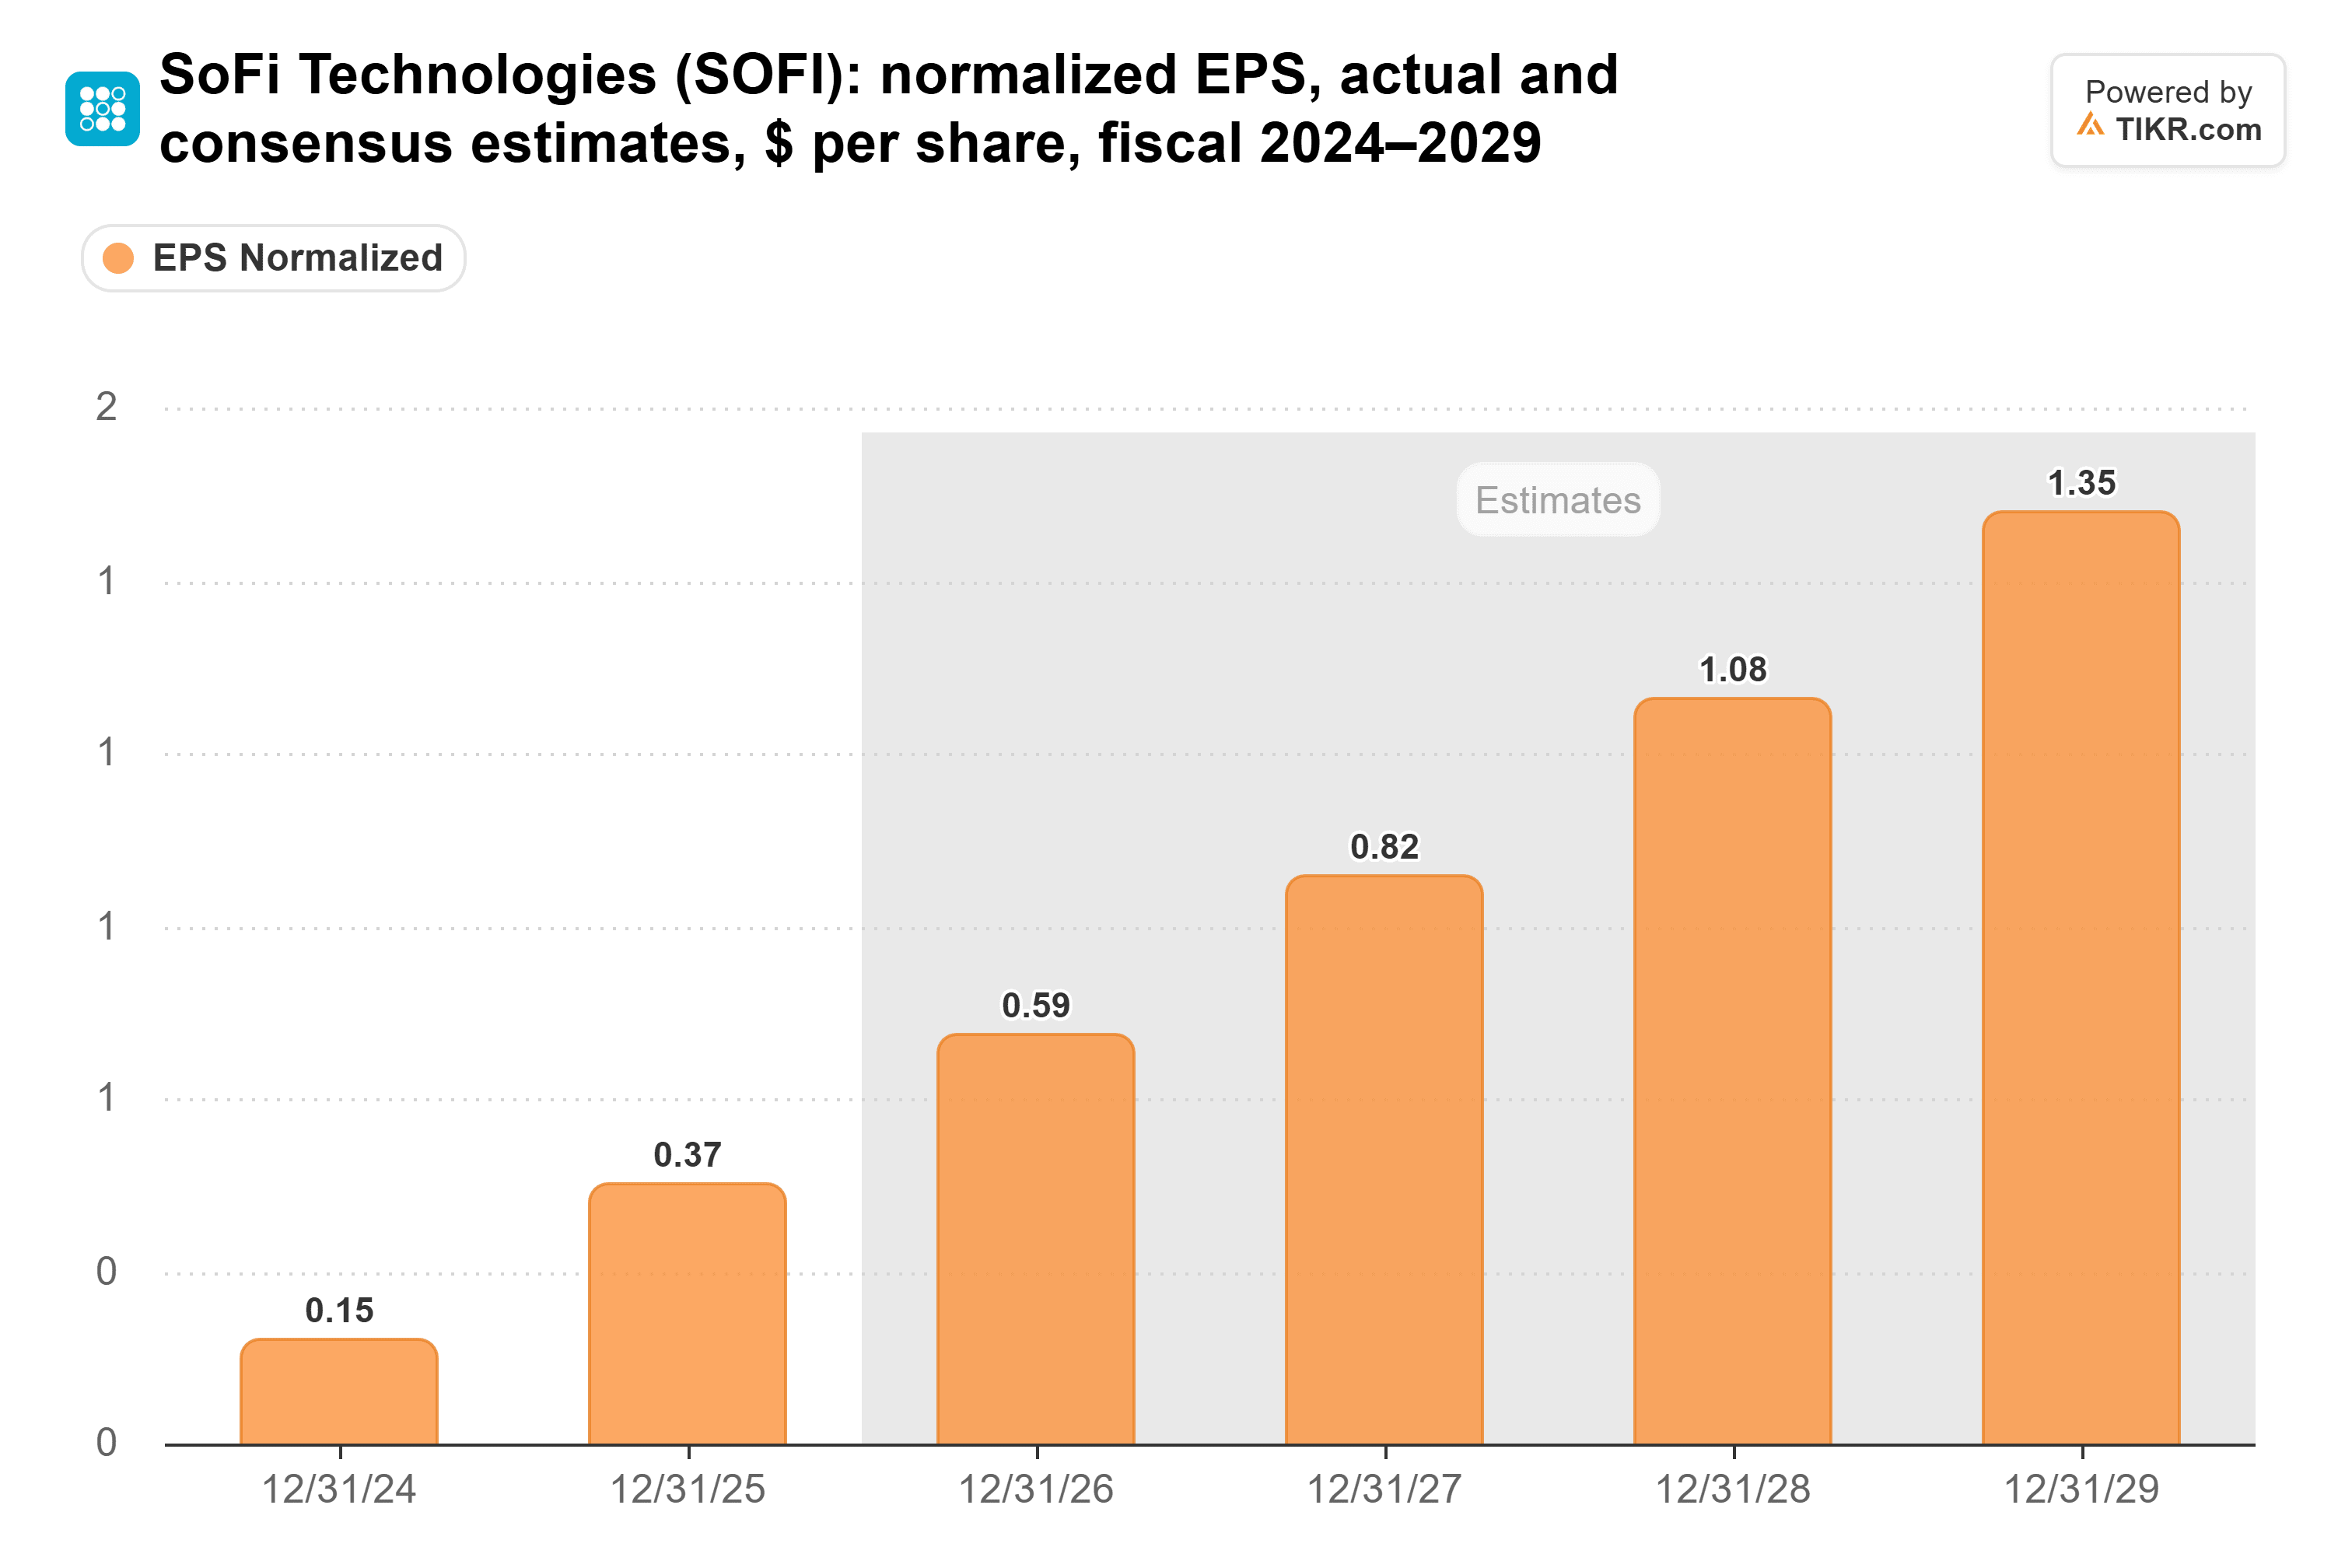
The $0.82 consensus should move up. SoFi met or beat every 2025 target it set last October, and it raised this year’s guide even though rates went against it.
The outlook calls for 27% revenue growth and a 20% net margin. Those are right in line with what TIKR’s valuation model assumed when it put SoFi at about $22 by December 2028.
TIKR tracks 25 analysts on SoFi. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on SoFi, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See SoFi’s Analyst Ratings
Still cheap on its own numbers
The day before the report, SoFi traded at 2.0x tangible book, against a 2.7x five-year average…
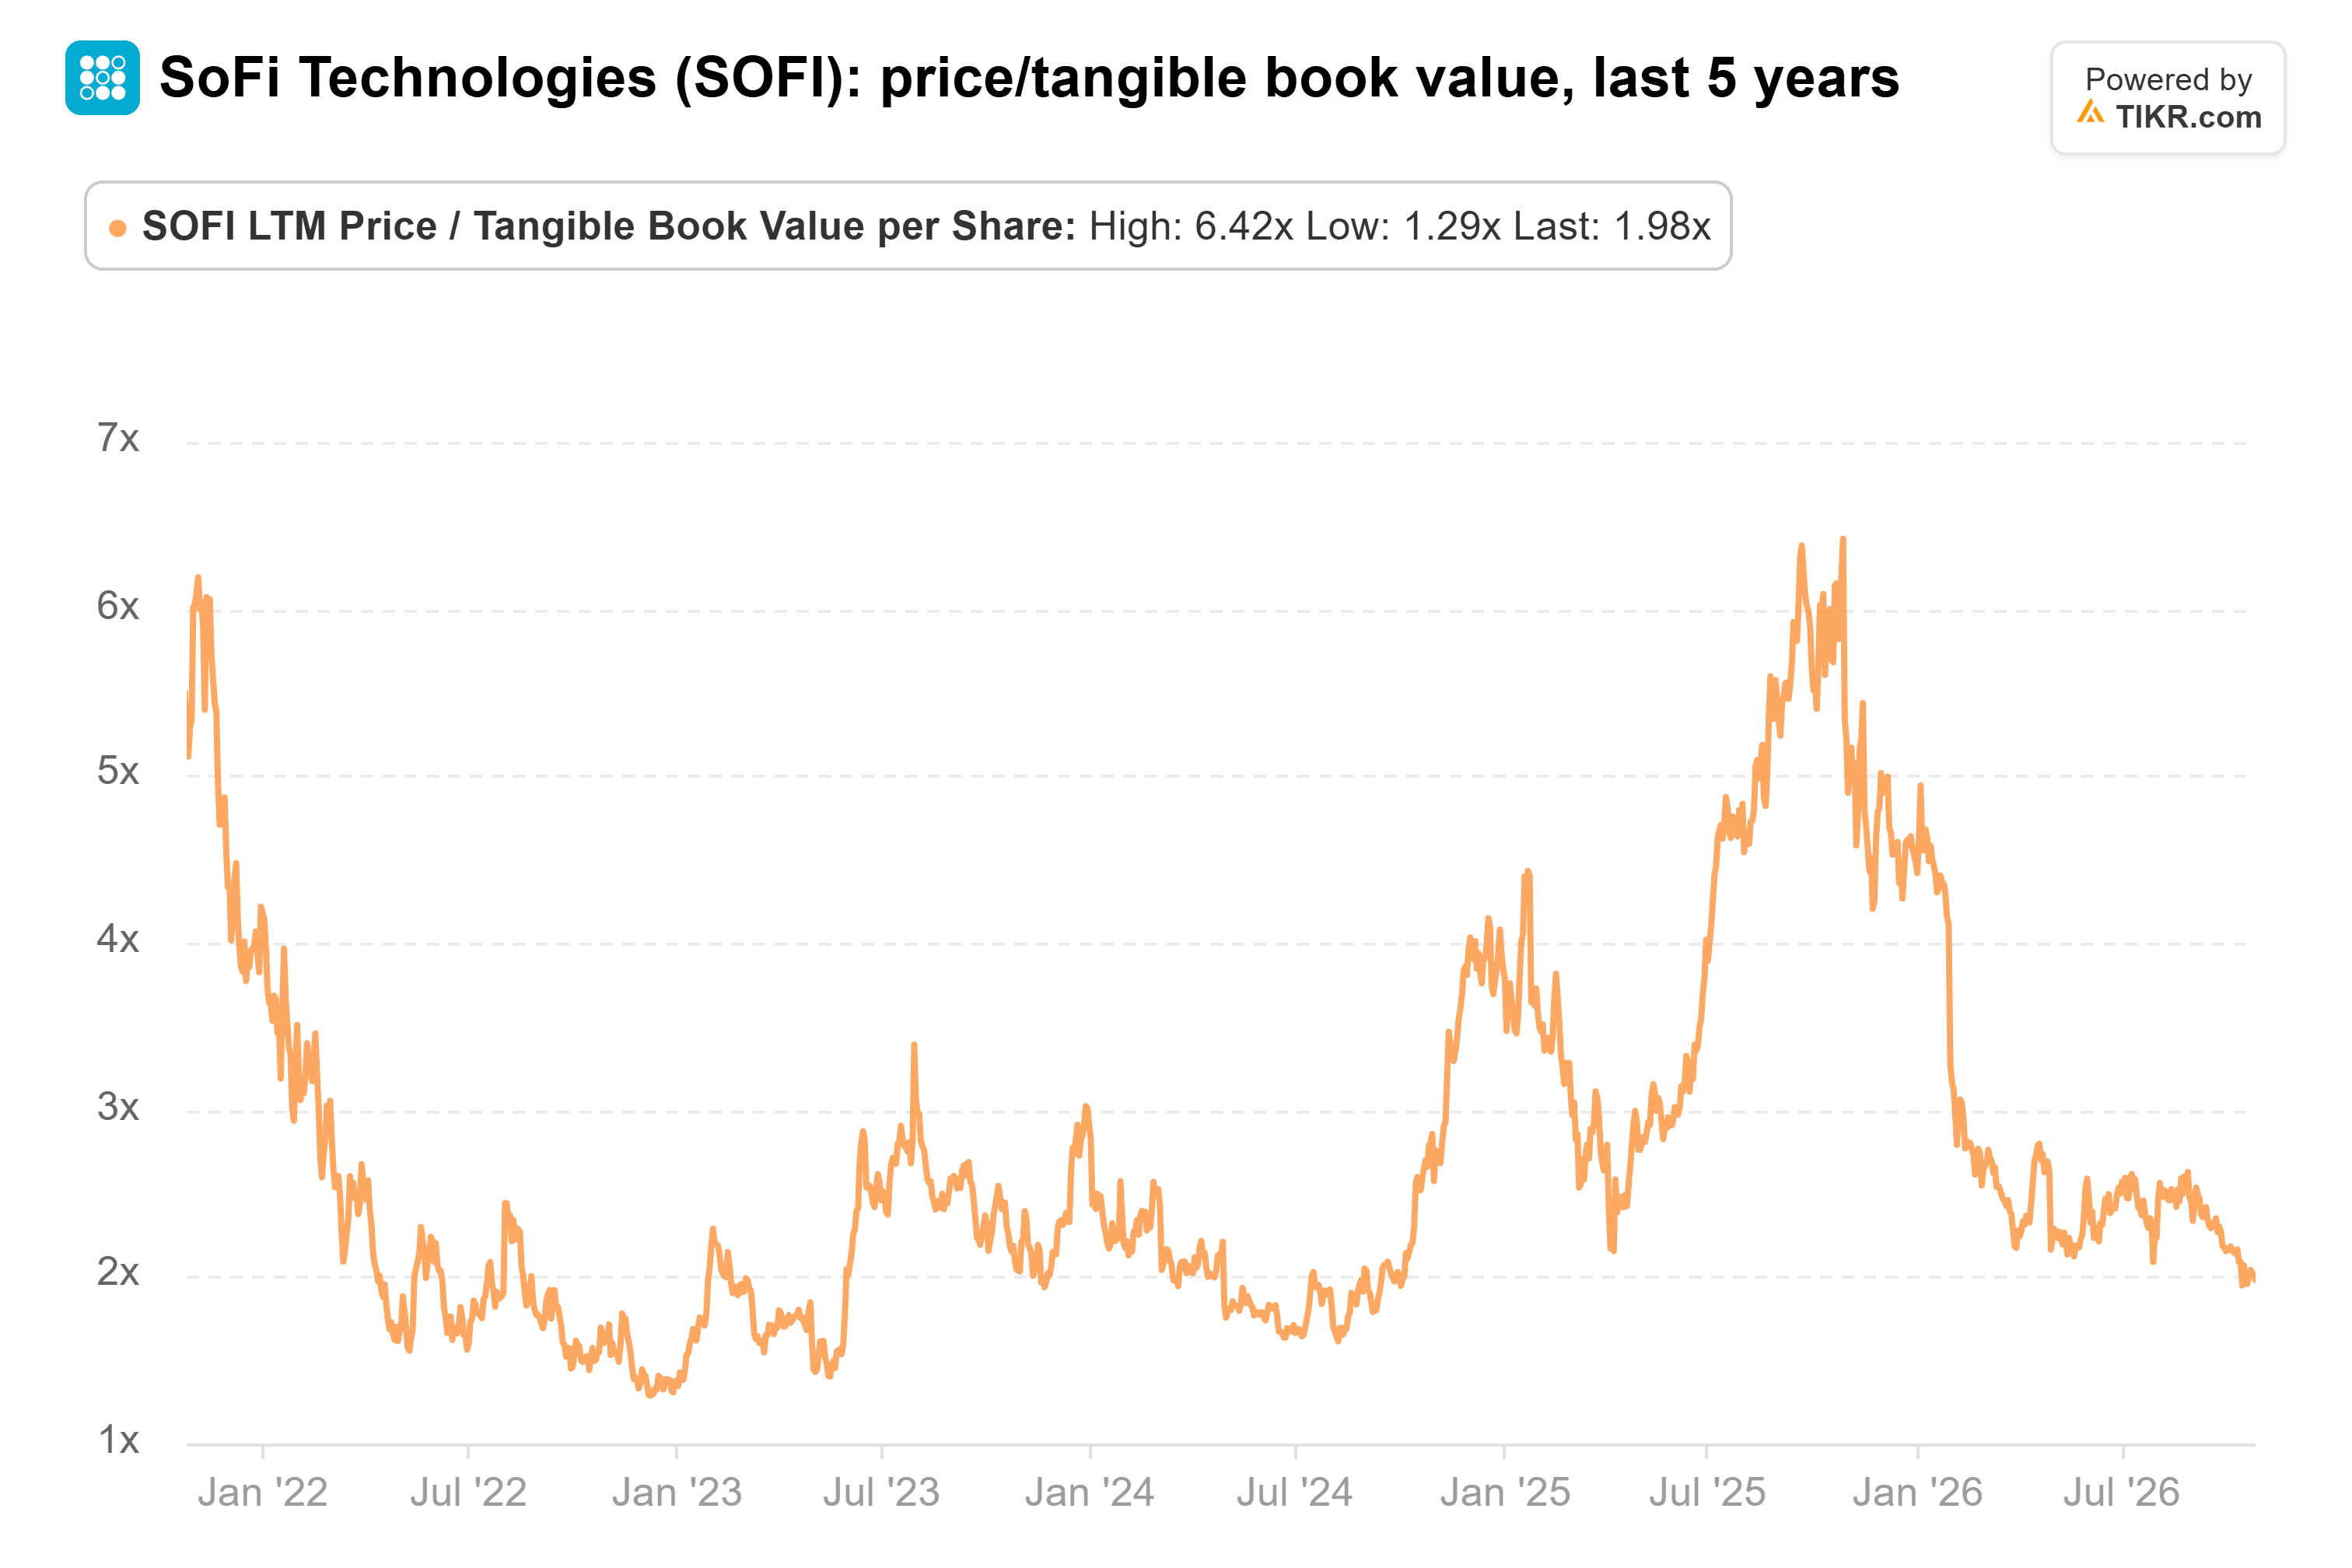
After Tuesday’s jump, it’s closer to 2.3x, nowhere near the 6.4x peak of October 2025. And the $20 consensus target is still more than 20% above Tuesday’s close.
Rates are the catch
Of the $12.6 billion of personal loans SoFi made in the third quarter, it kept most on its own books at fair value. Charge-offs fell to 2.26%, but higher rates still cut their value.
My take: The 2027 outlook is as good as it looks, and at around 2.3x tangible book, SoFi is a buy.
Of course, the Fed decides later today, and a hike would test those loan marks. The fourth-quarter report early next year will be the first check on the road to $0.90.
So what is SoFi stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what SoFi could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!