Key Stats for Bank of America Stock
- Current Price: $56.03
- Target Price (Mid): ~$77
- Street Target: ~$69
- Potential Total Return: ~38%
- Annualized IRR: ~8% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
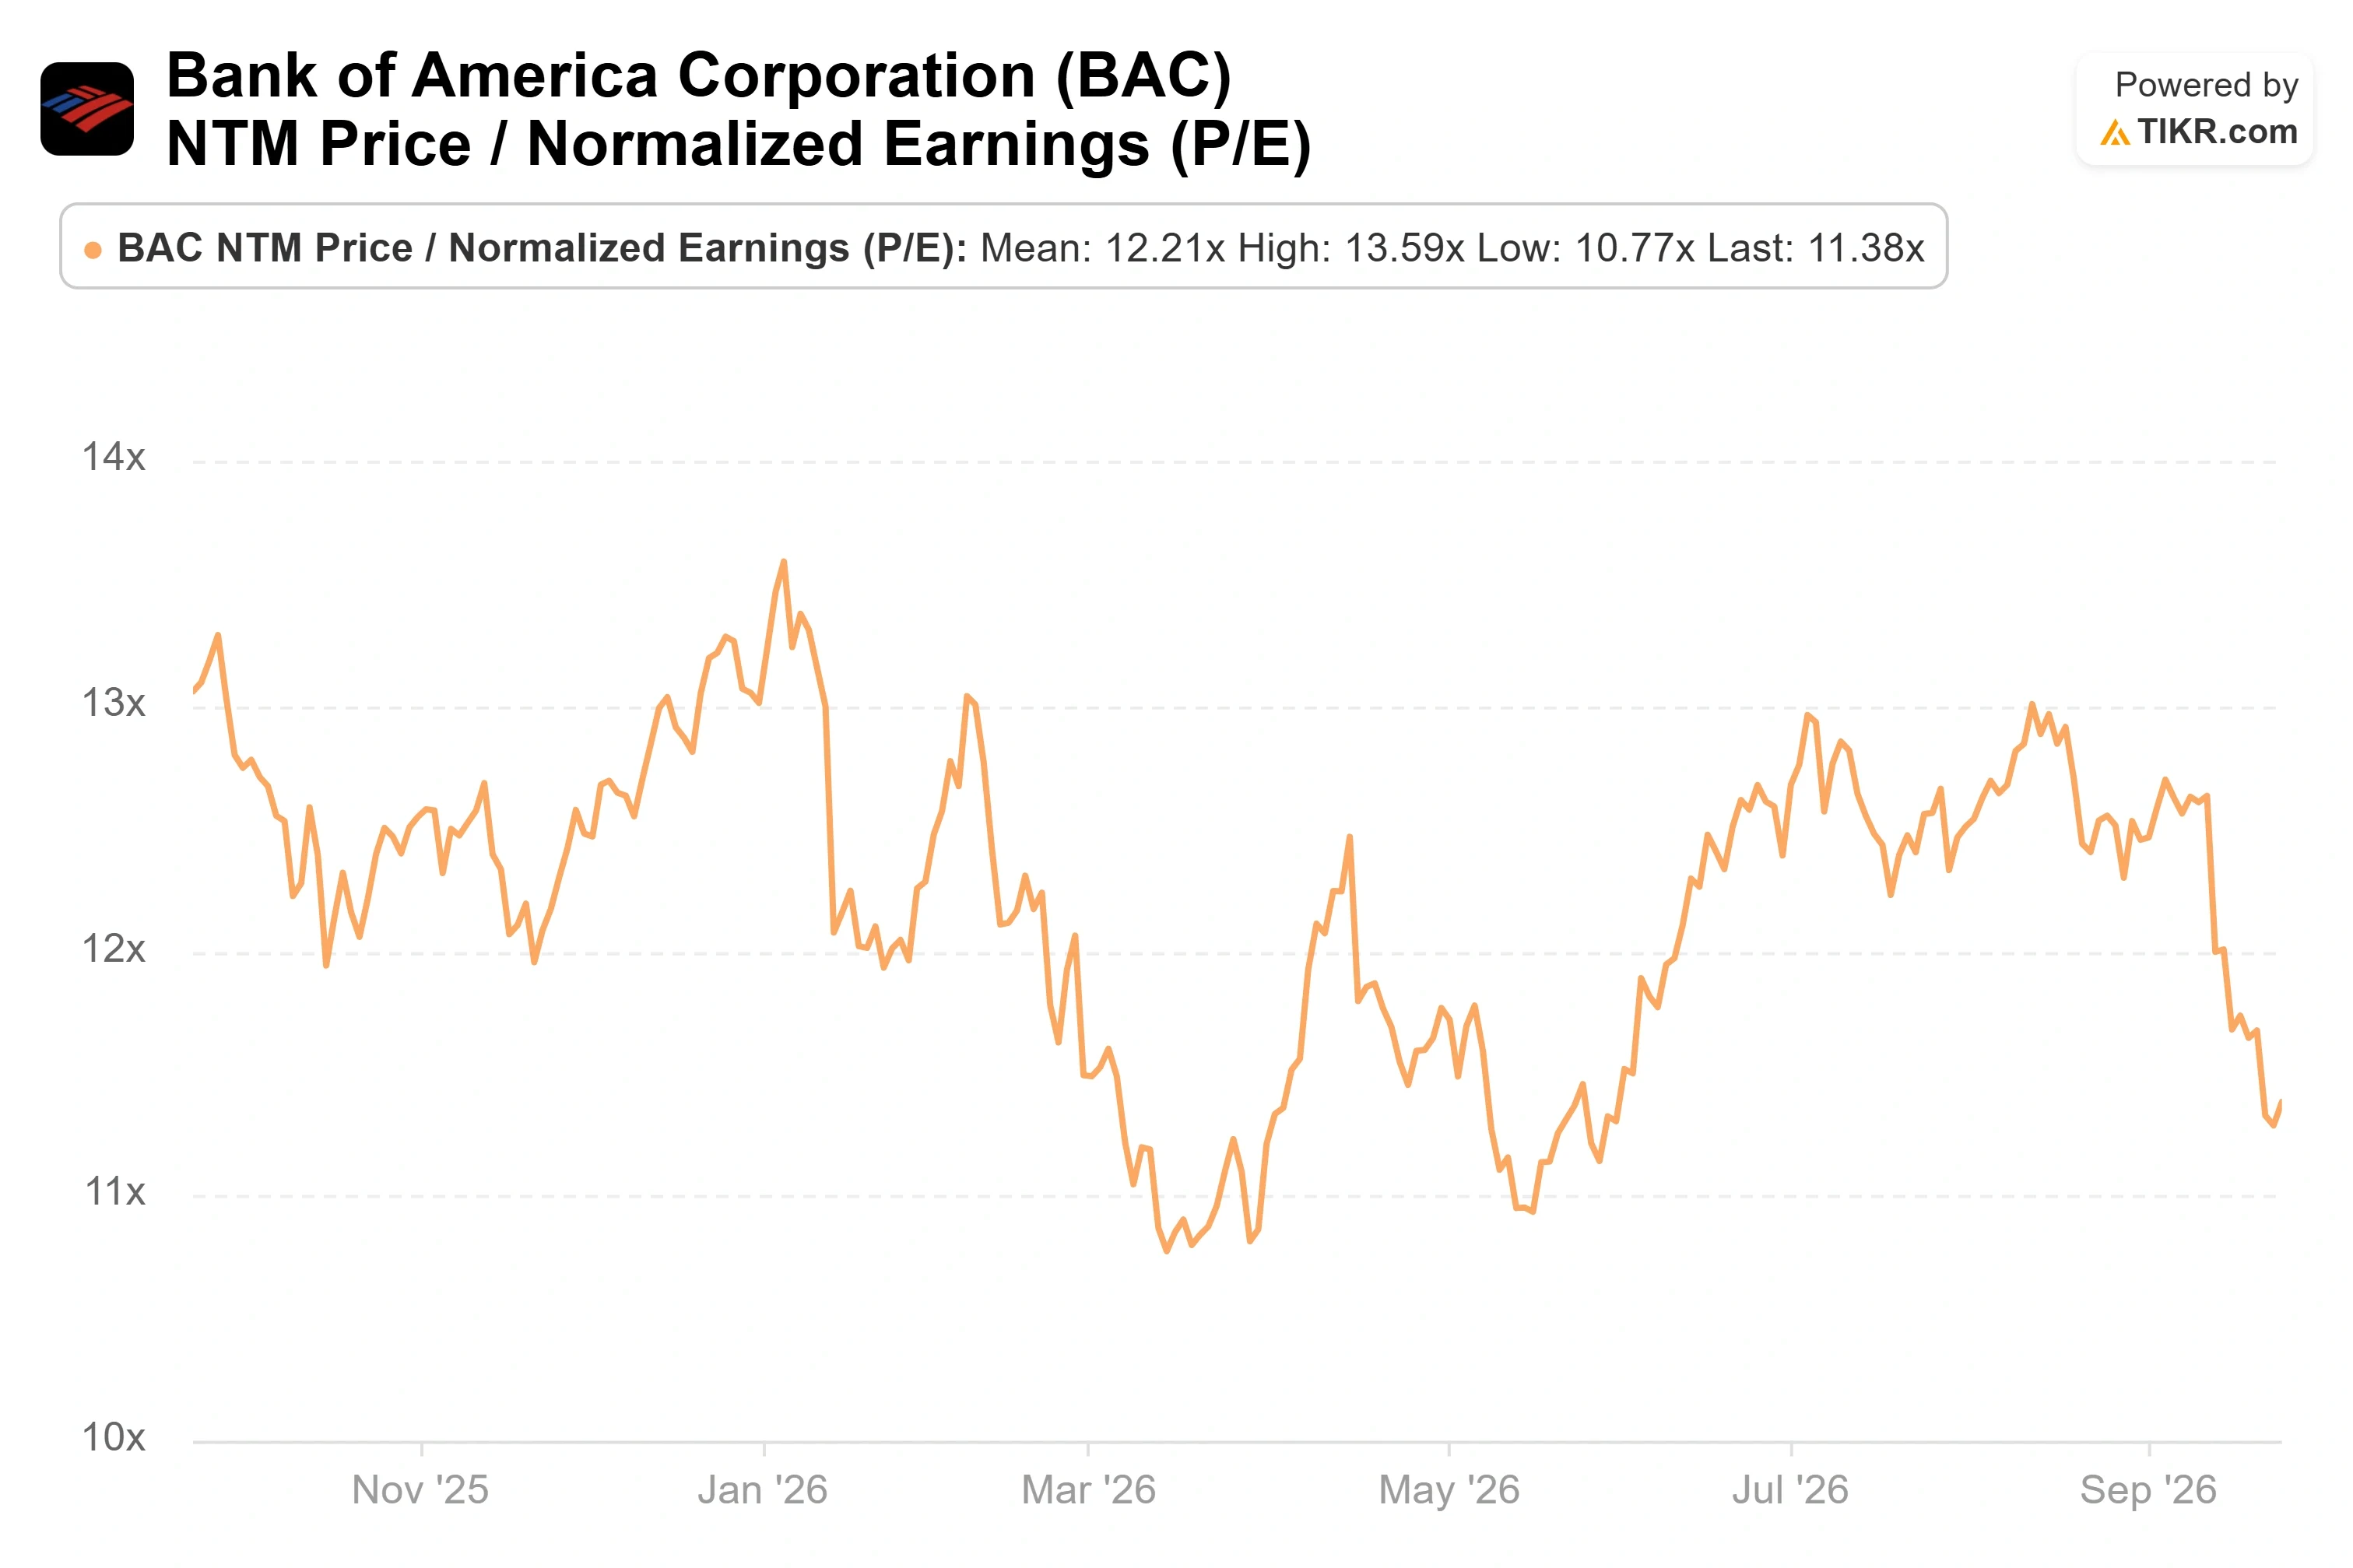
Bank of America (BAC) closed at $56.03 on September 24, 2026, less than 2% above its $55.00 close at the end of 2025. Over the same stretch, its forward P/E fell from about 13.0x to about 11.4x. That happened because the next-twelve-month earnings estimate rose from around $4.23 to around $4.92 per share while the price stood still, and part of that rise reflects the 12-month window rolling toward 2027.
On September 22, bank stocks fell on worries about AI competition and a flattening yield curve. The next day, Co-President Jim DeMare told Bank of America’s Financials CEO Conference in London, an event listed in the bank’s investor relations materials, that he is “not seeing any deterioration” in the U.S. economy, though growth may not be at its highest level of the past 12 months. The October 14 report will test whether that read extends to the bank’s own businesses.
AI Fears Hit Wealth and Consumer Franchises. DeMare Says Balances Remain Elevated
Reuters reported that the S&P 500 bank index fell 3% on September 22, with money managers such as Charles Schwab, down 6.1%, and Ameriprise, down 4.4%, among the biggest financial decliners. It linked the move to AI competition, uncertainty around AI-related IPOs, and a two-year to 10-year Treasury spread at its flattest since March 2025. A Gabelli fund manager told Reuters the AI worry centered on Meta’s Muse app competing in wealth management. Separately, Bloomberg described a broader fear that AI agents erode consumer inertia.
Bank of America fell with the bank index, and it is exposed on both fronts. Consumer Banking produced $43.673 billion of 2025 revenue and $12.245 billion of net income, the most of any segment. Global Wealth & Investment Management added $24.883 billion of revenue.
DeMare did not address Muse or AI agents. His customer data points the other way for now:
- Deposit balances across all three income groups are “elevated to what we’ve seen historically.”
- Wage growth for the lowest tercile, measured on a three-month rolling basis, now outpaces the higher two groups.
- Discretionary spending is growing in all three groups.
On wealth, he said Merrill is on track to hire more financial advisers in 2026 than in 2025.
Reported figures end June 30, before the selloff. Second-quarter average deposits reached $2.02 trillion, the 12th consecutive quarter of growth, but Global Banking drove most of it, and Consumer Banking deposits rose 1% to $957 billion. DeMare’s AI examples were internal, including coding productivity gains of 15% to 20% across “the 19,000 or 20,000 people we have coding.”

See historical and forward estimates for Bank of America stock (It’s free!) >>>
At About 11x Forward Earnings, Bank of America Trades in Line With Citi
Bank of America’s forward P/E of about 11.4x matches Citigroup’s and sits below JPMorgan’s roughly 14.0x. PNC (about 10.9x) and U.S. Bancorp (about 10.7x) trade slightly lower. TIKR’s competitor data does not include peer returns, so it cannot show whether the JPMorgan gap is earned. What it does show is Bank of America’s multiple falling while its second-quarter 2026 return on tangible common equity reached 17.0%, inside the 16% to 18% target set at its November 2025 investor day.
DeMare said choices between investing and returning capital should be “marginally accretive on these targets that we have of 16% to 18%.” Analysts remain positive: 15 Buys, 6 Outperforms, 3 Holds, 0 Underperforms, and 0 Sells, with a mean target of around $69, about 22% above the September 24 close.
Capital markets explain part of the discount. On September 14, CEO Brian Moynihan guided third-quarter investment banking fees down more than 10% and said Bank of America would likely trail the roughly 10% industry decline because it is less exposed to the busiest deal areas. He also said, “We feel very good about the underlying U.S. economy,” which puts both executives on the same read of consumers and credit.
The Federal Reserve’s first rate hike since 2023, on September 16, cuts both ways. It can lift lending margins, but Moynihan cautioned that higher rates slow some financing demand. DeMare called the second quarter “a lights-out quarter, I think, by any measure” and urged a year-over-year view because “quarter-to-quarter, you’re going to have the noise.”
Consensus expects third-quarter EPS of around $1.16, up from $1.06, on revenue of around $31.2 billion versus $28.088 billion. In the second quarter, EPS of $1.21 beat the $1.13 estimate, and the stock rose 1.60% on July 14, 2026. The bank has also hired 34 or 35 managing directors so far in 2026 as it builds out investment banking.
See how Bank of America performs against its peers in TIKR (It’s free!) >>>
TIKR Advanced Model Analysis
- Current Price: $56.03
- Target Price (Mid): ~$77
- Potential Total Return: ~38%
- Annualized IRR: ~8% / year

See analysts’ growth forecasts and price targets for Bank of America stock (It’s free!) >>>
The mid case points to around $77 by December 31, 2030, a total return of around 38%, or around 8% a year. Its assumptions span the model’s 2025 to 2035 forecast window:
- Revenue: a CAGR of around 3.5%, below TIKR’s 5.6% five-year historical rate.
- Margin: a net income margin of around 28%, versus 25.7% in 2025.
- Multiple: the P/E shrinks by around 1.5% a year.
The two revenue drivers are net interest income, which Moynihan said is tracking the investor-day outlook, and wealth fees, where he expected third-quarter asset management fees to rise 10% to 15%. The margin driver is operating leverage, including the coding gains DeMare described. The primary risk is the multiple, which the mid case already has shrinking.
If deposits and wealth flows hold and the multiple stabilizes, returns could exceed the mid case. The low case still assumes around 3% revenue growth, so a real AI-driven loss of customers could land below every scenario the model shows.
Conclusion
Bank of America reports third-quarter 2026 results at about 6:45 a.m. ET on October 14. Investment banking fees inside Moynihan’s $1.6 billion to $1.8 billion guide, with EPS at or above around $1.16, would show the slowdown landed where management said; fees below $1.6 billion would mean it ran deeper. Third-quarter deposit averages will mostly predate the September 22 selloff, so management’s comments on deposit and wealth flows since then are the first real read on whether AI fears belong in the multiple.
See what stocks billionaire investors are buying so you can follow the smart money with TIKR.
Should You Invest in Bank of America?
The only way to really know is to look at the numbers yourself. TIKR gives you free access to the same institutional-quality financial data that professional analysts use to answer exactly that question.
Pull up Bank of America, and you’ll see years of historical financials, what Wall Street analysts expect for revenue and earnings in the quarters ahead, how valuation multiples have moved over time, and whether price targets are trending up or down.
You can build a free watchlist to track Bank of America alongside every other stock on your radar. No credit card required. Just the data you need to decide for yourself.
Analyze Bank of America on TIKR Free →
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!