Key Stats for Arm Holdings Stock
- Current Price: $306.34
- Target Price (Mid): ~$1,368
- Street Target: ~$289
- Potential Total Return: ~346%
- Annualized IRR: ~39% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
Arm Holdings (ARM) fell 7.88% on September 24 to close at $306.34, and almost none of it was about Arm. The 10-year Treasury yield pushed above 5% after a hot reading on U.S. business activity, and the market repriced its most expensive growth names first. At more than 300 times trailing earnings, Arm sat at the top of that list.
What makes this drop different from the selloffs earlier in the year is who else is now exposed to it. Days before, on September 18, SoftBank increased a margin loan backed by its Arm shares to $25 billion from $20 billion. Arm’s majority owner has tied its own borrowing capacity to Arm’s share price, so a stock already priced for perfection now carries a second sensitivity that has nothing to do with royalties or AI chips.
SoftBank Turned Arm’s Price Into Its Own Collateral
SoftBank owns about 86% of Arm, and it is funding an enormous AI spending campaign, anchored by a multibillion-dollar investment in OpenAI. To raise cash without selling Arm stock, it has leaned on a margin loan secured by that stake, and this month it renegotiated the facility up to $25 billion, as first reported by Bloomberg. Lenders reportedly offered more than SoftBank sought, a sign banks are comfortable taking Arm shares as collateral at current prices.
Margin loans carry loan-to-value limits, so a sharp drop in the collateral can shrink the borrowing base or trigger a call that forces selling. That creates a feedback loop the stock did not have a year ago: an Arm decline pressures SoftBank’s funding math, which can invite more selling, which pressures Arm again. It changes nothing about the operating business, but it adds technical fragility on top of an already extreme valuation, exactly the kind of pressure a jump in the 10-year yield above 5% can set off.

See historical and forward estimates for Arm Holdings stock (It’s free!) >>>
The Business Is Not the Problem
In its most recent quarter (fiscal Q1 2027, reported July 29), revenue rose 22% year-over-year to a record $1.29 billion, and non-GAAP EPS of $0.45 beat both guidance and the $0.40 Street estimate. Data center royalty revenue more than doubled year-over-year again, and Neoverse cores have crossed 1.5 billion shipped, the most recent 500 million in nine months against six years for the first billion.
The order book behind the new AGI CPU, Arm’s first in-house data center chip, now exceeds $2 billion against $1 billion of committed supply, and management says confidence in beating that $1 billion has risen. Getting the chips built is the harder part. CEO Rene Haas described the constraint bluntly on the July call: “It is a very, very, very tight market across everything, whether it’s memory, whether it’s test equipment, whether it’s substrates, whether it’s TSMC wafers.” That tightness is why the pipeline outruns bookable revenue, and it delays the exact chip sales the valuation counts on.
The other soft spot is smartphones. Higher memory prices are squeezing handsets, and CFO Jason Child walked full-year royalty growth down toward the high teens from roughly 20%. The mature business is cooling just as the growth business inflects, and none of that is what moved the stock on September 24.
What Investors Are Actually Paying For
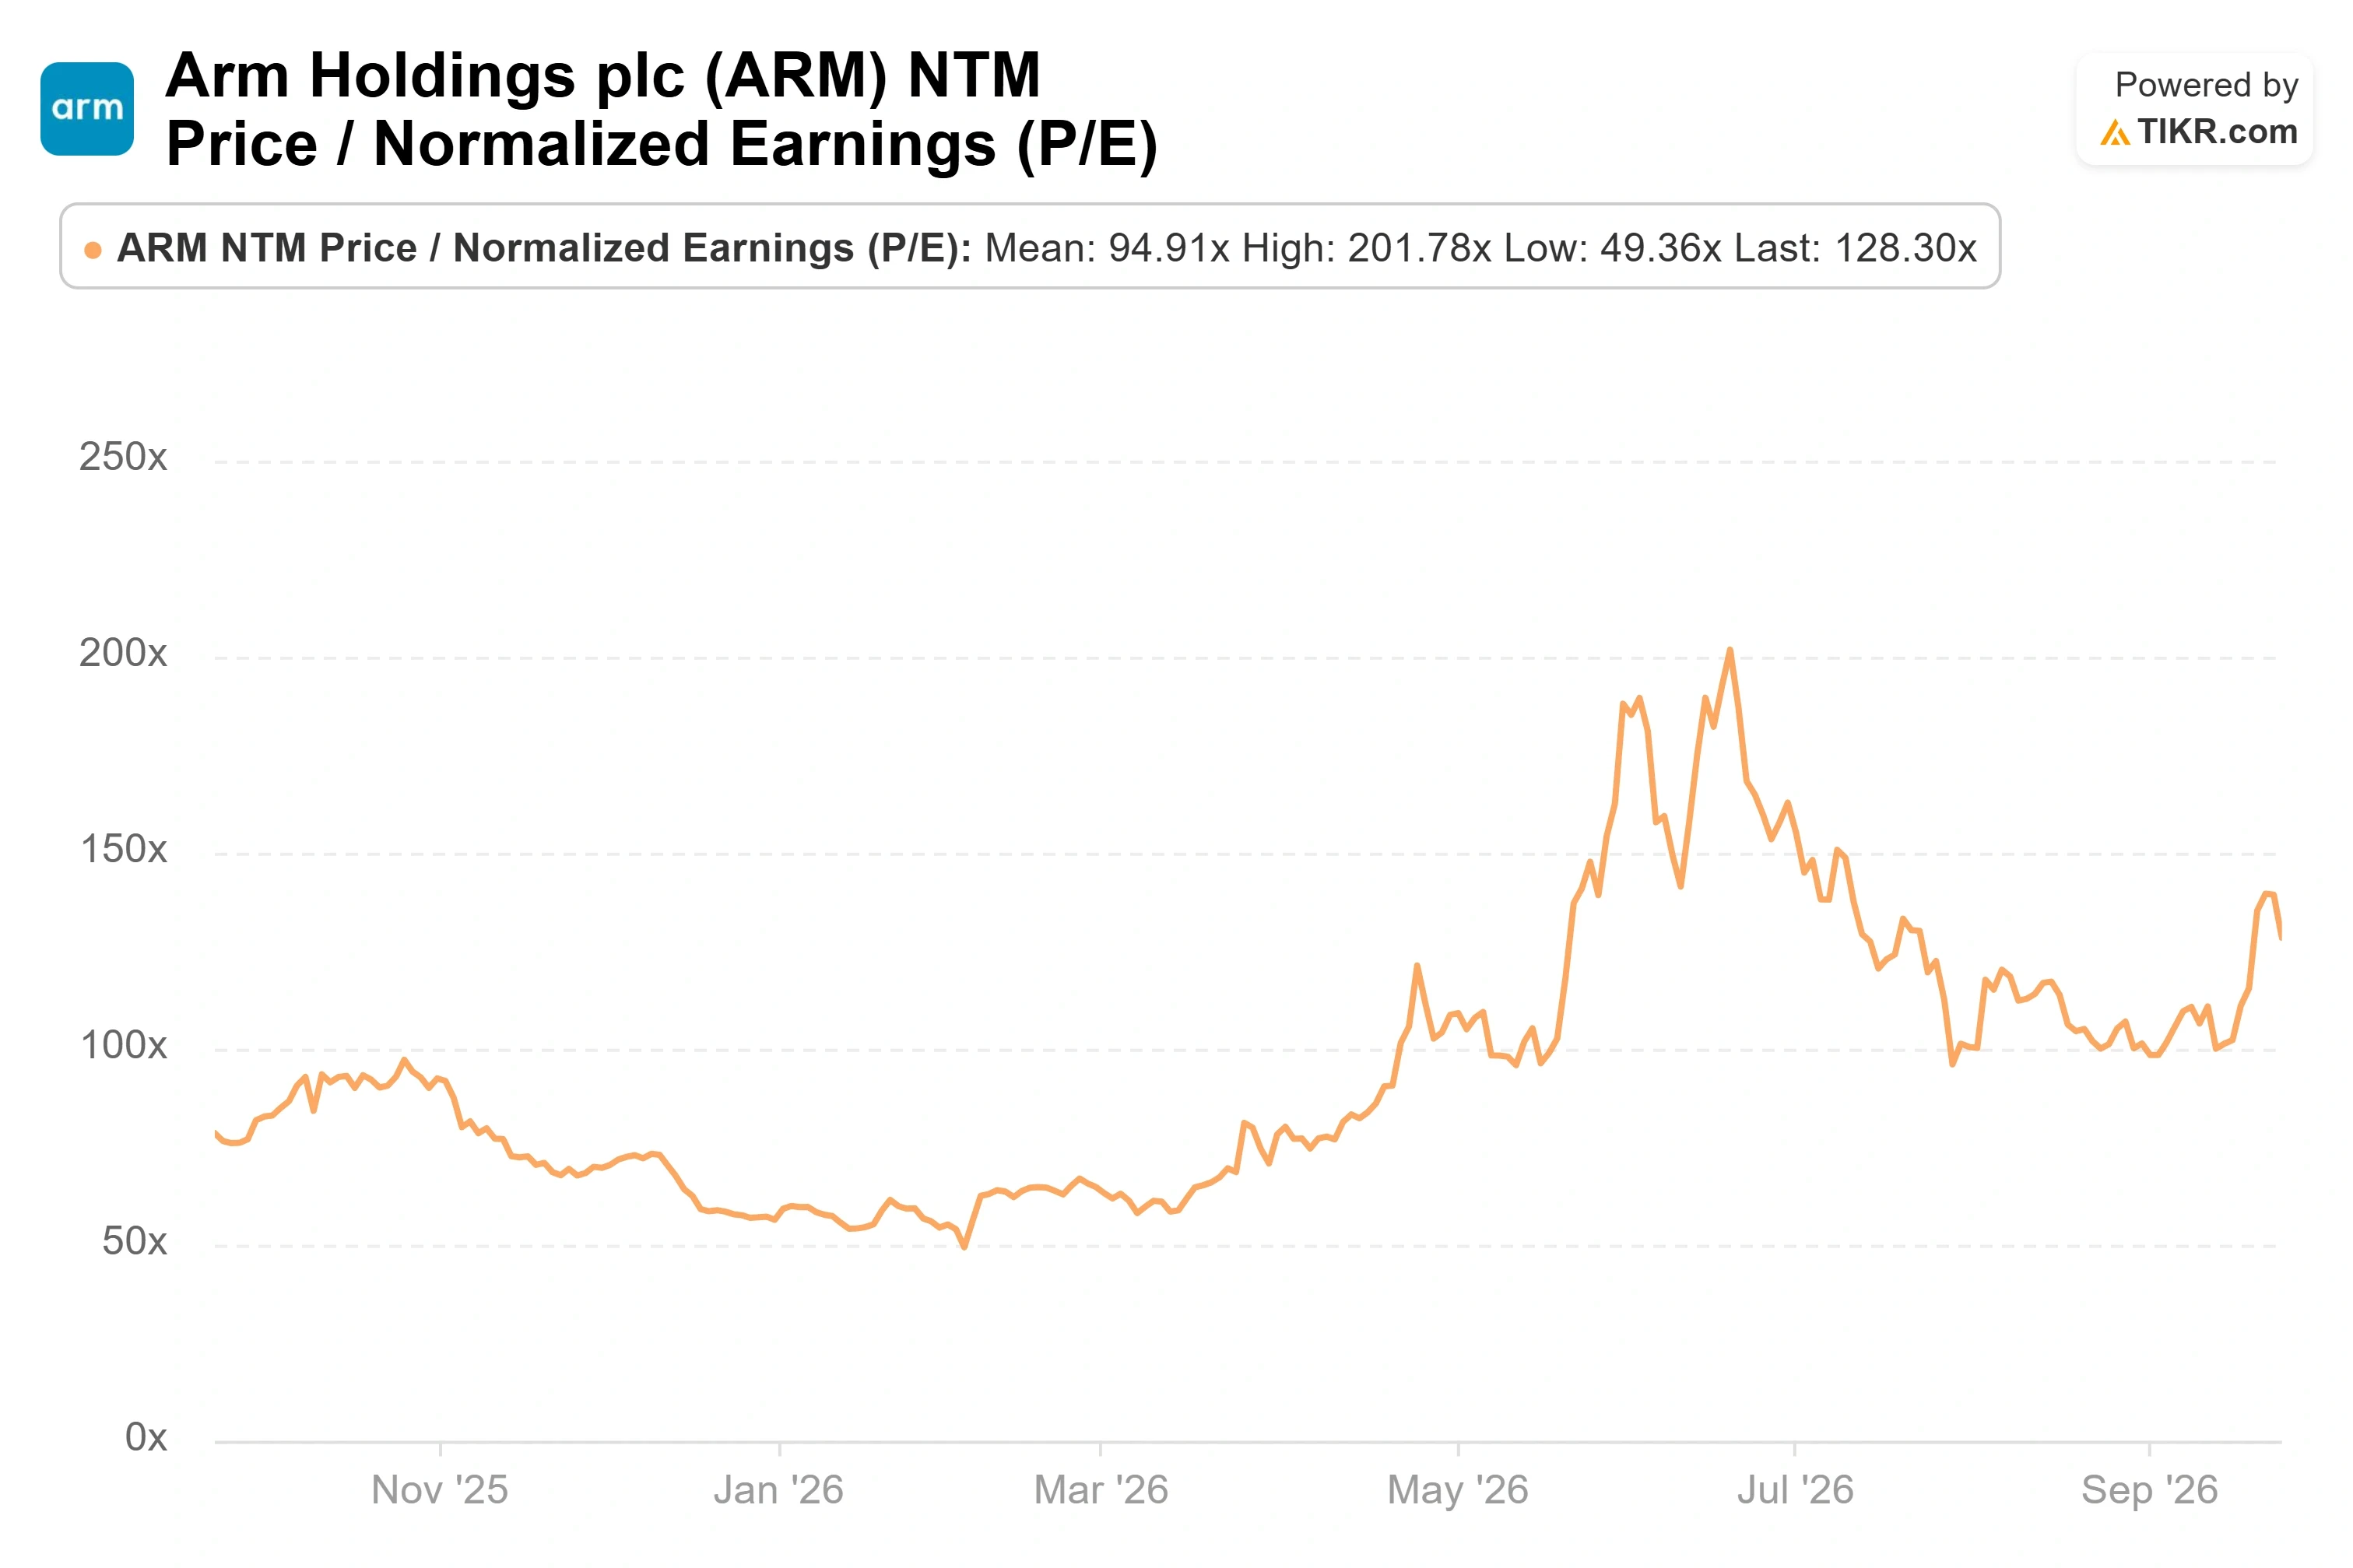
Even after the drop, Arm trades near 312 times trailing earnings and about 128 times forward earnings, a price-to-earnings ratio unmatched in its group, against a semiconductor peer set whose forward P/E averages roughly 67 times on TIKR’s Competitors page. Rambus sits near 31 times, and even fast-growing Global Unichip trades near 108. Arm is priced as a separate asset class, and that price is a forecast about the next five years.
The one piece of support is that the Street’s mean target of $288.71 now sits just below the market price, a reversal from the summer when the stock traded far above it. Over the past year, that configuration has tended to mark resets rather than tops. Whether it repeats depends on execution Arm has promised but not yet put in the income statement, and the stock now has to clear both the valuation bar and the leverage overhang at once.
See how Arm Holdings performs against its peers in TIKR (It’s free!) >>>
TIKR Advanced Model Analysis
- Current Price: $306.34
- Target Price (Mid): ~$1,368
- Potential Total Return: ~346%
- Annualized IRR: ~39% / year

See analysts’ growth forecasts and price targets for Arm Holdings stock (It’s free!) >>>
The TIKR model uses the mid-case scenario, a long-horizon view rather than a next-year call. It points to a price near $1,368 by early 2031, roughly 346% total return, or about 39% annualized over four and a half years. Nothing about today’s multiple makes Arm cheap; the case rests entirely on where the business goes.
Two drivers carry the revenue line: the data center royalty ramp, as Neoverse adoption widens across every major hyperscaler, and the AGI CPU, a merchant-silicon stream Arm has never had, now backed by a pipeline above $2 billion. The margin driver is the mix shift toward Armv9 and compute subsystems, which carry higher royalty rates. On mid-case assumptions, revenue compounds near 50% with net margin in the mid-40s.
The primary risk is the multiple itself, and the model bakes in high-single-digit annual P/E compression, so earnings growth has to outrun a shrinking multiple. The upside case is that AGI CPU demand keeps running ahead of its $2 billion pipeline and pulls the timeline forward. The downside case is heavier now than a month ago: a phone-royalty business still paying for an AI story it cannot yet monetize, with a parent whose funding tightens every time the stock falls.
Conclusion
Two things now decide this stock, and only one is about Arm. The first is royalty growth: the next report, guided to revenue near $1.38 billion with royalty growth in the low teens, tells you whether the data center engine is offsetting the smartphone drag. The second is the SoftBank loan, which turns any further slide in the price into a parent-level funding question that can feed back into the shares. Watch the royalty line when the December quarter reports, and watch how Arm trades on the next macro shock. A business beating its guide while the stock swings on yields and collateral math would say the market is pricing the parent’s leverage.
See what stocks billionaire investors are buying so you can follow the smart money with TIKR.
Should You Invest in Arm Holdings?
The only way to really know is to look at the numbers yourself. TIKR gives you free access to the same institutional-quality financial data that professional analysts use to answer exactly that question.
Pull up Arm Holdings, and you’ll see years of historical financials, what Wall Street analysts expect for revenue and earnings in the quarters ahead, how valuation multiples have moved over time, and whether price targets are trending up or down.
You can build a free watchlist to track Arm Holdings alongside every other stock on your radar. No credit card required. Just the data you need to decide for yourself.
Analyze Arm Holdings on TIKR Free →
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!