Key Takeaways
- Segment Mix Shock: Management Solutions grew just 4% to $1.2B in Q1 FY27, below the 5-6% full-year guide, while PEO and Insurance jumped 12% to $368M.
- Revenue Held, Splits Moved: Paychex reaffirmed its full-year revenue guide but raised PEO and Insurance growth to 7-8%, and flagged Q2 revenue growth of ~4% against two onetime prior-year items.
- Margin Expansion: Operating margin widened 280 bps to 38% and adjusted margin rose ~130 bps to 42%, with total expenses up only 1% YoY even as AI spending ran 5x last year’s level.
- Gibson on the Sell-Off: CEO John Gibson told analysts he “almost” felt like he was apologizing for successful execution of the company’s advisory strategy.
Paychex reaffirmed its full-year revenue guide and still lost 9% of its market value in a day. See what the model says the stock is worth: Analyze PAYX stock on TIKR for free →
Paychex Stock Fell 9% Because Its Best Business Stole Revenue From Its Biggest One
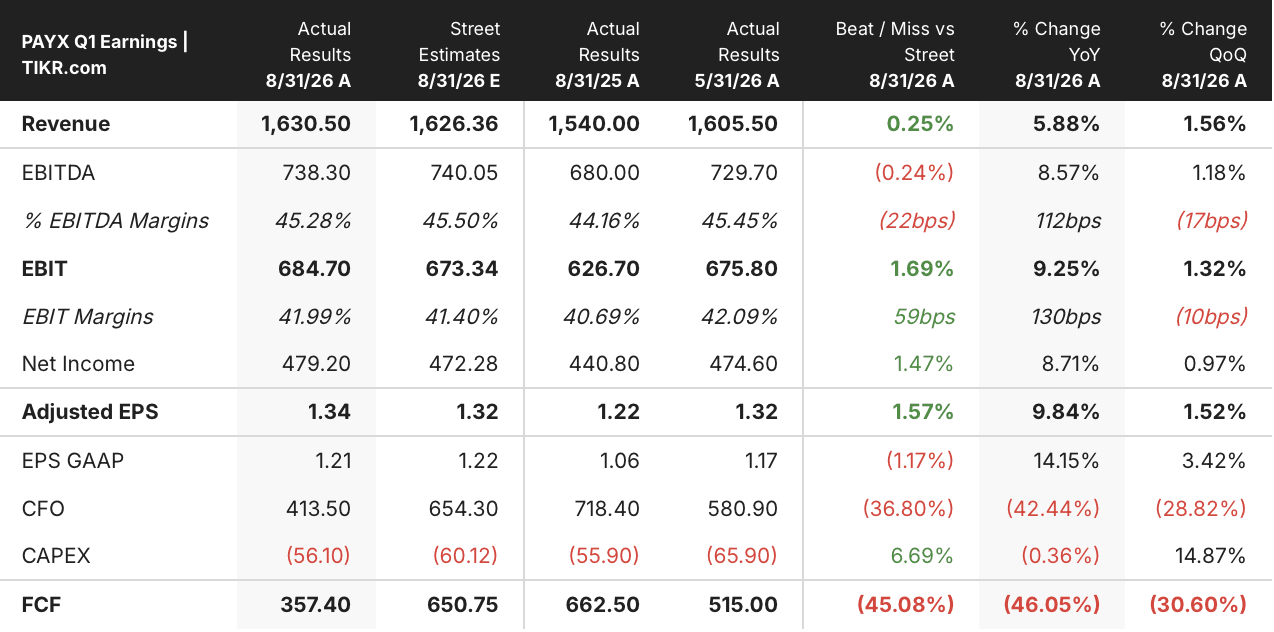
Paychex (PAYX) stock closed at $104.49 on September 23, 2026, down 8.77% after the payroll and HR services provider reported fiscal Q1 2027 results that beat its own internal revenue expectations. Total revenue rose 6% to $1.6 billion. Diluted earnings per share climbed 14% to $1.21, adjusted EPS rose 10% to $1.34, and operating margin expanded 280 basis points to 38%.
The damage came from one line: Management Solutions, the payroll and HCM software segment that carries roughly three-quarters of company revenue, grew 4.3% to $1.2 billion against a full-year guide of 5% to 6%.
That miss wasn’t demand. It was accounting geography. Paychex sells ASO (administrative services outsourcing, where the company handles HR tasks) and PEO (professional employer organization, where Paychex becomes co-employer and absorbs benefits administration). ASO revenue books to Management Solutions. PEO revenue books to PEO and Insurance. When a client upgrades from one to the other, revenue leaves the first bucket and lands in the second at roughly 3.5 times the size.
Those upgrades ran at double plan in the quarter. HCM sales reps referred nearly 50% more deals into PEO year over year, and broker referrals rose 43%. PEO and Insurance revenue grew 12% to $368 million on high-single-digit worksite employee growth and record retention, and management lifted the segment’s full-year guide to 7% to 8%.
CFO Bob Schrader framed the segment split on the Q1 earnings call as mechanical: “It’s a little bit left pocket, right pocket.” Strip the transfers out and Management Solutions organic growth sat near 5%, with price realization intact and client retention improving.
Gibson pushed harder, telling analysts the mix shift toward advisory solutions strengthens both the business model and the competitive position, and that he felt he was apologizing for executing too well.
Two things still argue for caution. Q2 revenue growth guides to 4% against a prior-year quarter that carried a onetime acquisition revenue synergy and realized portfolio gains, which means the back half must deliver growth in line with the last two quarters to reach the midpoint. And Paychex enters October and January PEO enrollment seasons into double-digit health inflation, with employee plan selection in Florida flowing directly through reported revenue.
Paychex raised its PEO guide while the stock dropped 9%. Check the valuation gap that created: See PAYX’s valuation model on TIKR for free →
TIKR Values PAYX Stock at $161, a 54% Gap From Thursday’s Close
TIKR’s mid-case model values Paychex at $161 by May 2031, implying 54% total return from the current price of $104, or 10% annualized over 4.7 years.
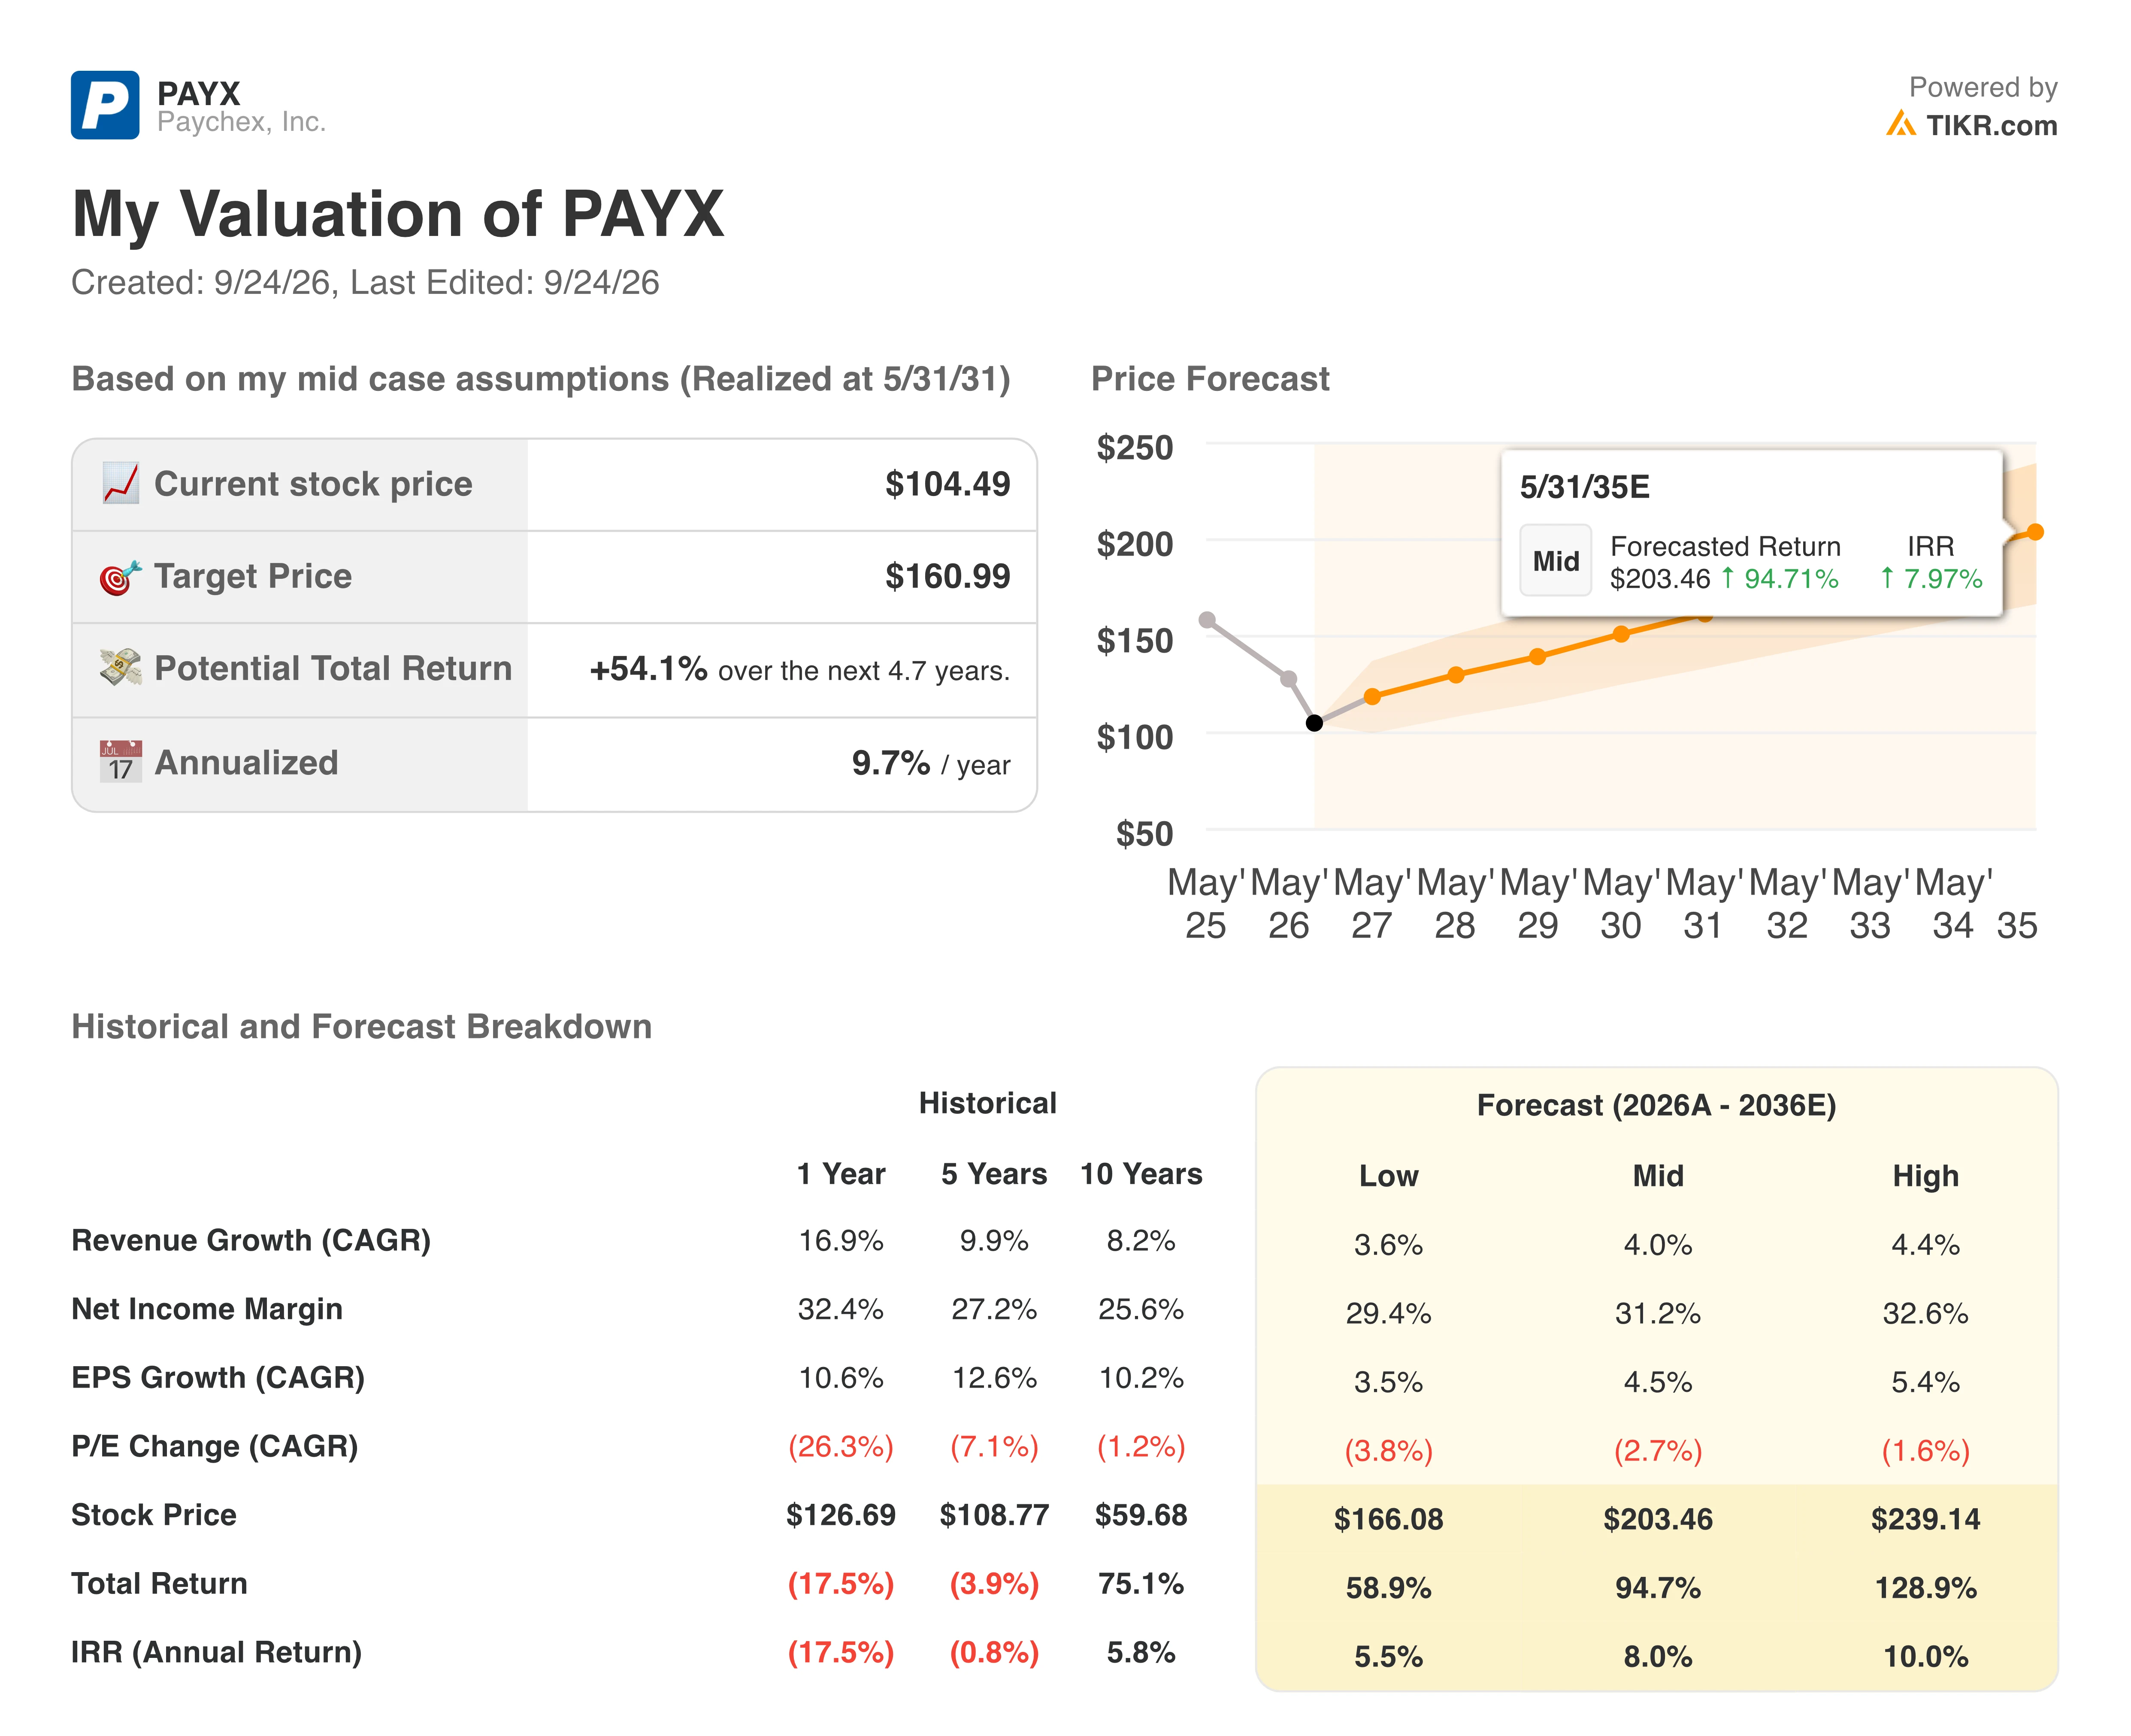
That return profile puts Paychex stock in territory rarely occupied by a mature payroll processor with a 47% rolling return on equity and a dividend that absorbed $424 million in the quarter.
The model’s mid case assumes 4% revenue growth and a 31% net income margin through the forecast window, both below what the company just delivered. Q1 margin expansion of 280 basis points on 1% expense growth, driven by 2,000-plus AI agents and a 20% reduction in manual payroll processing, sits well ahead of that bar, and the PEO mix the market punished carries higher lifetime value and better retention than the revenue it replaced.
TIKR’s model puts PAYX at $161 by 2031 against a $104 close. Compare that target to the quarter’s margin trend: Run the numbers on TIKR for free →
Should You Invest in Paychex, Inc.?
The only way to really know is to look at the numbers yourself. TIKR gives you free access to the same institutional-quality financial data that professional analysts use to answer exactly that question.
Pull up Paychex, Inc. stock and you’ll see years of historical financials, what Wall Street analysts expect for revenue and earnings in the quarters ahead, how valuation multiples have moved over time, and whether price targets are trending up or down.
You can build a free watchlist to track Paychex, Inc. alongside every other stock on your radar. No credit card required. Just the data you need to decide for yourself.
Access Professional Tools to Analyze X stock on TIKR for Free →
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!