Key Stats for Accenture Stock
- Current Price: $177.41
- Target Price (Mid): ~$269
- Street Target: ~$192
- Potential Total Return: ~52%
- Annualized IRR: ~11% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
Accenture (ACN) reports fiscal fourth-quarter and full-year results before the market opens on Thursday, October 1, with the stock down about a third in 2026 and trading near $177. The number that moves the stock will not be headline EPS. It will be whether the U.S. federal business turned back to growth exactly when management said it would, and what that signals about fiscal 2027.
On the June call, CFO Angie Park promised the federal drag would end this quarter. She also handed investors the rest of the fiscal 2027 setup: the acquisition contribution, and the timing of large deals that slipped out of the fiscal year. October 1 is the first read on all three, and it matters more than a penny of EPS beat or miss.
The FY2027 Exit Rate Is the Real Test
Federal has dragged on Americas growth all year, and Park was unambiguous on June 18: “our AFS headwind will sunset this quarter, and we expect that it will return to growth this quarter.” This is that quarter. If federal does not turn, the biggest single anchor on reported growth stays attached into 2027.
Accenture nearly doubled its fiscal 2026 acquisition budget to roughly $9 billion from $5 billion, anchored by an operational technology security platform. Park guided that these deals carry the company into fiscal 2027 with “slightly below 2%” of inorganic growth, real help for a business growing in the low single digits organically.
A couple of large managed-services contracts slipped into fiscal 2027 for what CEO Julie Sweet called “company-specific reasons,” and she was direct that they will not simply reappear in the fourth quarter. When they convert, it tells investors how much of the bookings backlog is real and how much is deferred. Set against that caution is one faster-growing piece: the OT security acquisitions carry $208 million in annual recurring revenue, growing at 48%, well above the core, and a step toward the platform-style revenue Accenture has been chasing.
See historical and forward estimates for Accenture stock (It’s free!) >>>
The Bar for the Print Itself
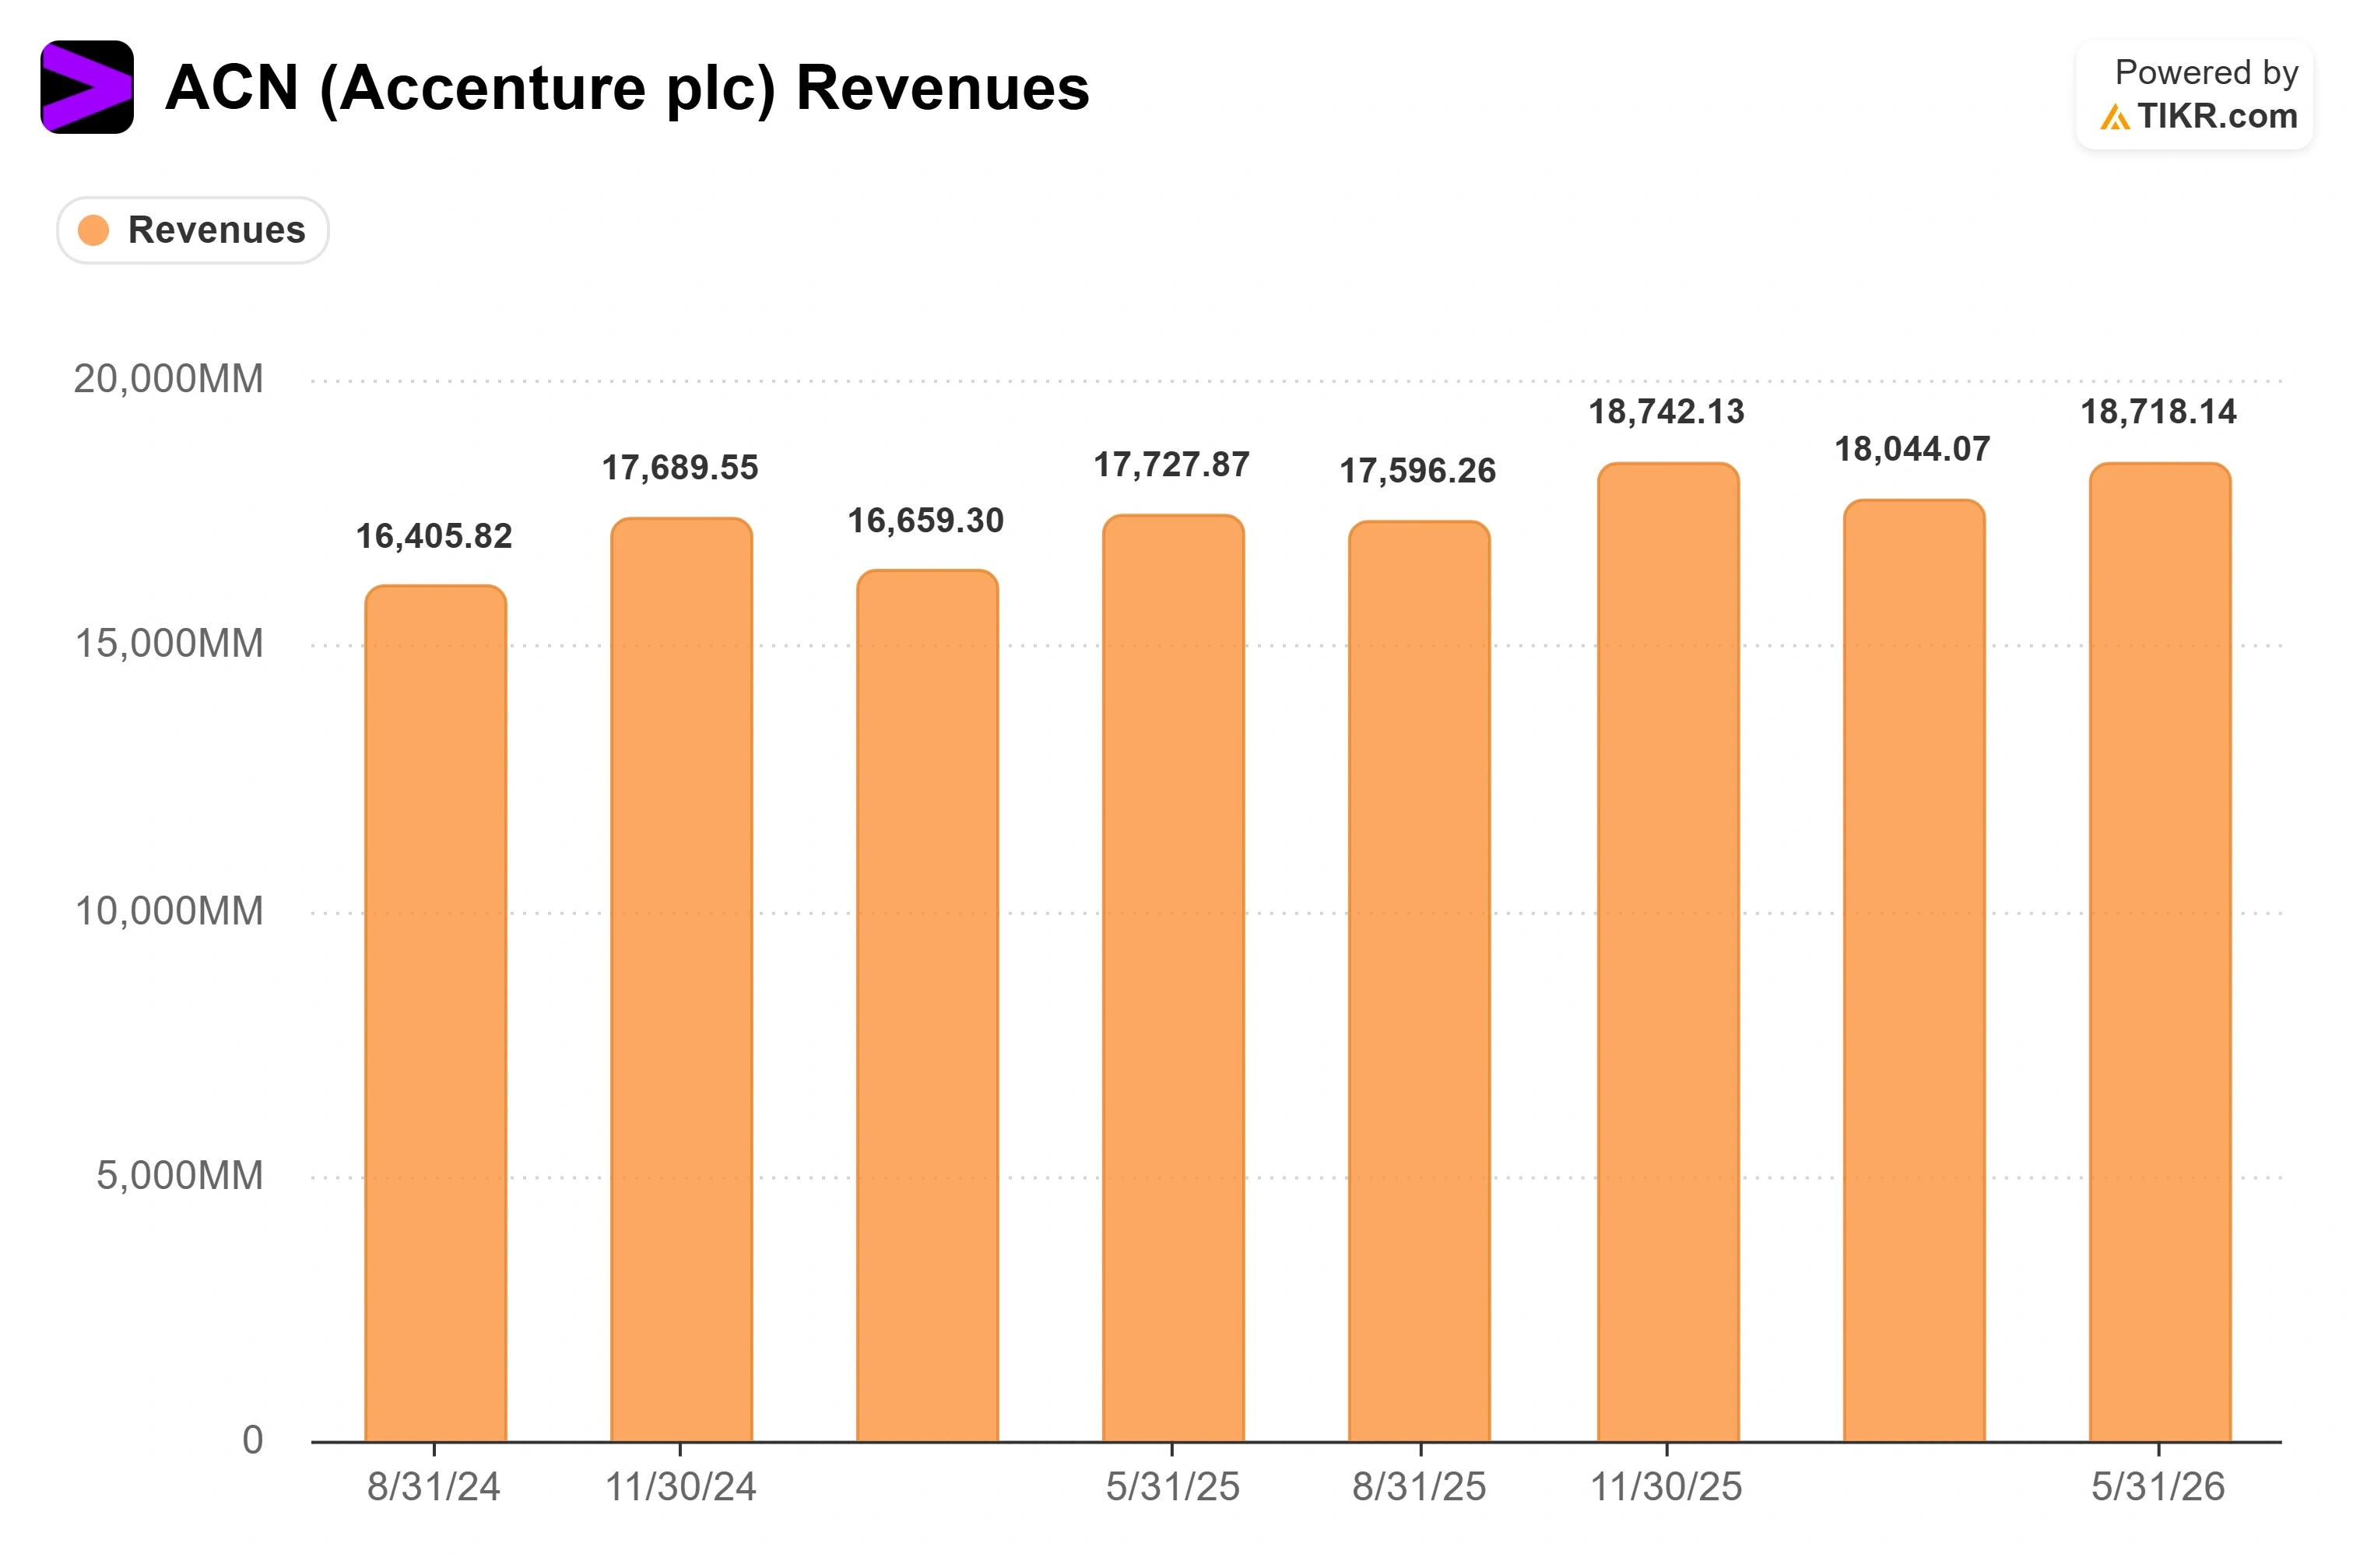
Wall Street models fourth-quarter revenue near $18.04 billion and adjusted EPS around $3.18, up from $3.03 a year ago. Accenture’s own June guidance put revenue at $17.75 billion to $18.4 billion, or 1% to 5% local-currency growth, and management warned more of that range than usual was in play after macro softness appeared late in the third quarter. For the full year, the company guided to adjusted EPS of $13.78 to $13.90 on 3% to 4% local-currency growth.
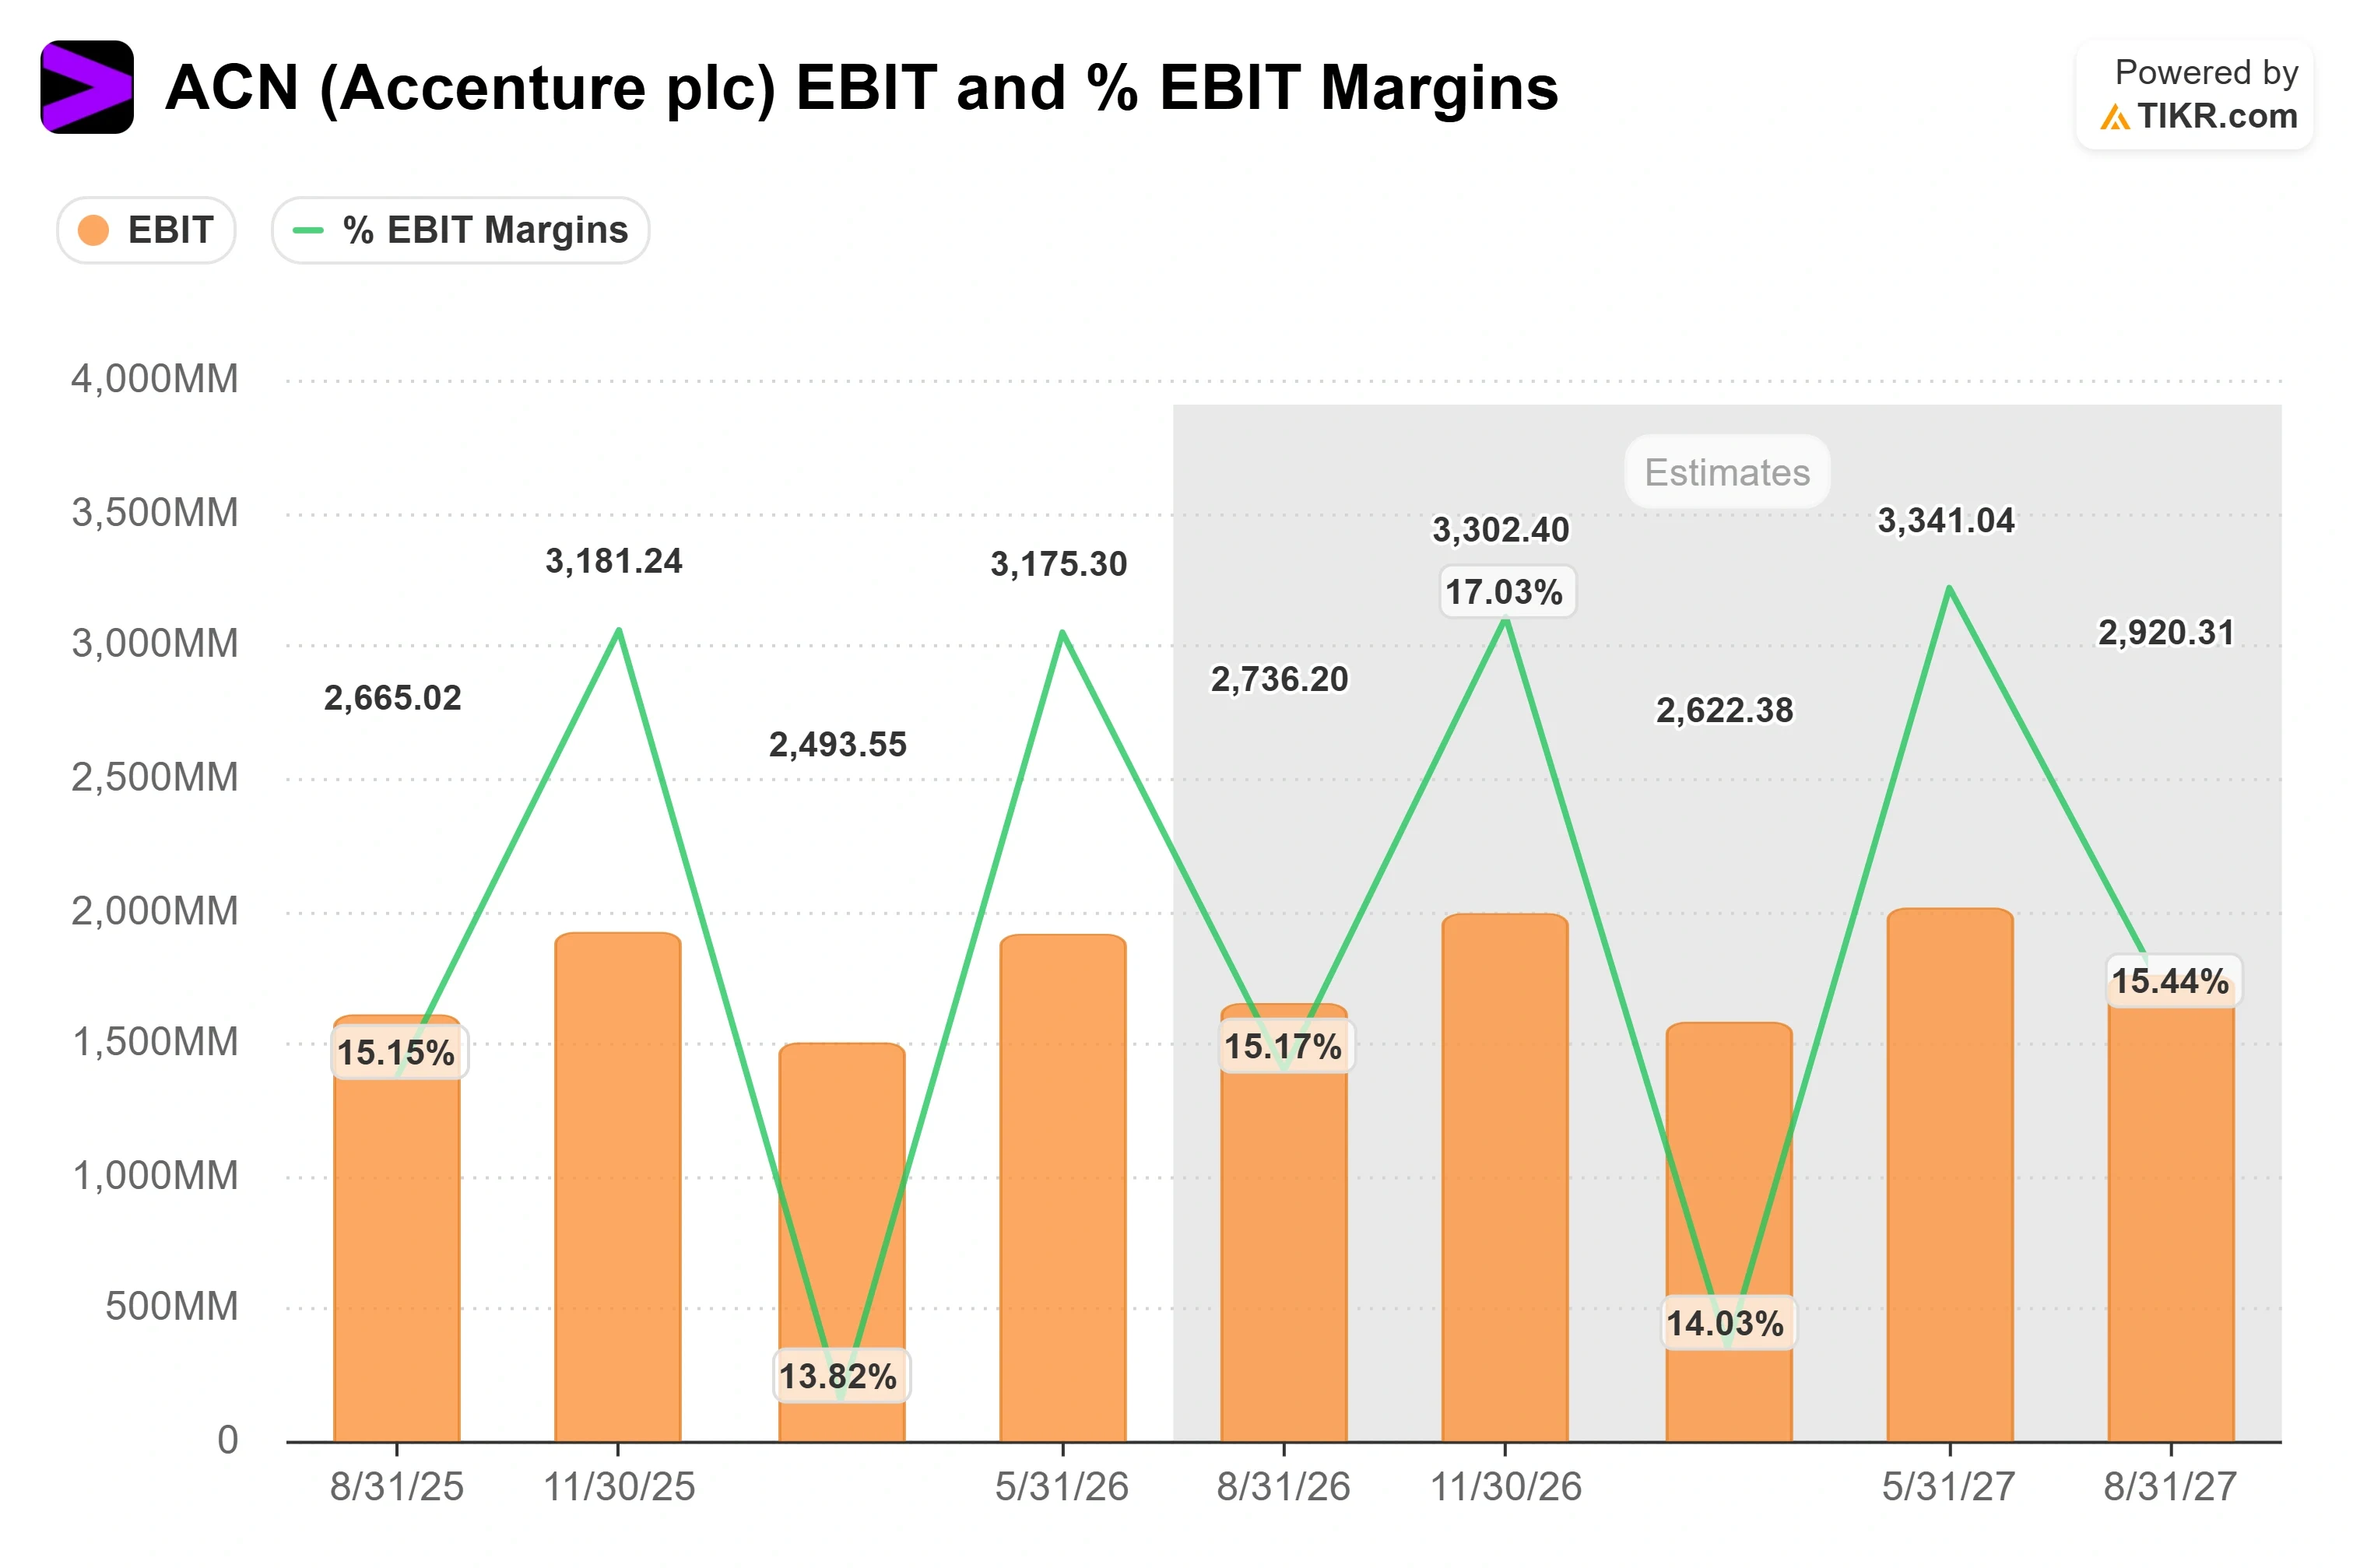
Third-quarter revenue of $18.72 billion landed just below the Street, yet adjusted EPS of $3.80 beat by about 2%, and EBIT margin reached 16.96%, up from 13.82% the prior quarter, even after a $100 million Middle East revenue hit. Profit has kept climbing while revenue barely moves. The recent trading tape shows how divided the market is on that gap: on September 18, Accenture announced an AI-safety partnership with Anthropic under which each company plans to invest at least $1 billion over five years, and the same day, Guggenheim downgraded the stock to Neutral and pulled its target, sending shares down about 5%. The stock then recovered about 3% the following Monday. The partnership is a spending commitment, not booked revenue, and several analysts, including BMO Capital, called its near-term financial impact limited even while raising targets.
On valuation, Accenture trades at roughly 12.4 times next-twelve-month earnings, below IBM near 17.8 times and Tech Mahindra near 18.4 times, though close to Cognizant at 9.4 times and Wipro at 12.4 times. The discount reflects the growth question, not quality: Accenture posts a return on invested capital of 27% and a gross margin of 32%, both stronger than most of the group. The market pays up for growth elsewhere and marks Accenture down until its top line reaccelerates.
See how Accenture performs against its peers in TIKR (It’s free!) >>>
TIKR Advanced Model Analysis
- Current Price: $177.41
- Target Price (Mid): ~$269
- Potential Total Return: ~52%
- Annualized IRR: ~11% / year

See analysts’ growth forecasts and price targets for Accenture stock (It’s free!) >>>
The TIKR mid case values Accenture at around $269, roughly 52% total upside, and an annualized return near 11%. Two revenue drivers carry it: a return to mid-single-digit organic growth once the federal drag clears, and close to 2% of inorganic contribution from the roughly $9 billion acquisition program entering fiscal 2027. The margin driver is continued operating leverage on a fixed-price mix that management said exceeds 60% of work, lifting net income margin from about 11.9% toward the low-12% range.
The primary risk is the one that defined the year: AI compresses demand for the advisory and staffing work Accenture bills, organic growth never reaccelerates, and the company buys growth rather than earning it. Upside is that margins hold, federal and acquisitions lift the fiscal 2027 exit rate, and the market re-rates a franchise trading below its own history. Downside is that revenue stays stuck near 1% to 2%, bookings keep slipping, and the stock stays cheap because growth never comes.
Conclusion
Two lines decide on October 1. The first is whether management confirms federal returned to growth, because Park promised that turn for this exact quarter and it is the cleanest read on the fiscal 2027 growth story. The second is fourth-quarter revenue against the $17.75 billion to $18.4 billion guide: the top half signals contained macro softness, the bottom confirms the deceleration that spooked investors in June. Federal turning with a mid-range print re-rates the stock; federal still soft leaves it a value trap until December.
See what stocks billionaire investors are buying so you can follow the smart money with TIKR.
Should You Invest in Accenture?
The only way to really know is to look at the numbers yourself. TIKR gives you free access to the same institutional-quality financial data that professional analysts use to answer exactly that question.
Pull up Accenture, and you’ll see years of historical financials, what Wall Street analysts expect for revenue and earnings in the quarters ahead, how valuation multiples have moved over time, and whether price targets are trending up or down.
You can build a free watchlist to track Accenture alongside every other stock on your radar. No credit card required. Just the data you need to decide for yourself.
Analyze Accenture on TIKR Free →
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!