


Key Takeaways
- Barclays upgraded Tesla to Overweight on Monday, raised its price target to $450 from $370, and called a SpaceX merger a key part of the bull case.
- Scott Galloway argues the merger would be a bailout in which Tesla holders win and SpaceX holders pay.
- Tesla’s normalized earnings per share fell from $3.12 in 2023 to $1.66 in 2025, while its forward P/E sits well above its three-year average.
- The deal would only favor SpaceX holders if Robotaxi and Optimus start earning, and the first merger terms will show how much SpaceX holders give up.
Tesla (TSLA) shares jumped [6%] on Monday after Barclays upgraded the stock because of a deal that hasn’t been agreed yet: a merger with SpaceX (SPCX).
Elon Musk said on SpaceX’s earnings call last week that both companies have formed special committees to discuss a merger. Barclays analyst Dan Levy now treats the deal as effectively settled and called it “a key part of the Tesla bull case.” He moved Tesla to Overweight from Equal Weight, raised his price target to $450 from $370, and expects “some premium to TSLA stock” when terms arrive.
On Monday’s episode of Prof G Markets, host Scott Galloway saw the deal differently. As he put it, “right now, Tesla’s the patient and SpaceX is the organ donor.”
He thinks Tesla holders are the winners. They’d swap shares of a shrinking car company for a stake in Starlink and AI, and SpaceX holders would pay for it.
Harsh. But the numbers mostly back him up.
TIKR tracks 44 analysts on Tesla. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Tesla, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Tesla’s Analyst Ratings
The car business isn’t carrying the stock
Tesla’s normalized earnings per share have nearly halved in two years, and analysts don’t expect them back above the 2023 level until 2028.
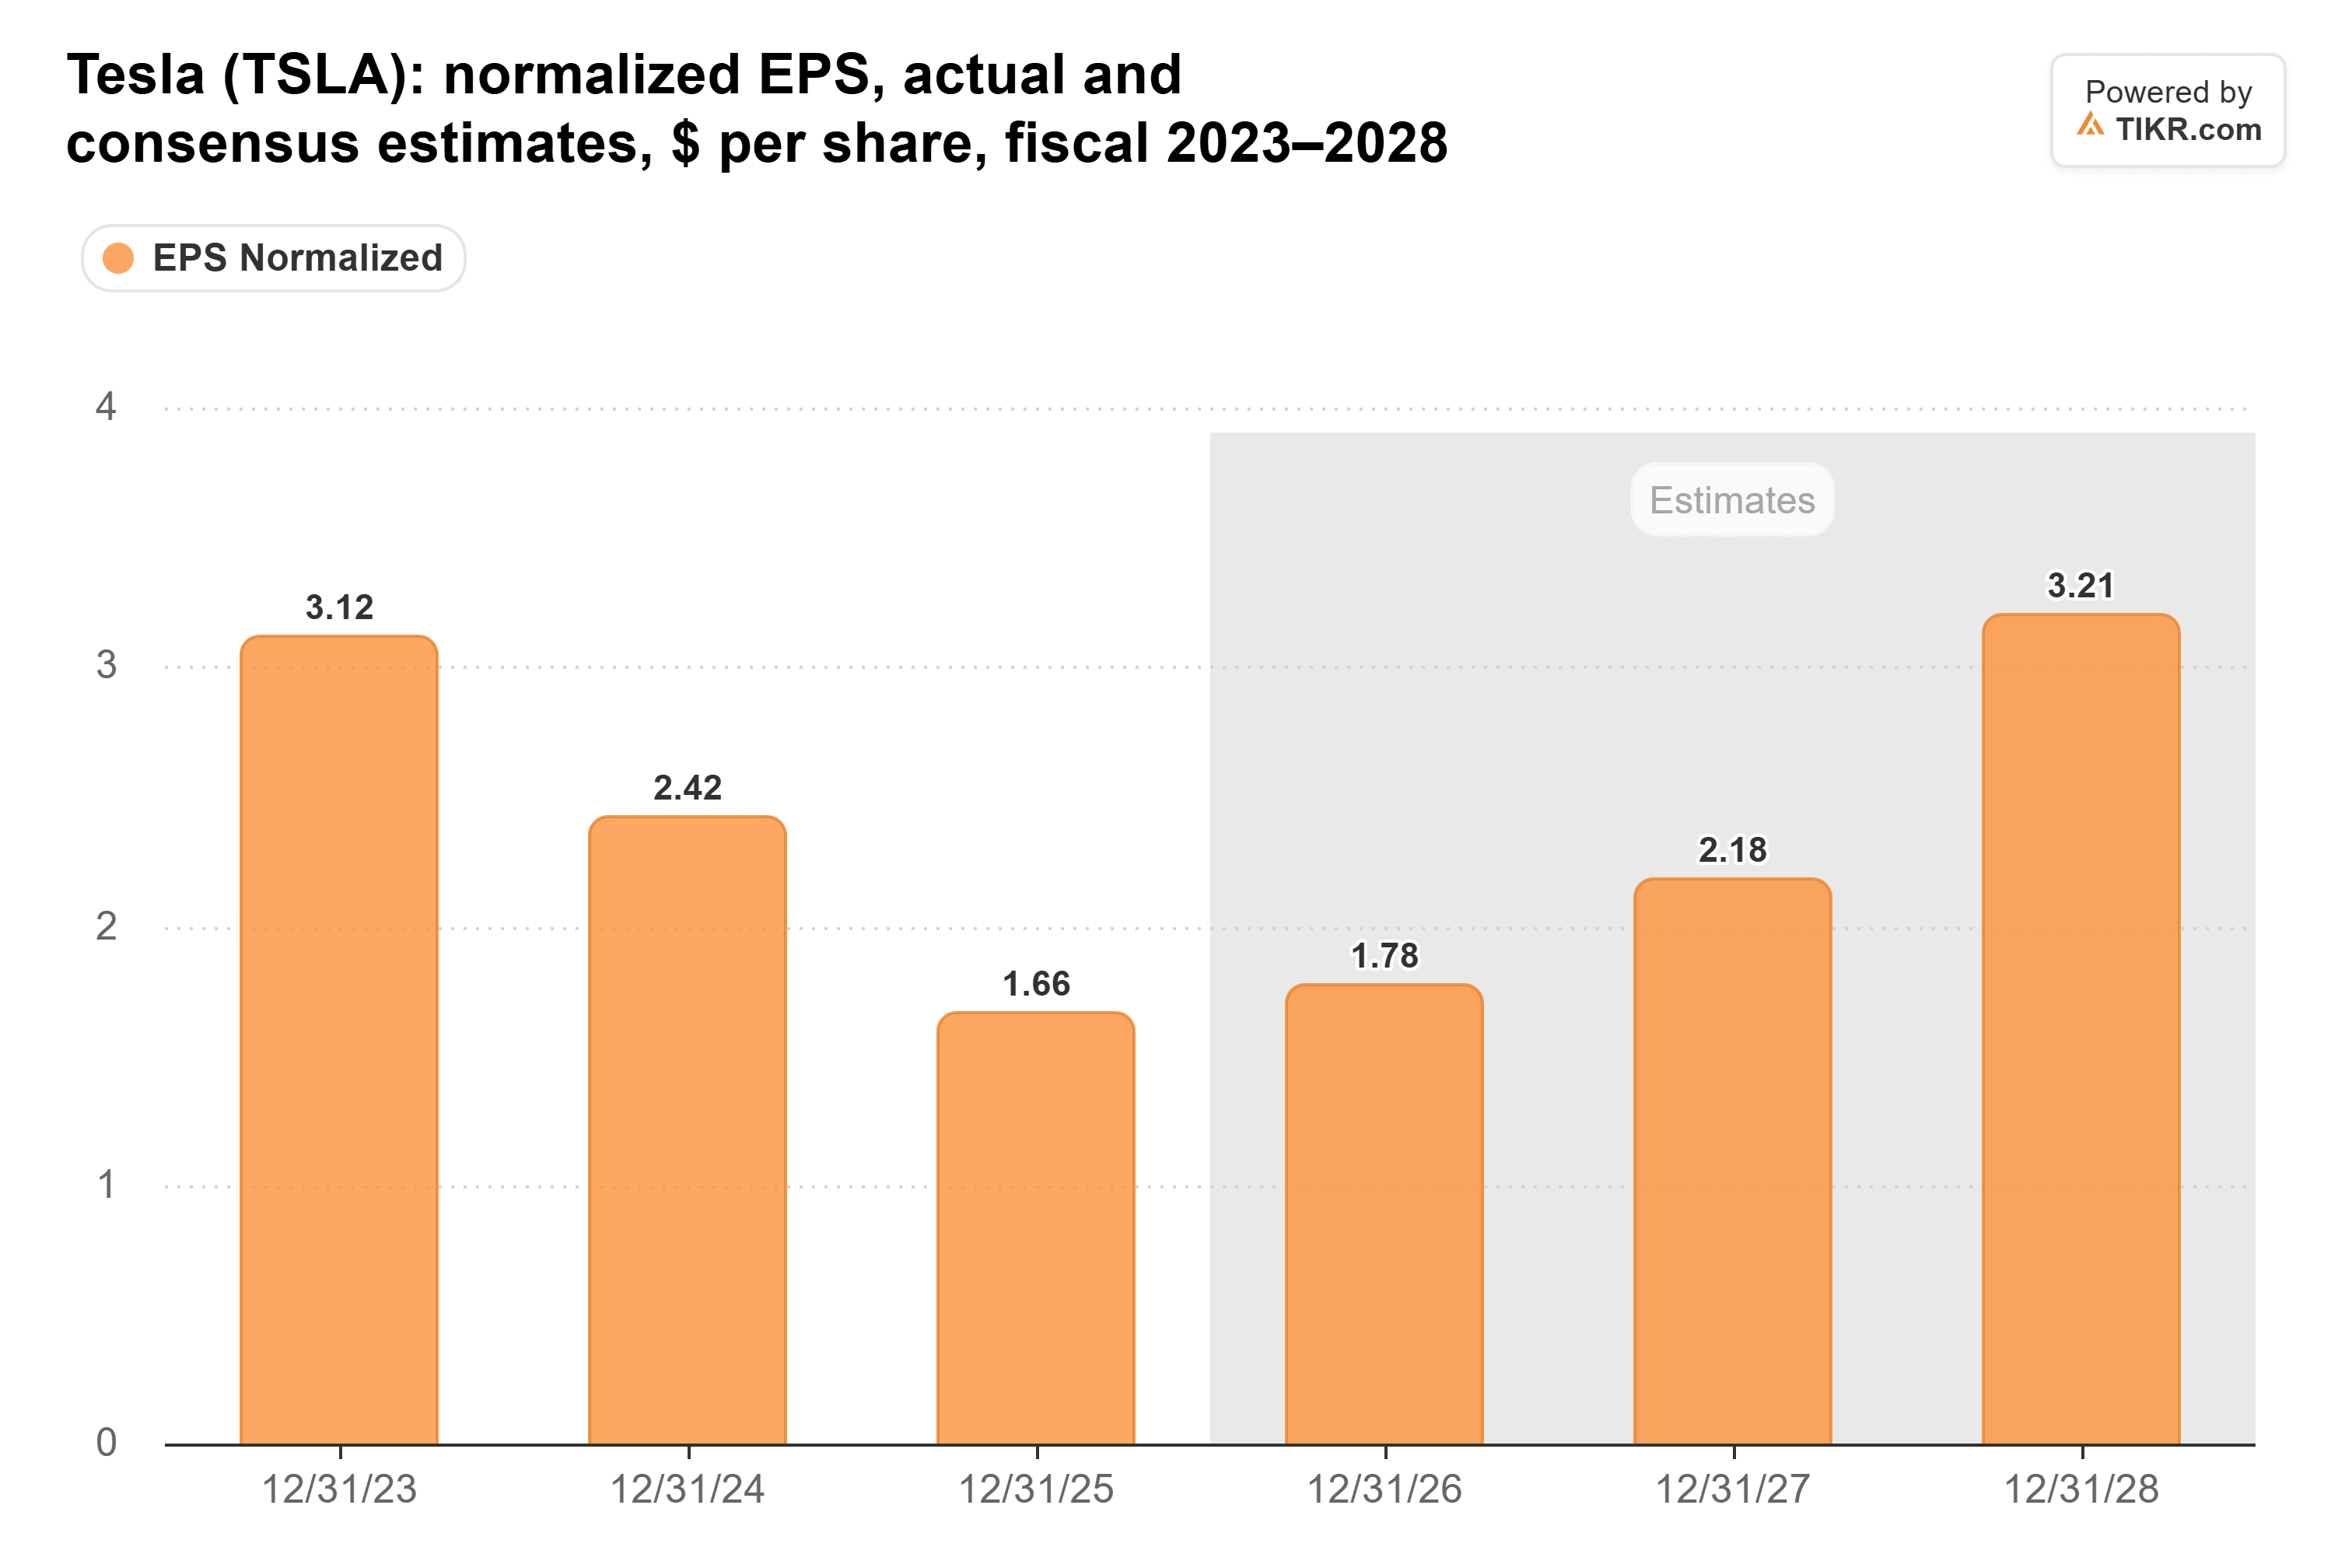
There’s very little profit left. Tesla’s GAAP operating margin was 2.6% in the third quarter, down from 5.8% a year earlier, as R&D spending rose 69%.
Yet the stock traded at about 175x forward earnings at Friday’s close, well above its three-year average of 135x.
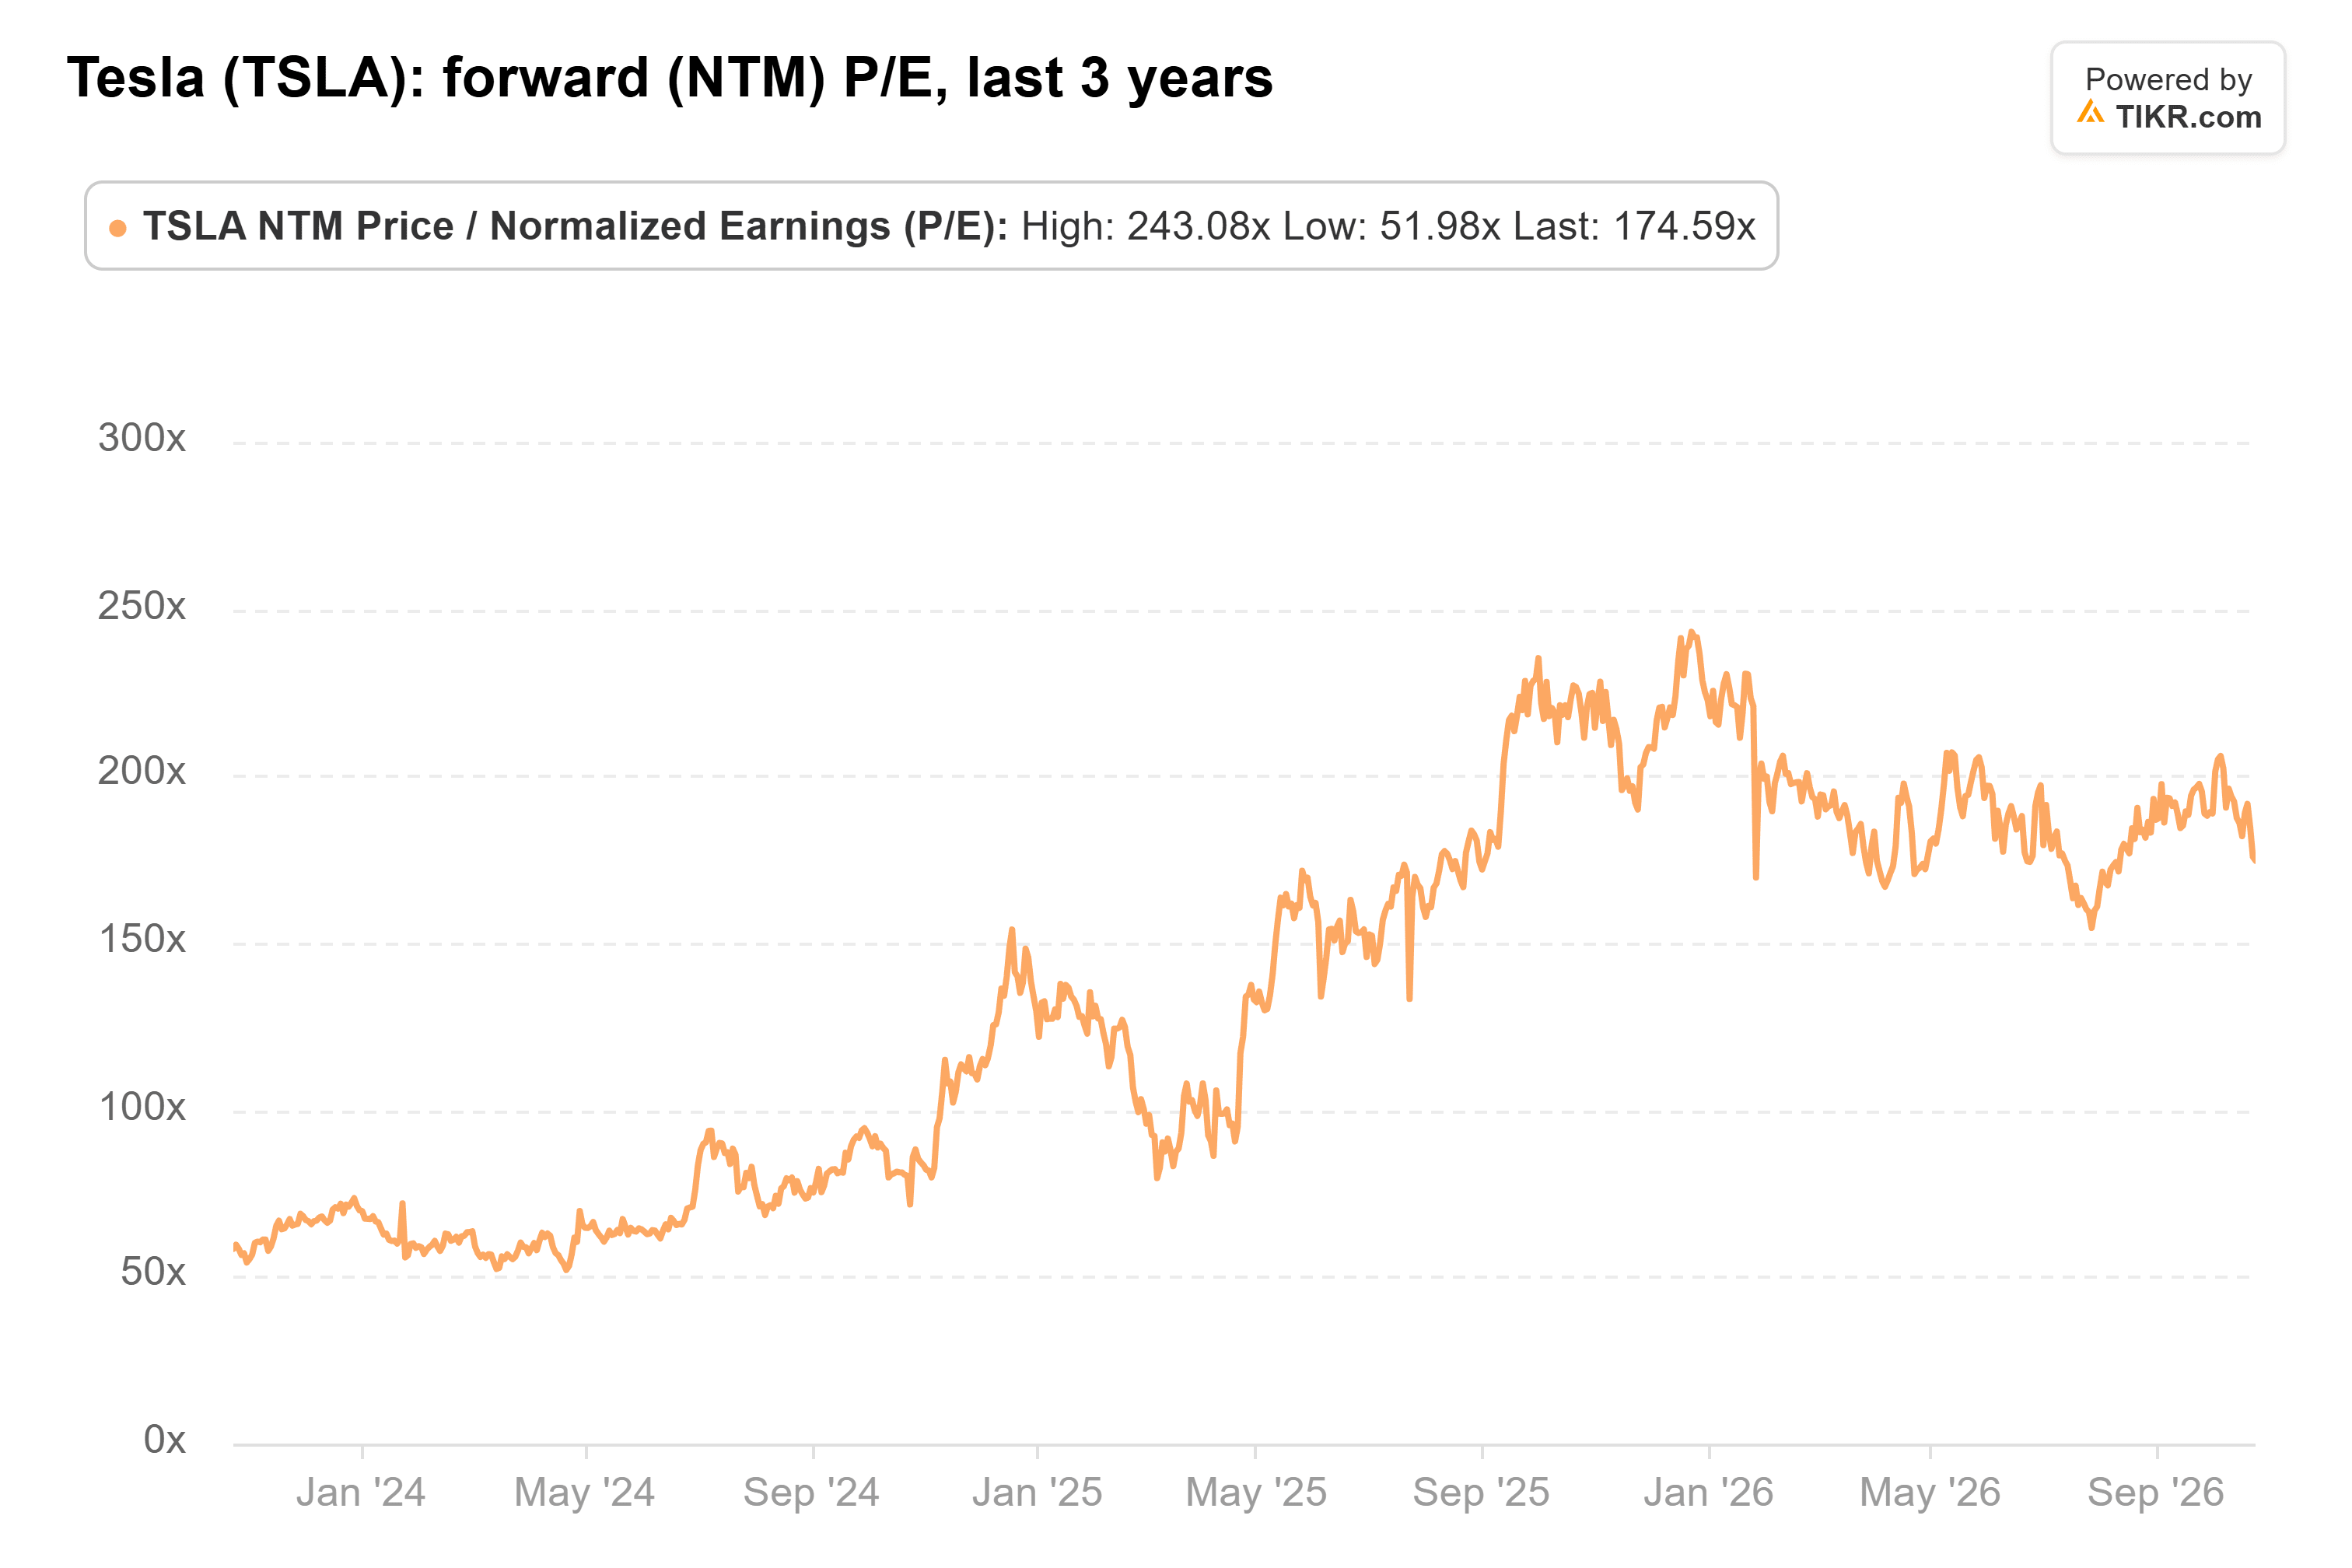
(And that was before Monday’s jump.)
That premium rests on Robotaxi, Optimus and, more and more, the merger. Barclays more or less said so: Levy expects the deal to add upside through a takeover premium and to limit the downside, since investors are unlikely to short the stock before an announcement.
SpaceX holders would pay for the transplant
Galloway’s co-host, Ed Elson, put numbers on the swap: “Tesla’s trading 14 times sales. SpaceX is trading at 87 times sales.” He calls the merger “multiple laundering”: Tesla’s slowing car business gets folded into SpaceX’s bigger story.
SpaceX has earned its richer multiple, too. Its third-quarter revenue rose 161% to $14.6 billion.
Tesla looks like the bargain on sales, but at a 2.6% operating margin, very little of that revenue turns into profit. On forward earnings, SpaceX trades at about 52x, against Tesla’s 175x.
So in an all-stock deal, SpaceX holders would hand over shares priced at 52x earnings for a company priced at 175x… plus whatever premium the committees agree. JPMorgan expects a premium of 30% to 35% in a SpaceX-led all-stock deal.
That premium is the organ, and SpaceX holders are the ones giving it.
Robotaxi could reverse the transplant
If Robotaxi and Optimus pay off, the deal looks very different: SpaceX holders would get those businesses at a price set while Tesla earned $1.66 a share.
There are early signs. Cumulative unsupervised Robotaxi miles grew eightfold in the third quarter, to nearly 2 million, and Barclays says it has seen “a sharp inflection in Robotaxi miles driven” in recent weeks. The bank also expects Tesla’s car business to grow this year after two years of declines. On Tesla’s third-quarter call, Musk said Robotaxi revenue should be noticeable by the second quarter of 2027.
But Musk’s autonomy timelines tend to slip. In January, he expected driverless rides in “dozens of major cities” by the end of 2026. In October, management cited six. And analysts aren’t counting on Robotaxi earnings yet either: their 2028 EPS estimate of $3.21 is barely above 2023’s $3.12.
Galloway has the diagnosis right
My take: on today’s numbers, Galloway is right, and Tesla holders come out ahead. If I owned SpaceX, I’d want a small premium and Robotaxi revenue in Tesla’s results before signing off. And with Musk holding about 82% of SpaceX’s voting power, according to Barclays, SpaceX’s other holders won’t have much say.
Of course, there are no terms yet. On Tesla’s side, a deal needs a majority of all outstanding shares, a bar Barclays called a “high hurdle” and Musk himself acknowledged on SpaceX’s call. The first terms the special committees disclose will show how much SpaceX holders end up giving.
So what is Tesla stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Tesla could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!



