Key Takeaways
- Dell stock is up 299% in 2026, with sharp rallies after two earnings reports that brought record AI server orders and a $95 billion backlog.
- The business has earned much of the run: Dell raised its full-year revenue outlook to $192 billion, up 69%.
- Barclays argues that higher memory prices drive much of Dell’s growth, but Super Micro’s much stronger preliminary quarter suggests AI server demand is holding.
- At 17x forward earnings, Dell is worth buying more only if its late-November report shows free cash flow catching up with profit.
Dell Technologies (DELL) stock is up 299% in 2026 through Tuesday’s close, and the business has done most of the lifting.
It’s also 16% below its Sept. 18 high, after a downgrade questioned what’s really behind that growth. So do you take profits here, or buy more?
Two Reports Built a $95 Billion Backlog
Dell’s May 28 first-quarter report started it. Revenue jumped 88% to $43.8 billion, and management lifted its full-year revenue outlook to $165 billion to $169 billion, from $138 billion to $142 billion in February.
The Sept. 1 second-quarter report topped that:
- Revenue up 58% to a record $47.0 billion
- A record $60.9 billion of AI server orders
- A record $95 billion AI backlog
- Full-year revenue guidance raised by $25 billion to $192 billion, with AI server revenue now expected at $74 billion (up from $60 billion)
As CFO David Kennedy put it at Citi’s conference on Sept. 10, “Demand was faster than the P&L.”
TIKR Tracks 29 Analysts on Dell Technologies. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Dell Technologies, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Dell Technologies’ Analyst Ratings
Barclays Says It’s Memory Prices
Wall Street now expects revenue to climb from $113.5 billion in the year ended January 2026 to $193 billion this fiscal year and $231 billion the year after.
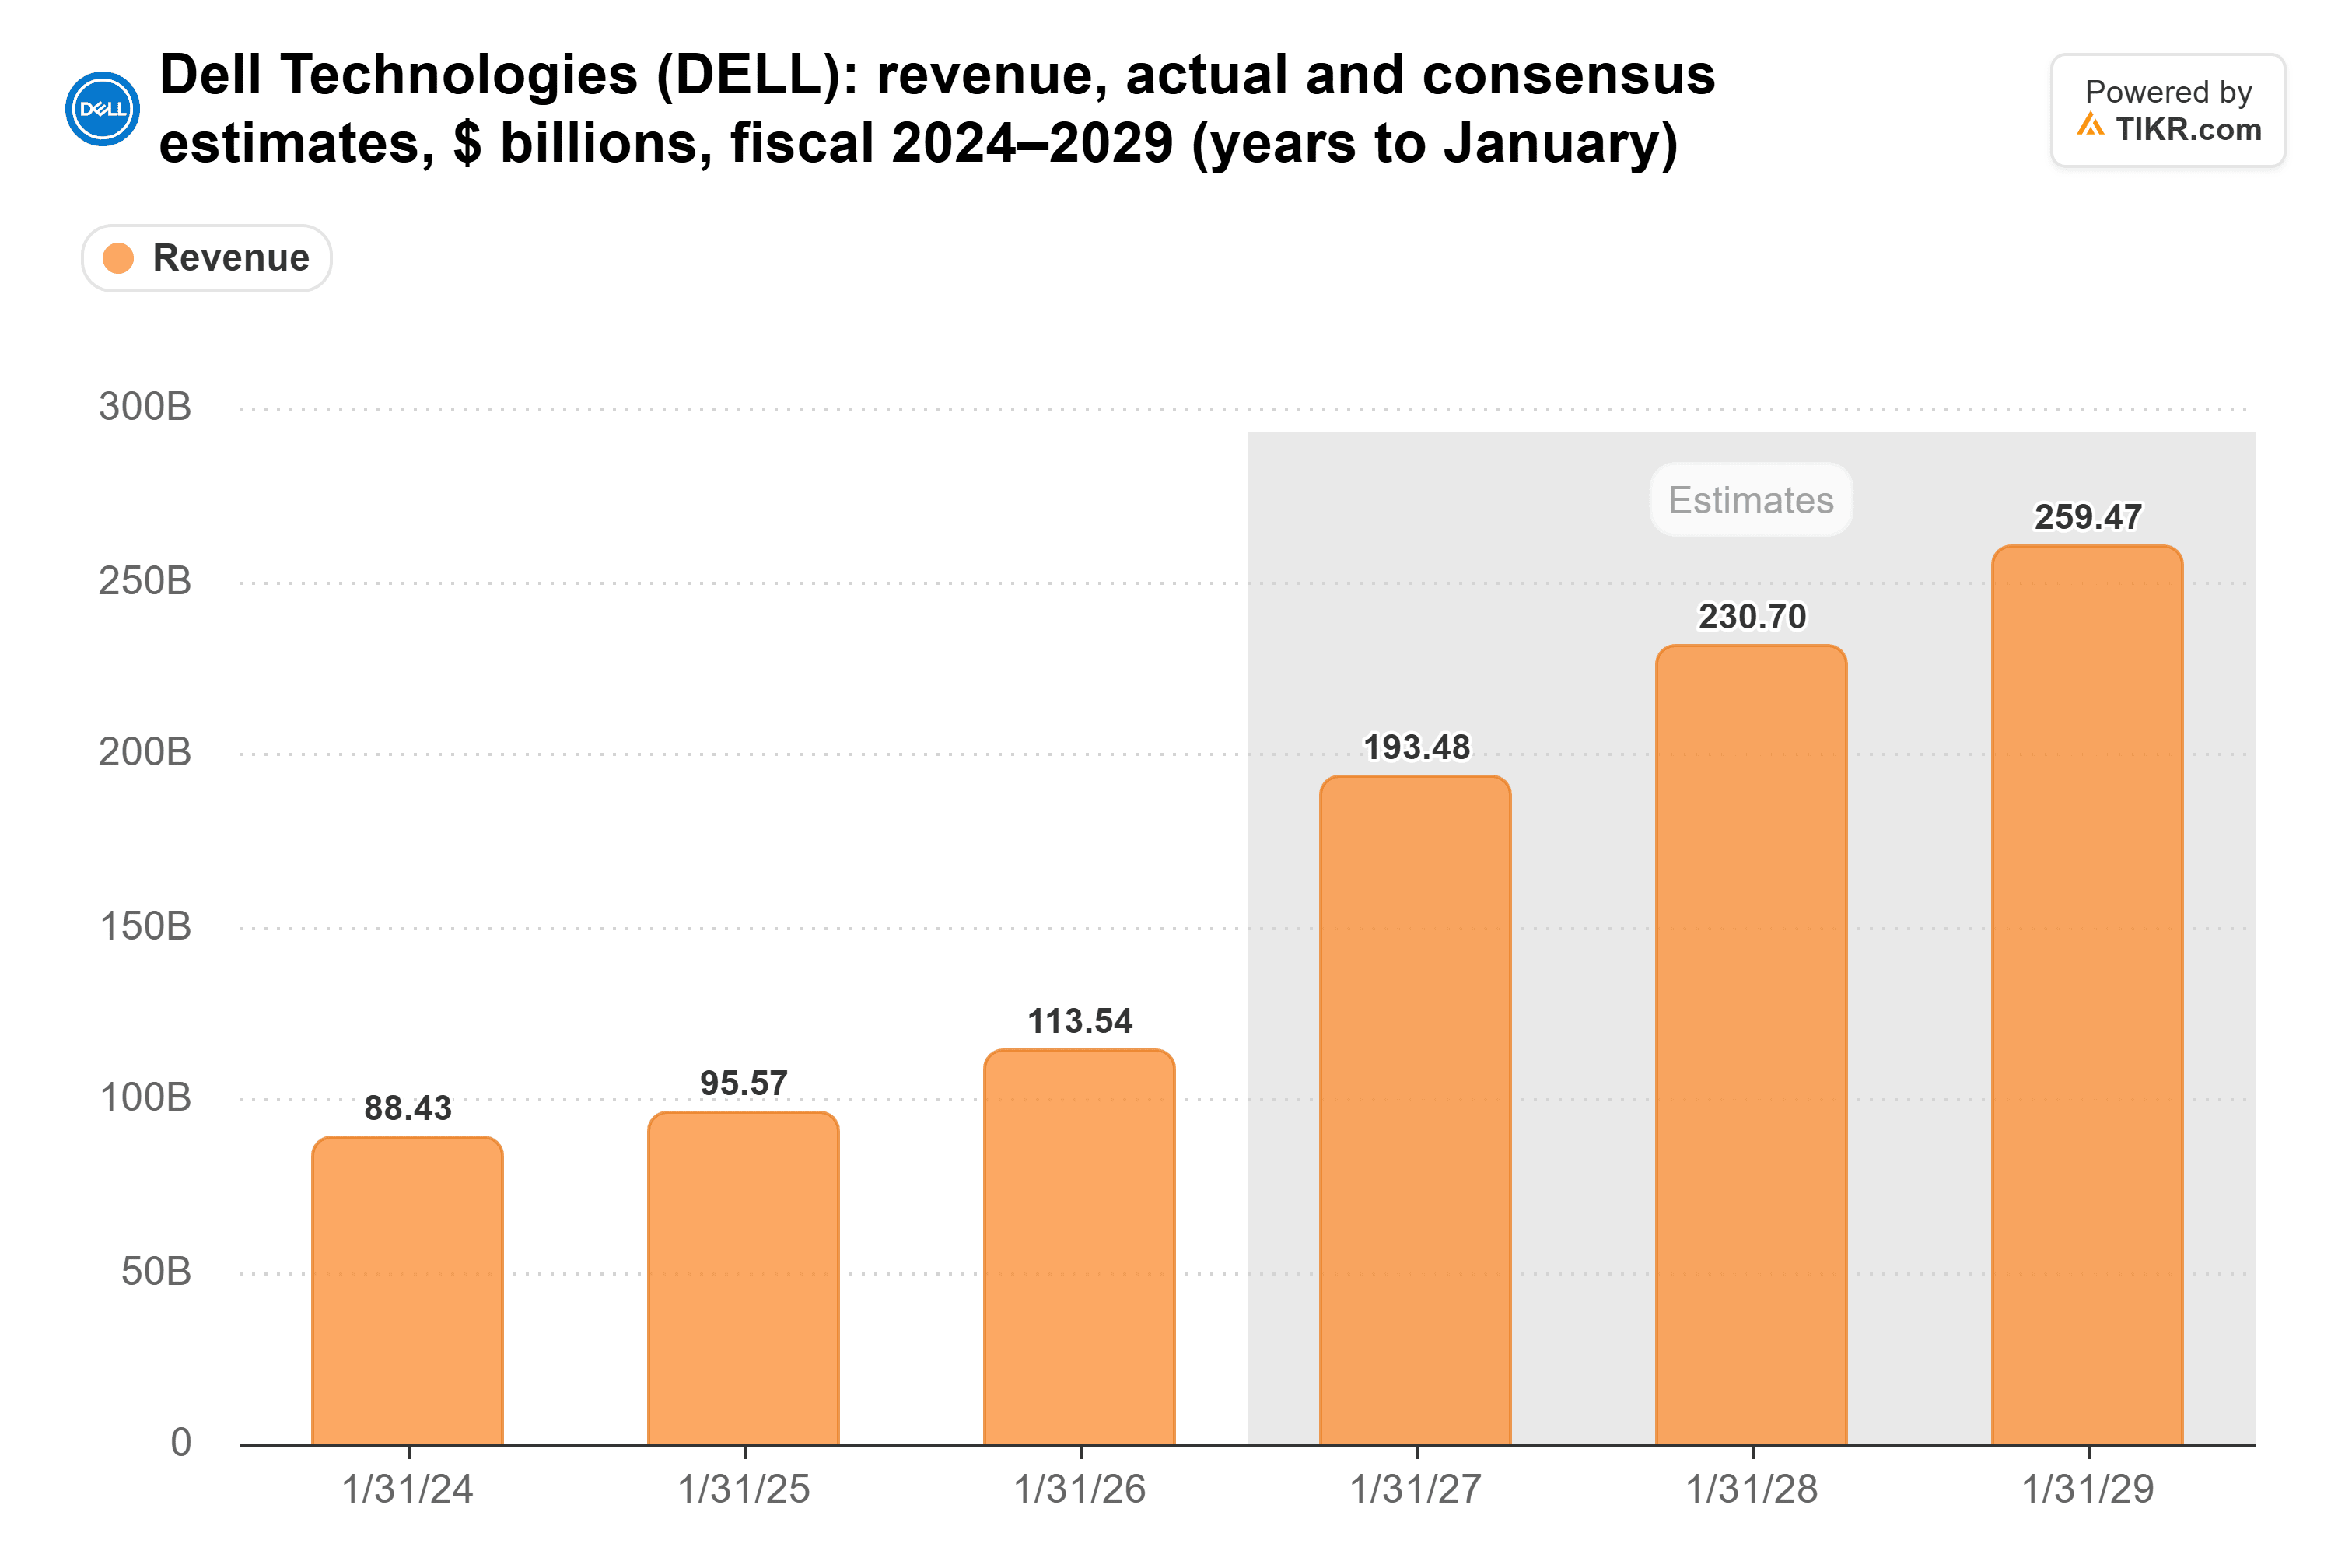
Barclays thinks a lot of that is memory. Analyst Tim Long downgraded Dell to Equal Weight on Oct. 14 and lowered his target to $574 (from $603). His case: there’s no “meaningful AI inflection” in enterprise spending yet, and much of Dell’s growth comes from passing higher memory costs on to customers. If those prices level off, Dell’s sales could too.
Dell concedes part of that. Traditional server and networking revenue rose 122% to $10.5 billion last quarter, and COO Jeff Clarke said on the second-quarter call, “There’s a notion of inflation inside our growth.”
Kennedy’s answer is density: one new server can replace five or six older ones, and each carries far more memory and processor cores.
On Oct. 20, rival Super Micro Computer (SMCI), up 20% in 2026, said its fiscal first quarter likely brought in $18.5 billion to $19.5 billion of revenue, well above the $14.5 billion to $15.5 billion it had forecast.
Cash Has to Show Up in November
Cash is the weak spot. Free cash flow fell 47% to $986 million in the second quarter (Dell’s adjusted measure came to $8.1 billion). In the first half, net income rose to $7.6 billion from $2.1 billion, but free cash flow held flat at $4.1 billion, with customer financing tying up $6.4 billion.
Analysts expect about $12 billion of free cash flow for the full year, so Dell needs roughly $8 billion in the second half.
Dell is expected to report fiscal third-quarter results after the close on Nov. 24. It guided to $49.0 billion of revenue and $6.50 of adjusted EPS, a step down from the second quarter’s $7.04, and consensus sits slightly higher at $49.2 billion and $6.56.
Dell Stock Is a Buy at 17x, If the Cash Follows
Dell trades at 17x forward earnings, down from a peak of 26x in August but still above its five-year average of 12x.

Management guides to $25.50 of adjusted EPS this fiscal year, up 148%, and analysts expect $30.26 of normalized EPS the year after. The $595 consensus target sits 19% above Tuesday’s close.
I’d buy more, but not blindly. The backlog, the raised guidance and Super Micro’s numbers all say AI server demand is real, and 17x is a fair price for earnings growing this fast. What isn’t proven yet is the cash.
Memory is the other risk. Michael Dell told CNBC on Oct. 13 that the shortage could last about four years, while Barclays expects growth to slow as prices normalize. If the third quarter brings another free cash flow figure under $1 billion, the cash problem stops looking temporary, and I’d stop adding.
So what is Dell stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Dell could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!