


Key Takeaways
- Box beat Q2 FY27 estimates on revenue, billings, and RPO, raised full year revenue guidance to roughly $1.29 billion, and lifted net retention to 106%.
- BOX now trades at 21.5x NTM normalized earnings, above its three year mean of 19.35x but well below the ~30x peak it hit in mid-2025, arguing against a “stock is overheated” read.
- The Street’s mean price target hit a record $38.71 on September 17, and the stock’s implied discount to that target (about 12%) is actually smaller than the discount investors were pricing for most of the past year.
- Free cash flow margin improved sharply year over year in the seasonally weakest quarter (22.0% versus 15.0%), even as management guided full year gross margin lower on AI infrastructure costs.
See Box’s full NTM valuation history on TIKR for free →
Box’s Q2 Beat Confirms Enterprise Advanced Is Working
Box’s (BOX) fifth straight quarter of accelerating constant currency growth was not a fluke. Q2 FY27 revenue hit $321.1 million, up 9% year over year, while billings jumped 17% and remaining performance obligations grew 15% to $1.7 billion.
Net retention rose to 106%, above the company’s own 105% guidance and up from 103% a year earlier. Management credits nearly all of it to Enterprise Advanced, the premium tier that carries a 30% to 40% price per seat uplift and, per CFO Dylan Smith, drives stronger net retention within that cohort than the company average. Box raised full year revenue guidance by $10 million to roughly $1.29 billion on the back of this momentum, and the qualitative evidence, wall to wall wins at a multinational bank and a federal agency, an insurance provider modernizing over 100 terabytes of content, backs up the acceleration rather than just describing it.
BOX Stock’s Re-Rating Looks Earned, Not Excessive
This is where the numbers complicate the simple “Wall Street is way ahead of the stock” story.
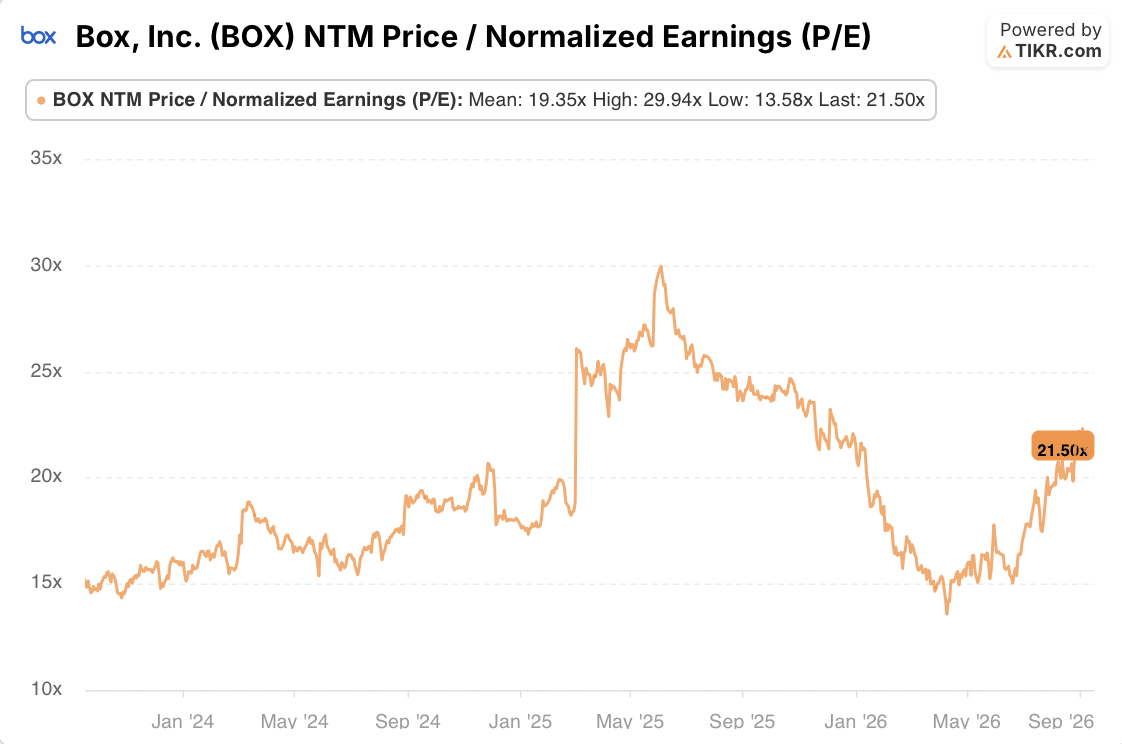
BOX’s NTM price to normalized earnings multiple sits at 21.5x today, above its three year mean of 19.35x but nowhere near the roughly 30x high it touched in mid-2025, and well off the 13.58x low it hit around May 2026 when the stock had cratered to the mid-$20s. That is a stock recovering toward its historical middle, not one trading at an extreme.
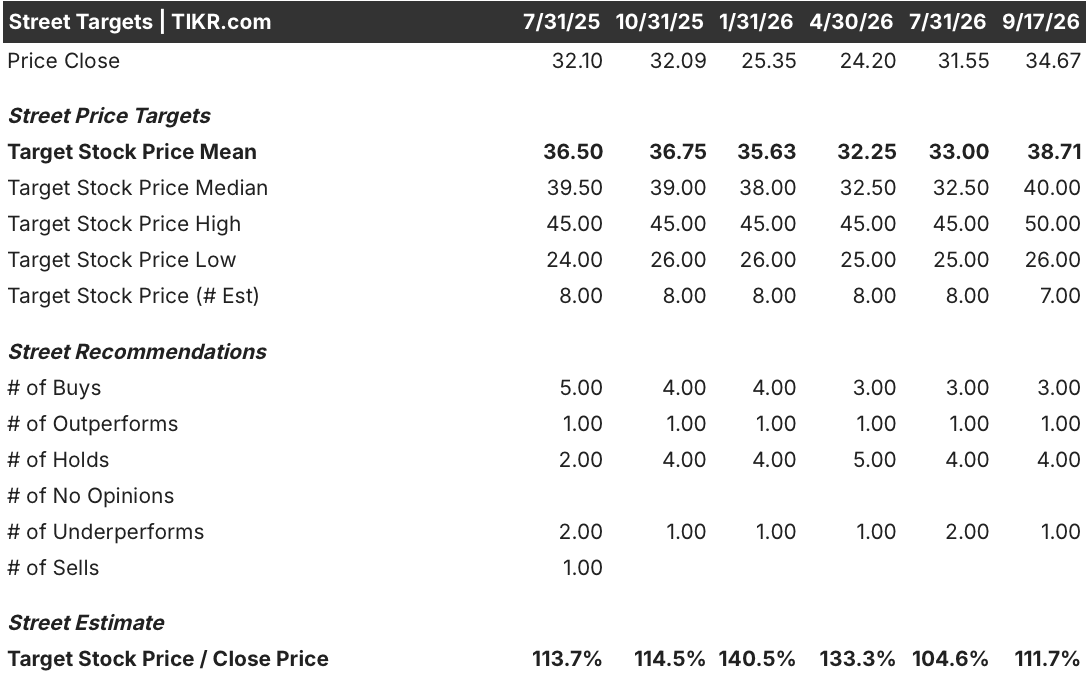
The Street Analysts Targets tells a similar story. The mean target of $38.71 as of September 17 is the highest in the two year window shown, topping the prior peaks of $36.50 and $36.75 set back when the stock traded in the low $30s. But the premium that target implies over the actual stock price, about 112% of the close, is smaller than the 133% to 140% premiums seen in early to mid 2026, when the stock had fallen into the $24 to $25 range. In other words, targets have gone up, but so has the stock, and the gap between the two has actually narrowed from where it stood for most of the past year.
Analyst sentiment has also improved on the margins: sell ratings, present as recently as mid-2025, have disappeared from the table, even as the total number of analysts covering the name ticked down from eight to seven.
Track how BOX’s price target has moved against its own multiple on TIKR for free →
Box’s Cash Generation Is Outpacing Its Own Margin Guidance
The tension in Box’s story isn’t valuation, it’s the gap between gross margin guidance and what cash flow is actually showing. Management guided full year gross margin to about 80.5%, with further Q4 softening to roughly 80%, and CFO Dylan Smith said at Citi’s TMT conference that pressure from AI compute costs and constrained public cloud capacity should persist “at least probably through next year.”
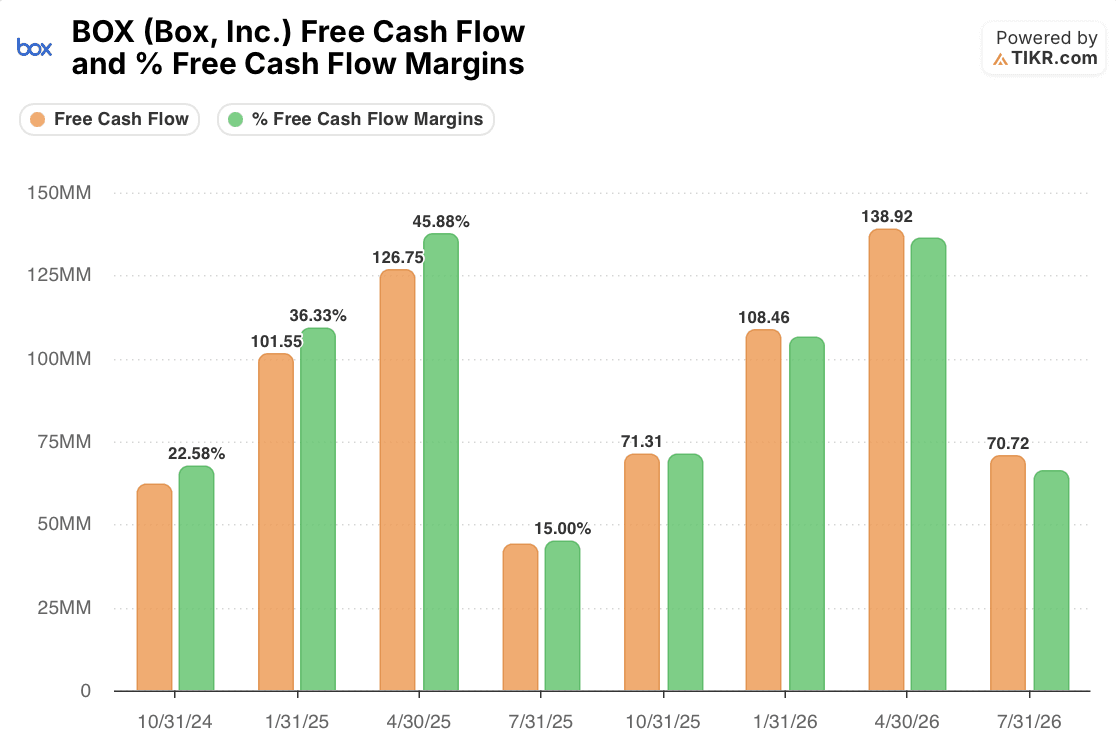
Free cash flow tells a more constructive story. Box’s fiscal second quarter is consistently its seasonally weakest for cash generation, FCF margin fell to just 15.0% in the July 2025 quarter and 22.6% in October 2024, well below the 45%-plus margins Box posts in its April quarters. Against that seasonal pattern, the July 2026 quarter’s $70.72 million in free cash flow and 22.0% margin represents real year over year improvement from the $44.10 million and 15.0% margin posted a year earlier, even as gross margin guidance moved the other direction. That combination, softer gross margin guidance alongside stronger free cash flow conversion, suggests the AI cost pressure is showing up in the income statement before it shows up in cash, which is worth watching rather than dismissing. It also sits alongside a guided billings deceleration, from 17% growth in Q2 to roughly 9% in Q3, that management attributes to comparison timing rather than softening demand.
Q3 Is the Test for Whether Box’s Re-Rating Holds
The evidence supports a company whose growth reacceleration is real and whose valuation has recovered toward, not beyond, its historical norm, with free cash flow actually running ahead of the cautious gross margin guidance rather than behind it. What isn’t yet resolved is whether the guided Q3 billings slowdown is genuinely just lumpy comps, as management insists, or the first sign that the Enterprise Advanced upgrade cycle is normalizing after two years of acceleration. A Q3 print that reaccelerates billings growth back above the 9% floor, or gross margin that stabilizes rather than continuing to slip toward 80%, would support the case that the Street’s now record high price targets are catching up to a business that has earned them. A miss on either front would suggest the recent multiple recovery got a little ahead of the fundamentals after all.
Compare Box’s next quarterly guidance against consensus estimates on TIKR for free →
Should You Invest in Box, Inc.?
The only way to really know is to look at the numbers yourself. TIKR gives you free access to the same institutional-quality financial data that professional analysts use to answer exactly that question.
Pull up BOX stock and you’ll see years of historical financials, what Wall Street analysts expect for revenue and earnings in the quarters ahead, how valuation multiples have moved over time, and whether price targets are trending up or down.
You can build a free watchlist to track Box, Inc. alongside every other stock on your radar. No credit card required. Just the data you need to decide for yourself.
Access Professional Tools to Analyze BOX stock on TIKR for Free →
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!


