Key Takeaways
- Vistra stock has fallen 31% over the last year amid investor concern about ERCOT pricing and a Texas audit of data center grid requests.
- Q2 adjusted EBITDA jumped 31% YoY to $1.77B, even though revenue of $4.02B missed the ~$5.57B consensus.
- The Street holds 15 buys, 4 outperforms, 1 underperform, and 1 sell, with a $218 mean target implying ~58% upside from $138.
- TIKR’s model targets $199 by December 2030, a 44% total return.
Why Vistra Stock Fell 31% While Its Adjusted EBITDA Kept Growing
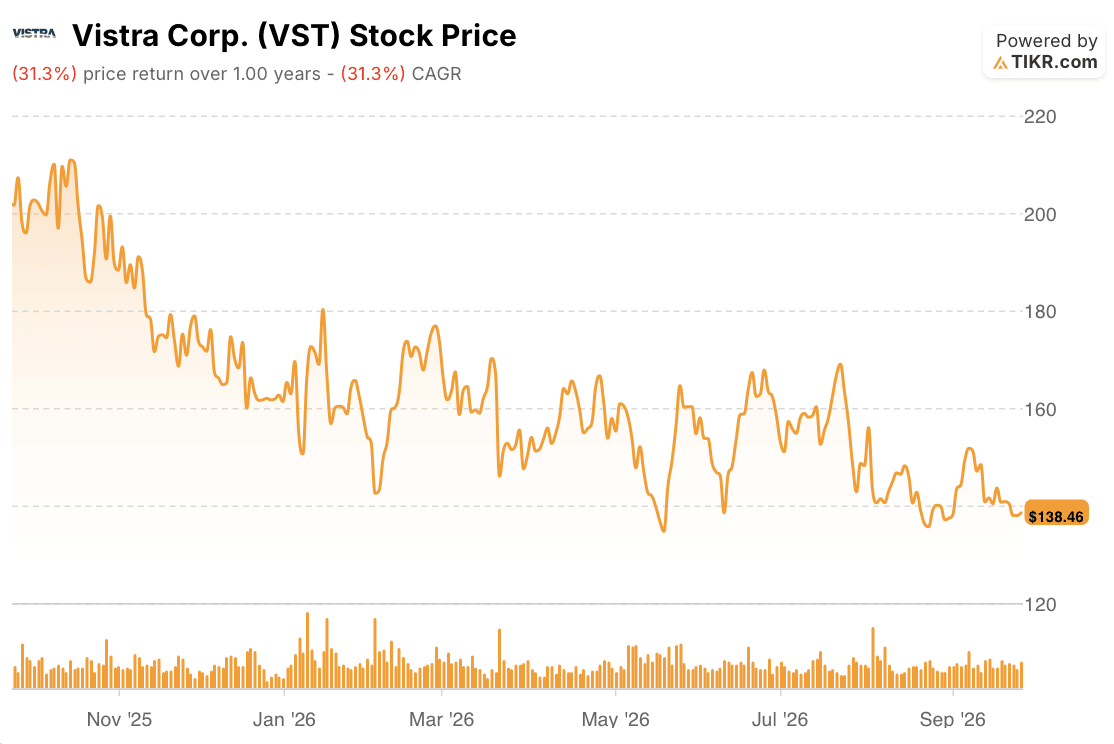
Vistra (VST) stock has fallen 31% over the last year, closing at $138 on September 25, 2026. The decline coincided with investor concern about ERCOT pricing and Texas data center demand, even as Vistra’s Q2 adjusted EBITDA increased.
ERCOT pricing has remained too low, in management’s view, to support new generation builds. CEO Jim Burke put it plainly on the August 7 Q2 earnings call: “Year-to-date, ERCOT wholesale prices have been $30 a megawatt hour. They were $30 a megawatt hour last year. $30 is not going to get new stuff built.”
Texas then added policy uncertainty. Governor Abbott ordered an audit of planned data centers seeking grid connections, and ERCOT postponed the Batch Zero transmission-planning study. Vistra said it does not currently expect its Comanche Peak project to be affected and still targets energization at the end of 2027.
The Q2 print gave bears more to work with. Net income slipped 6.7% to $305 million, and that figure included a $472 million unrealized hedge loss expected to settle in future years. CFO Kris Moldovan said Vistra’s 2027 adjusted EBITDA midpoint opportunity is trending toward the low end of its $7.4 billion to $7.8 billion range. Vistra calls that figure an opportunity estimate, not guidance.
Yet adjusted operating earnings kept growing. Adjusted EBITDA climbed 31% year over year, and management expects 2026 to land at or above the midpoint of its $6.8 billion to $7.6 billion guidance. On September 18, Luminant entered a 20-year agreement to supply a Texas data center project with 200 MW to 207 MW of power, subject to conditions precedent. And an investment partnership jointly owned by Burke and his spouse bought 2,200 shares on August 31 and 4,465 shares on September 1, at weighted-average prices of $135.99 and $135.25.
The share price suggests the market is more skeptical of ERCOT pricing and data center timing than management’s hedge-supported earnings outlook.
Analysts Still See 57% Upside in Vistra Stock
Vistra stock carries 15 buys, 4 outperforms, 1 underperform, and 1 sell. Separately, 19 analysts publish a price target, and their $218 mean sits 57% above the current price.
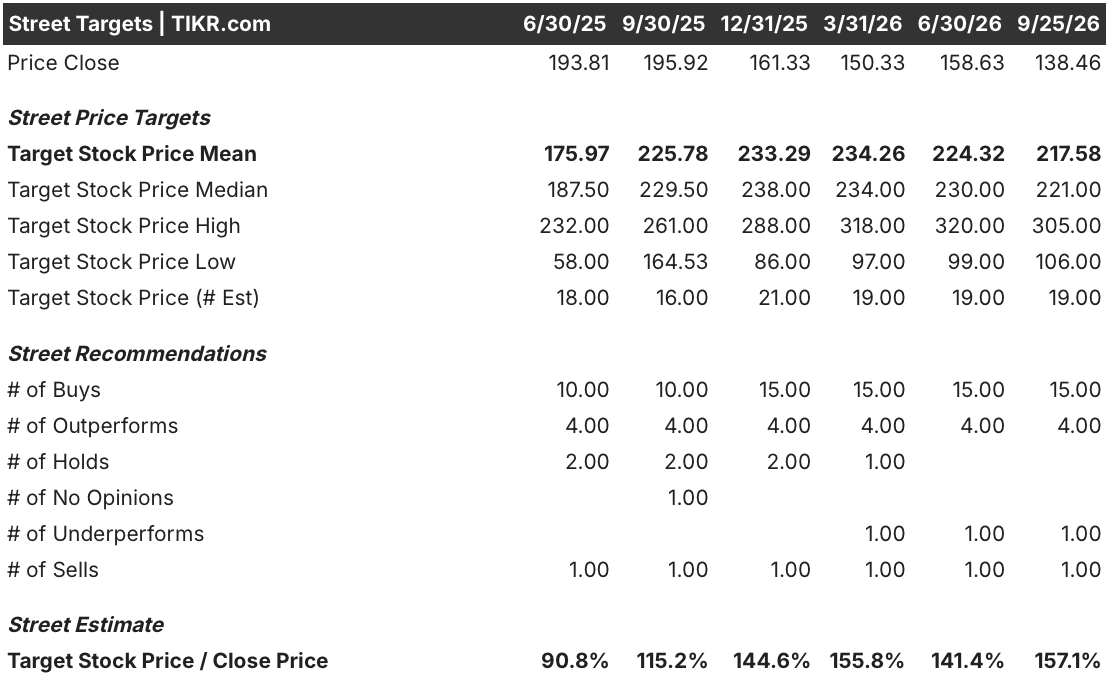
The mean target fell from $234 in March to $218 while the share price declined from $150 to $138, so the implied upside stayed broadly similar.
TIKR Values Vistra Stock at $199 by 2030, Well Above Today’s Price
TIKR’s mid-case model values Vistra at $199 by December 2030. That implies a 44% total return from the current price of $138, or 9% annualized over 4.3 years.

A 9% annual pace fits a power producer that sells at market prices and carries more price risk than a regulated utility.
The model lands below the Street’s $218 mean, yet it still sits 44% above the current price. Q2 EBITDA grew on higher realized energy and capacity prices and the Lotus acquisition, and that growth contrasts with investor concern about ERCOT’s forward curve.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!