Key Stats for Starbucks Stock
- Current Price: $100.80
- Target Price (Mid): ~$146
- Street Target: ~$110
- Potential Total Return: ~45%
- Annualized IRR: ~10% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
Starbucks (SBUX) closed at $100.80 on October 23, up 11.1% from its October 9 close of $90.75, the low point of a 16.40% drawdown. In the same stretch, Citi cut its price target to $104 from $112, Mizuho cut its target to $105 from $115 in a restaurant-wide update, and the Street mean slipped to $110.17 from $111.87 at the end of September.
The stock rose while targets fell. The fiscal fourth-quarter report, due after the close on Thursday, October 29, should show which side read the business right, and the July 29 earnings call shows where to look.

Closures and Delivery Drove Nearly Half of the Q3 Comp
Asked by Wells Fargo’s Zack Fadem what drove fiscal Q3’s 7.9% comparable sales growth, CFO Cathy Smith said “about half of it or a little bit less than half of it was due to closures, sales transfer, delivery growth.” The rest, she said, came from store performance, menu and innovation.
Sales transfer means customers of closed stores moving to nearby ones, which lifts the surviving stores’ comps even if systemwide traffic does not grow, and that lift fades once the closure is lapped. Smith said a closer look at underperforming North American coffeehouses “could result in some closures,” so the effect can recur. Delivery is real demand, and CEO Brian Niccol said the channel has yet to show any meaningful cannibalization.
That leaves roughly 4 points of the comp from store performance and menu, the part that compounds. Management guided Q4 U.S. comps to 6.5% or better, so the mix behind that number matters as much as the number itself.
Q4 Margins Lose the Tariff Refund
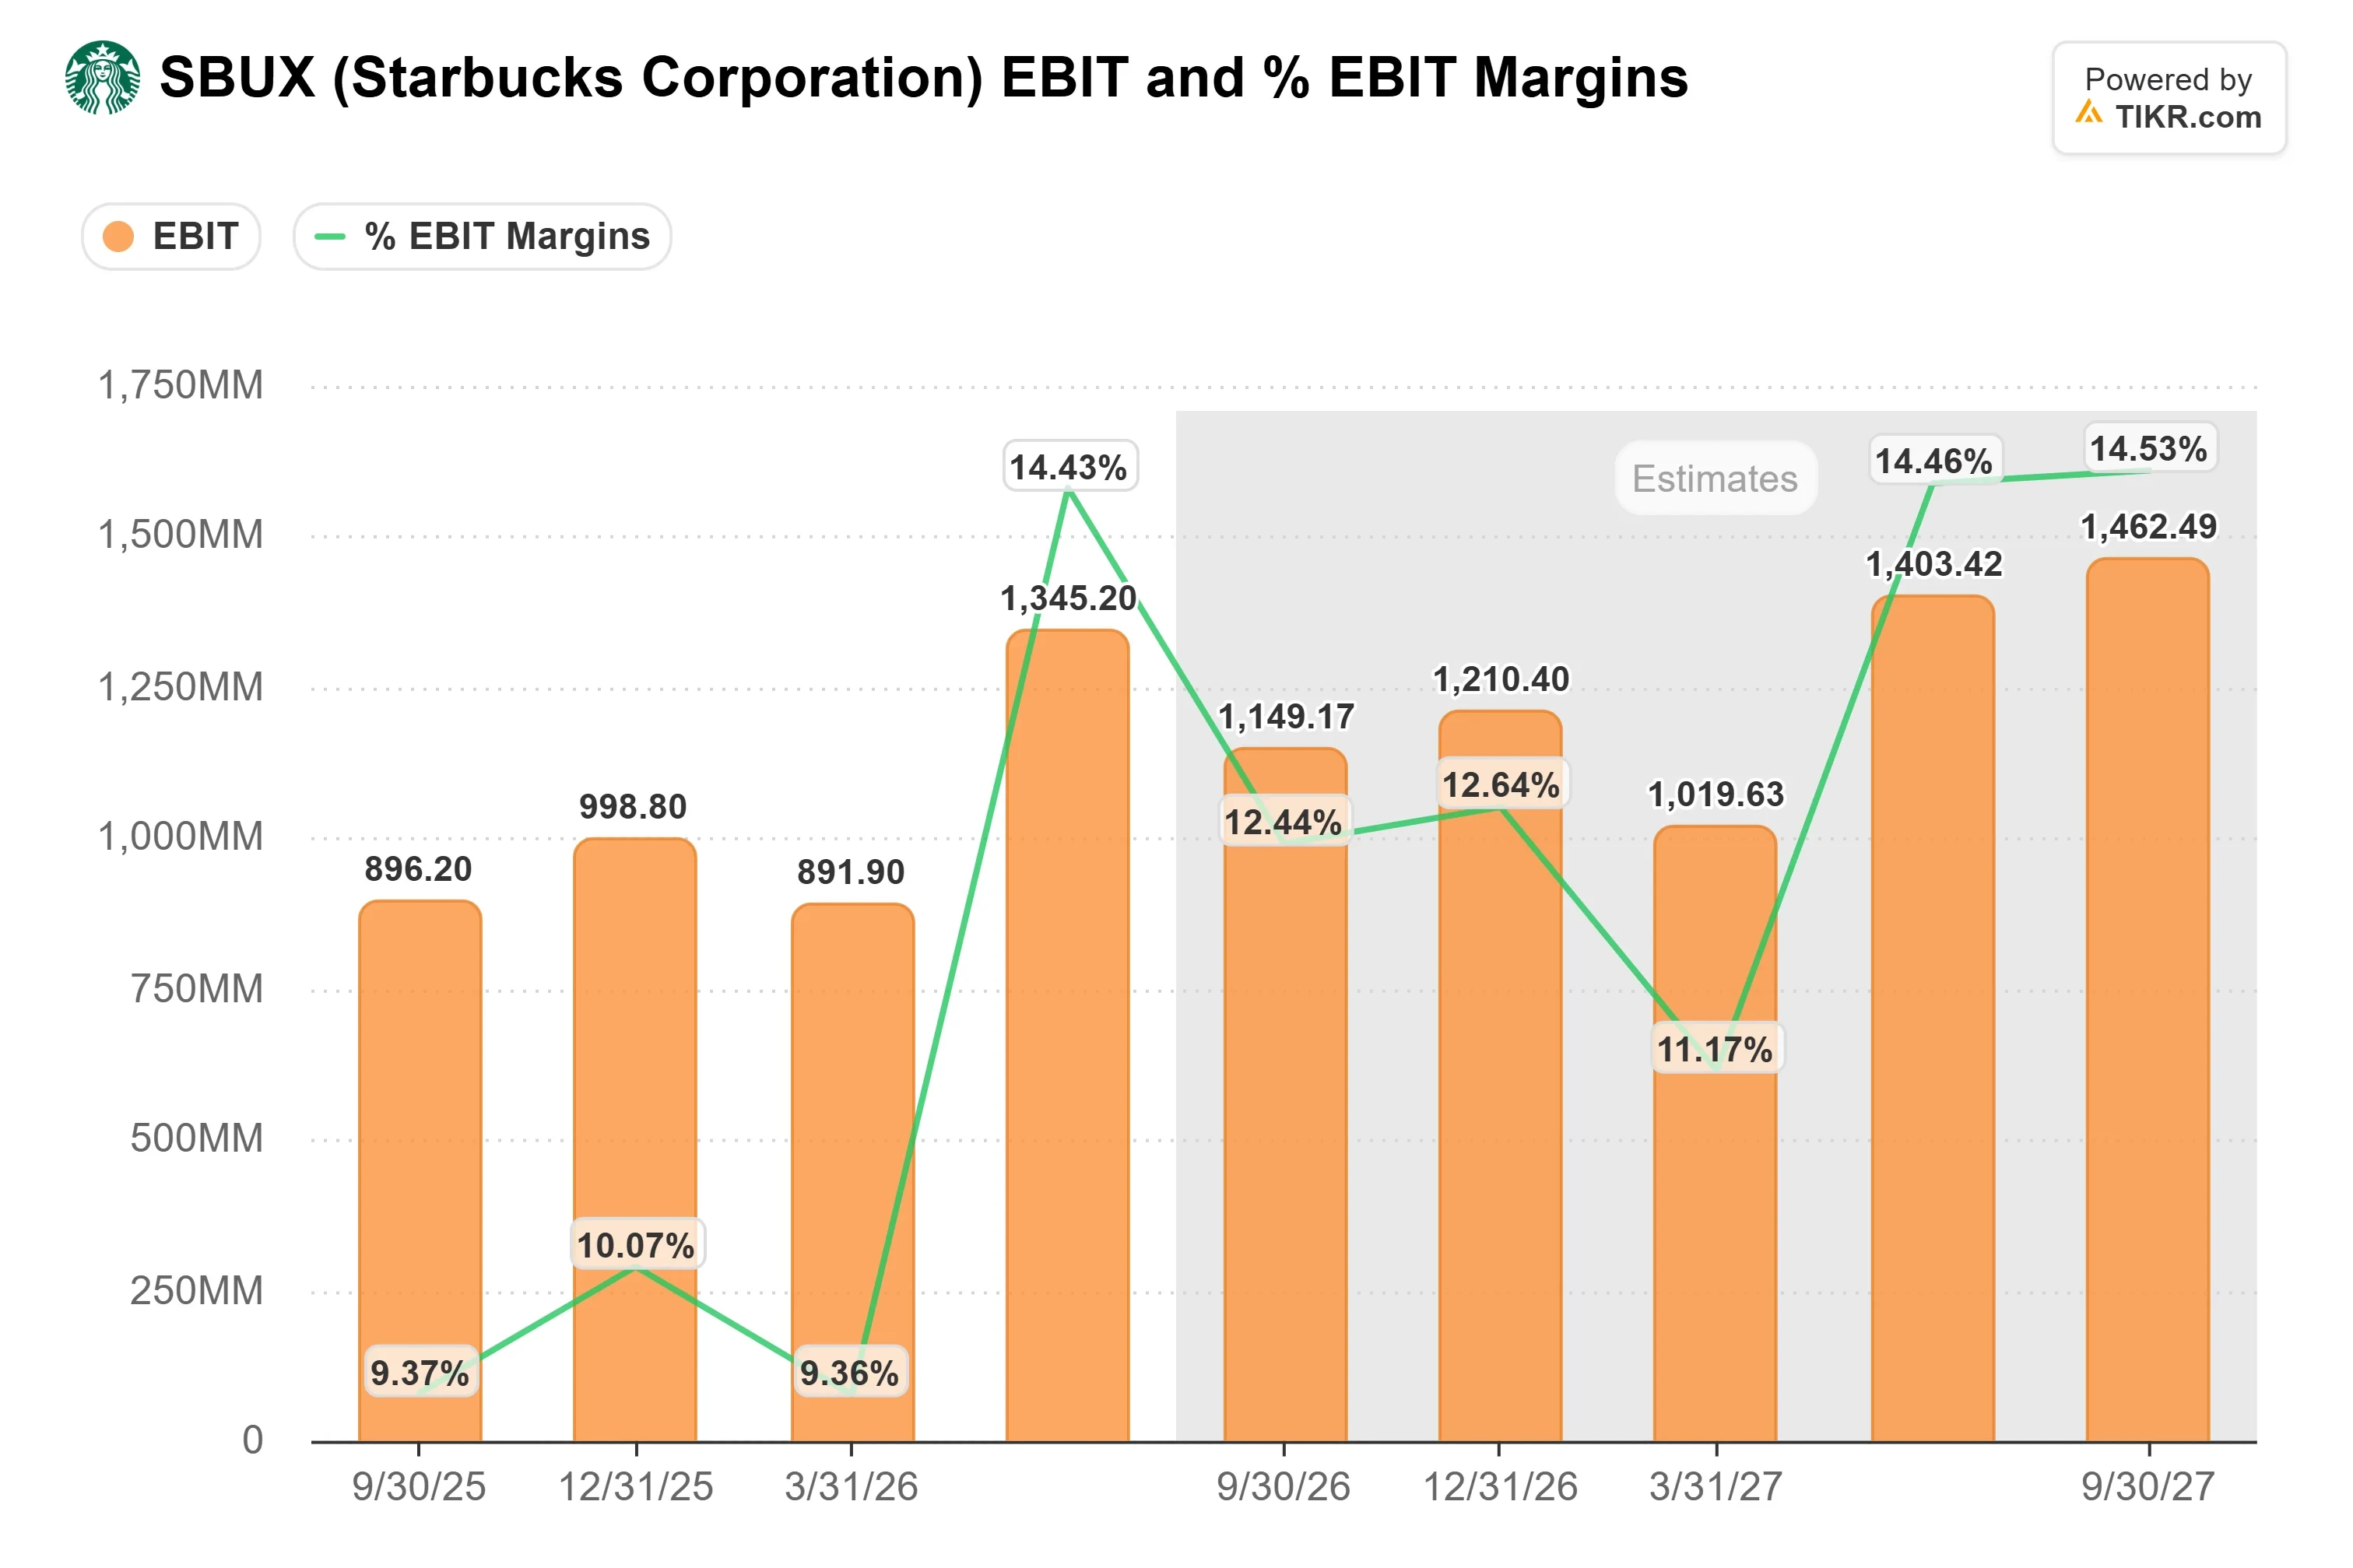
Q3 consolidated operating margin reached 14.4%, up about 430 basis points. Smith said sales leverage did most of the work, supported by cost savings, lower inflation and reciprocal tariff refunds that largely offset tariffs incurred in the first three quarters of fiscal 2026. She called the year-to-date product and distribution cost rate of 32.3%, not Q3’s 30.3%, “the better proxy for a more normalized Q3 COGS rate.”
Margins still expanded without the refunds, but by less: North America rose more than 100 basis points excluding them, against about 280 reported. Smith said Starbucks has “largely gotten the refunds we’re entitled to,” so Q4 should get little or no help from them. TIKR’s consensus EBIT and revenue estimates imply a Q4 EBIT margin of about 12.4%, down from Q3’s 14.4% but above 9.4% in a year-ago quarter that still consolidated China.
TIKR tracks 35 analysts on Starbucks. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Starbucks, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Starbucks’ Analyst Ratings
China’s Pay-to-Sit Rule Tests the Joint Venture
The China joint venture, 60% owned by Boyu Capital with Starbucks keeping 40%, began requiring a purchase to use seating on October 22. It also plans to invest more than 300 million yuan in fiscal 2027 to upgrade the in-store experience, China Daily reported. China contributed $53 million of Starbucks’ Q3 revenue, so the rule is a brand question more than a Q4 earnings one.
TIKR Advanced Model Analysis
- Current Price: $100.80
- Target Price (Mid): ~$146
- Potential Total Return: ~45%
- Annualized IRR: ~10% / year
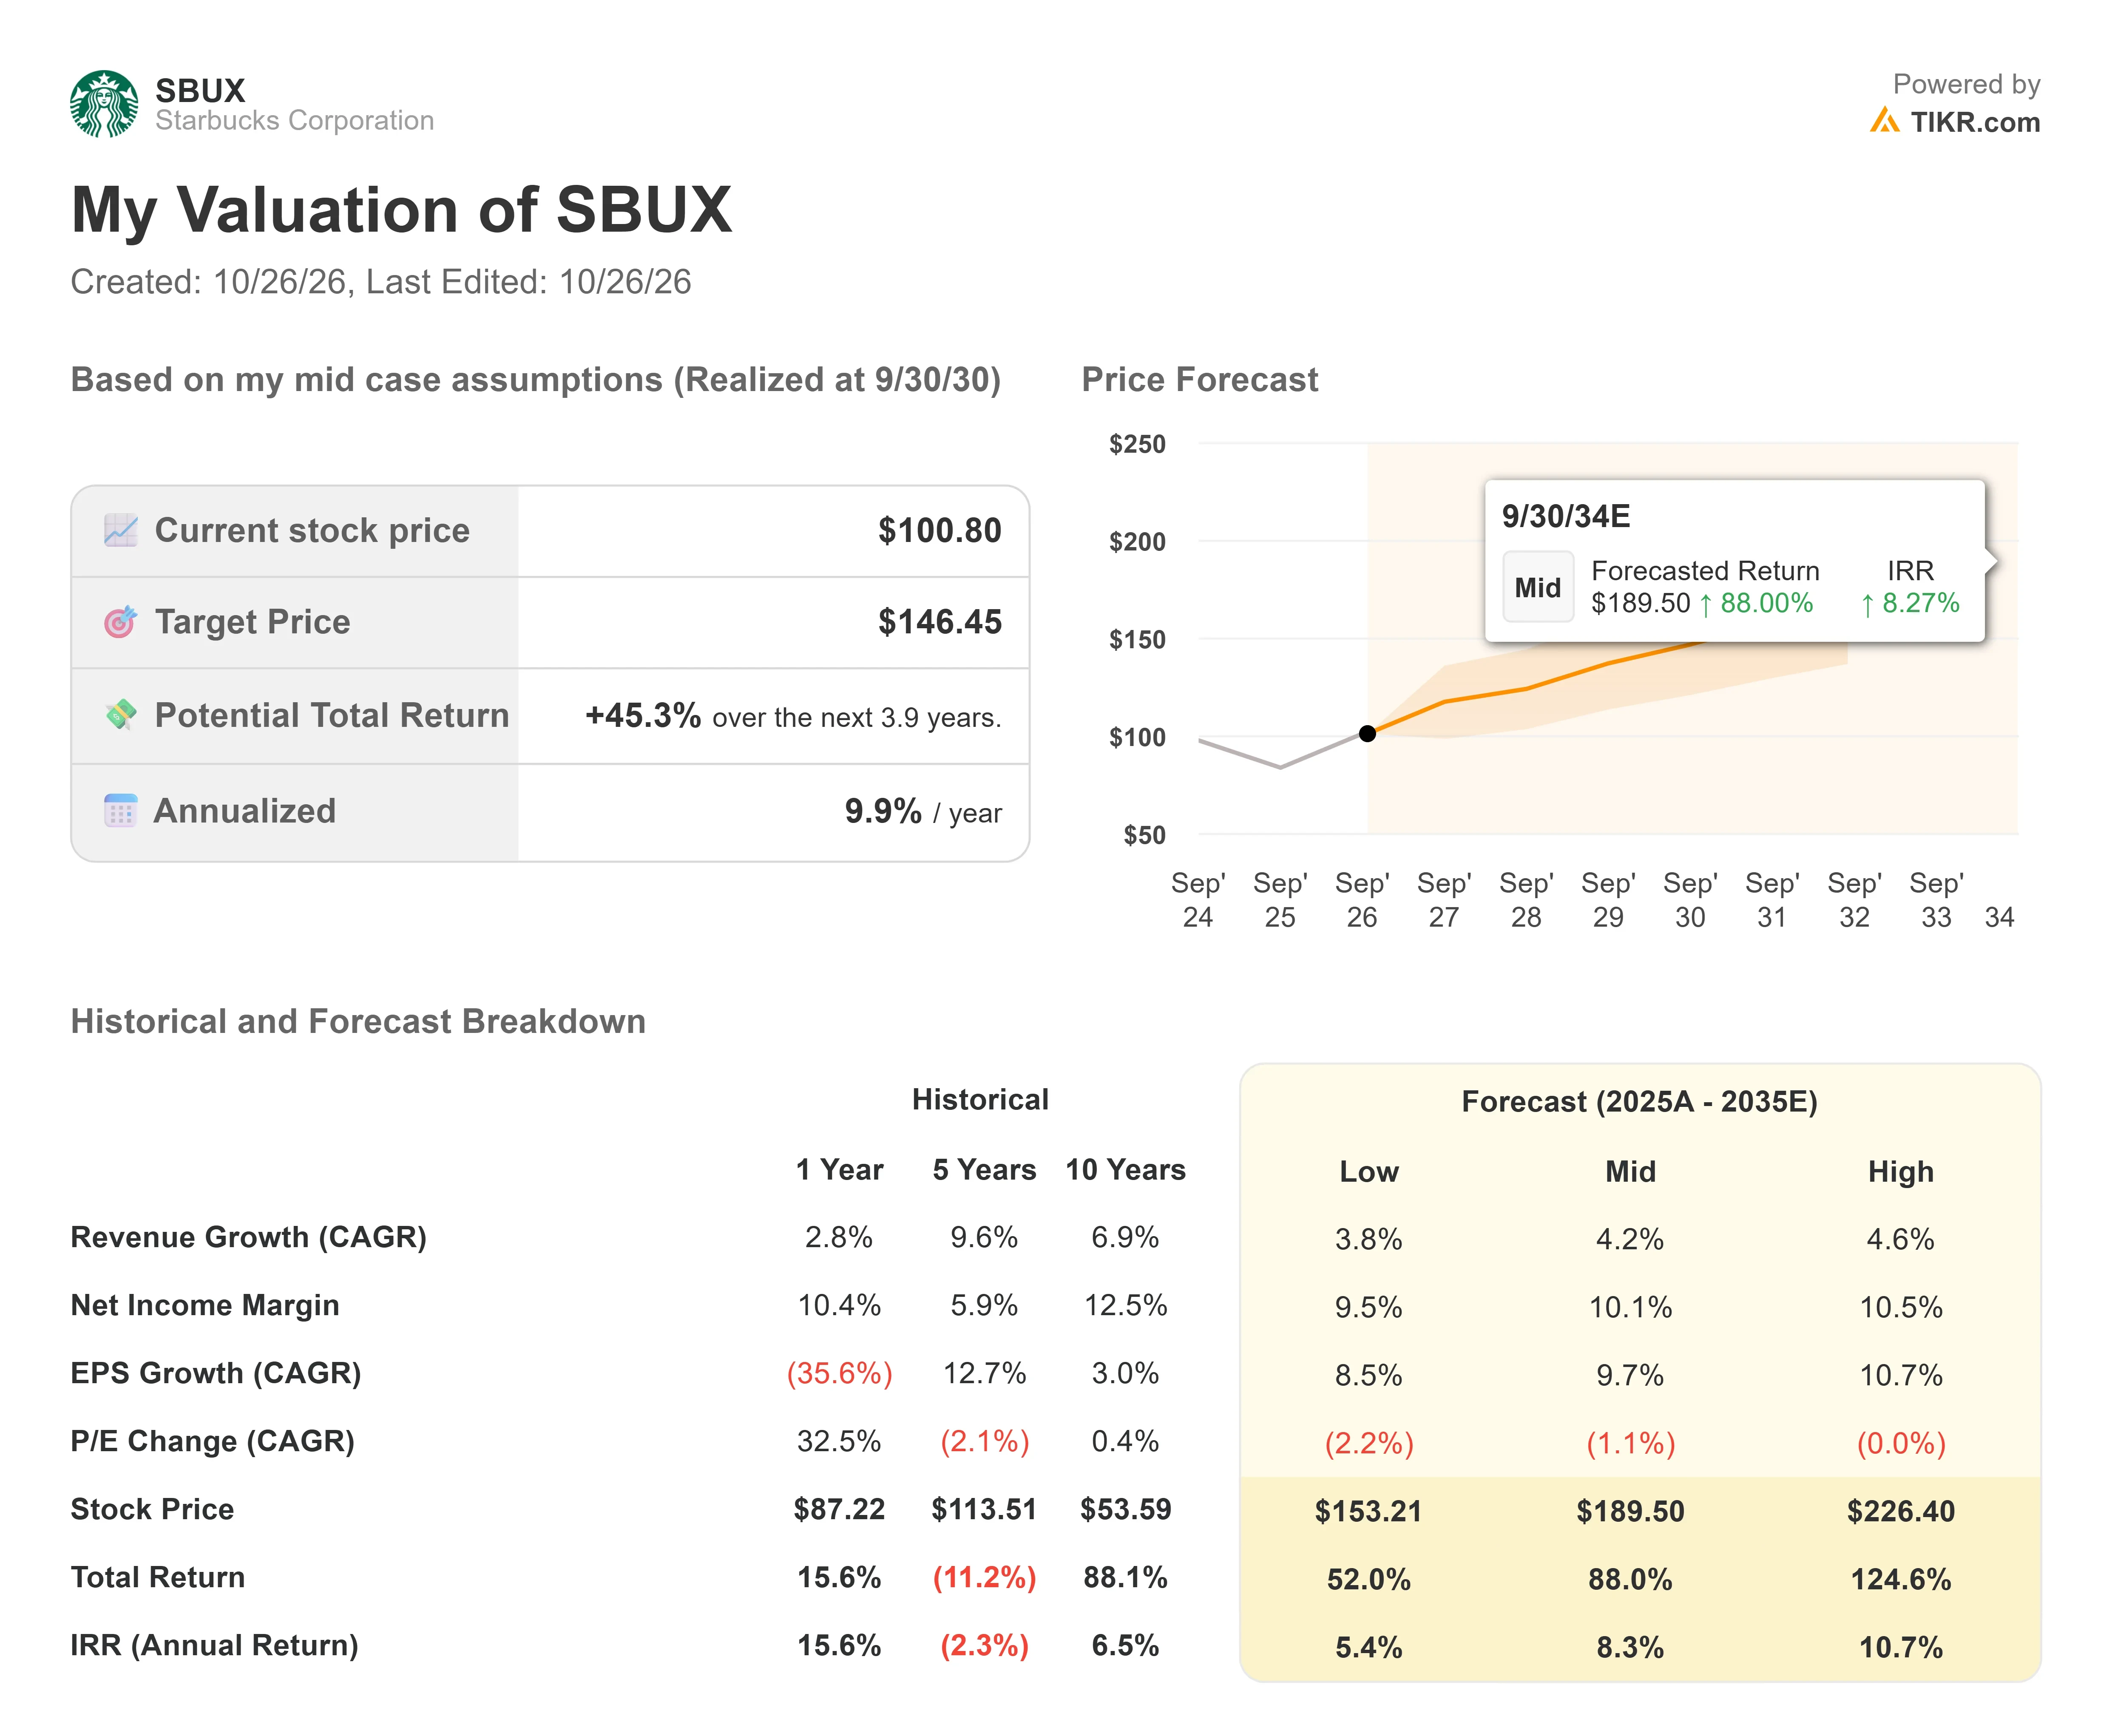
The mid case puts Starbucks at around $146 by September 30, 2030, about 45% above $100.80, or ~10% a year. Its mid-case assumptions call for revenue growth of about 4% a year, a net margin near 10% and EPS growth near 10% a year, with the P/E drifting slightly lower. That target sits about 33% above the ~$110 Street mean; of the 35 analysts TIKR tracks, 12 rate the stock Buy, 2 Outperform, 18 Hold, 2 Underperform and 1 Sell.
Upside comes if store-driven comps keep running near 4 points as closures are lapped. Downside comes if margins without refund help drift back toward the year-ago 9.4% EBIT margin, which would undercut the earnings growth the mid case needs.
Conclusion
On October 29, two numbers matter more than the headline comp: how much of it management credits to store performance versus closures and delivery, and whether Q4 EBIT margin lands near the ~12.4% that estimates imply. A store-driven share above half with margin at or above that mark supports the rebound; a comp leaning on closures and delivery with margin well short of it sides with the analysts cutting targets.
So what is Starbucks stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Starbucks could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Analyze Starbucks on TIKR Free →
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!