


Key Takeaways
- Nebius’s total debt exploded from $1.22 billion to $10.06 billion in the year to June 2026, and that figure does not even include the $5.75 billion in convertible notes it closed in August.
- Free cash flow swung from nearly breakeven, at negative $0.21 billion, in the first quarter of 2026 to negative $3.41 billion in the second, its worst quarter on record, as $5.7 billion of capital spending outran $2.3 billion of operating cash flow.
- Between March and September 2026, Street analysts nearly halved their Buy ratings on the stock, from 9 to 3, even as the average price target nearly doubled to $290.71 over the same stretch.
- Nebius’s rebuttal to the “altnet” comparison rests on customer prepayments and contracted-cash-flow-backed debt, but the balance sheet is growing faster than either defense is currently offsetting.
The Comparison Nebius Is Trying to Get Ahead Of
Reuters Breakingviews columnist Edward Chancellor made an explicit case this month that today’s neoclouds resemble the “altnets,” the alternative telecom carriers that spent close to $500 billion building broadband networks in the late 1990s on the promise of insatiable demand, then defaulted in waves once capital markets closed in 2000. Nebius sits squarely in that comparison. It builds AI data center capacity ahead of signed contracts, wagering that demand will absorb whatever it constructs. Short seller Jim Chanos, cited in the same column, argues neocloud economics do not clear the cost of capital even when GPU depreciation is stretched to a decade.
Nebius’s executives reject the parallel directly. CEO Arkady Volozh told investors at Citi’s TMT conference this month that demand visibility has stretched from 18 months to as much as 24, with orders now arriving for the first half of 2028. CFO Dado Alonso has pointed to customer prepayments, which covered roughly 70% of Q2 deals and are expected to bring in more than $9 billion in 2026, as the structural difference from altnets that borrowed blind against unproven traffic.
That is the thesis worth testing. Prepayments and disciplined financing are a real distinction from a 1990s bond-funded land grab, but only if the balance sheet backs it up.
The Numbers Are Moving Faster Than the Defense

They do not, yet. Nebius’s total debt has gone from essentially nothing, $30 million in September 2024, to $10.06 billion by June 2026. Most of that arrived in the past year: debt nearly doubled in a single quarter, from $4.97 billion at year-end 2025 to $9.59 billion by March 2026, before growth slowed to 4.9% in the second quarter. That June print still excludes the $5.75 billion in convertible notes Nebius closed in August and the $2.8 billion it raised through its at-the-market equity program in the second quarter alone.
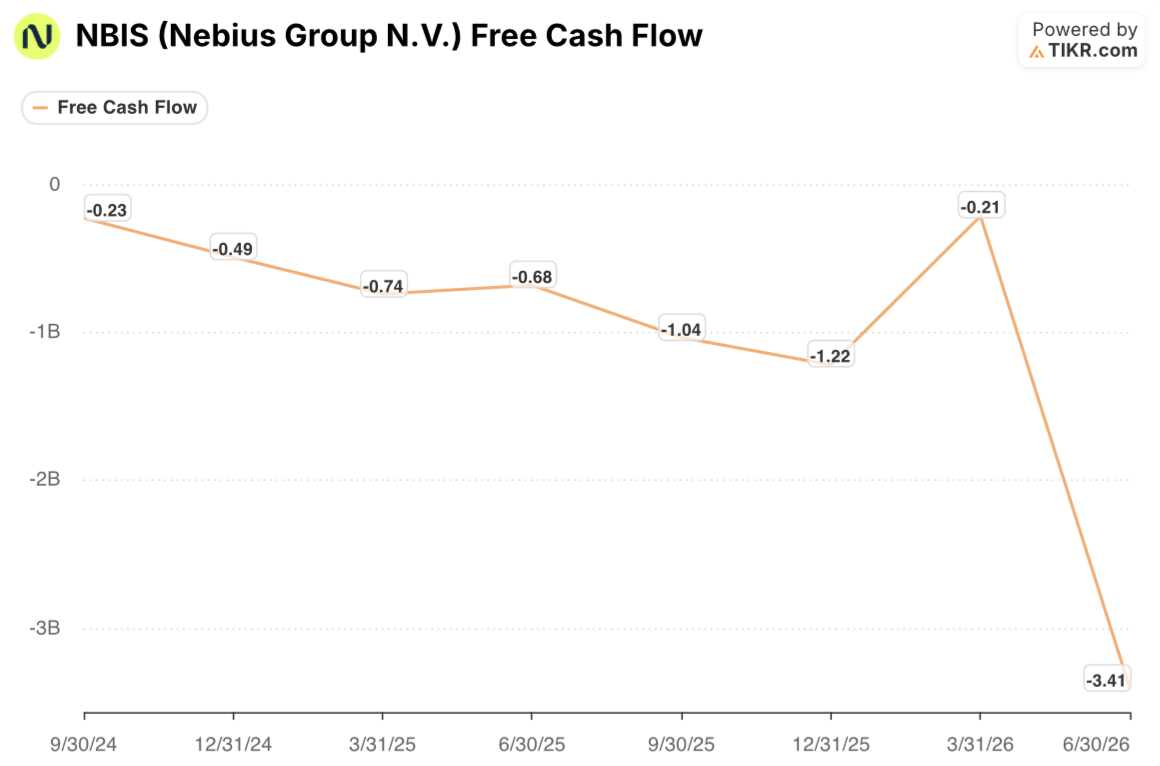
Free cash flow tells a similarly jagged story. It improved to nearly breakeven, negative $0.21 billion, in the first quarter of 2026, then collapsed to negative $3.41 billion in the second, by far its worst quarter in the two-year history TIKR shows.
That swing lines up with what management disclosed on the Q2 call: $5.7 billion of capital expenditure against $2.3 billion of operating cash flow. Prepayments clearly helped operating cash in one quarter. They did not stop capex from outrunning it the next.
Check Nebius’s debt and free cash flow trend against its own prepayment claims on TIKR for free →
Even the Street Isn’t Fully Buying the Rebuttal

The clearest sign of unease is not in Nebius’s own filings, it is in how analysts are rating the stock. Between the end of March and September 11, coverage broadened from 13 to 17 analysts, and the average price target nearly doubled, from $165.85 to $290.71. But the number of analysts rating the stock an outright Buy fell from 9 to 3 over the same window, while Hold, Underperform, and Sell ratings, categories barely present a year earlier, now make up a meaningfully larger share of coverage.
That is an unusual combination. Analysts are not calling the growth story wrong, the rising targets say the opposite, but a shrinking share of them are willing to stake a Buy rating on it at the current price and debt load. It reads less like conviction that Nebius clears the cost-of-capital bar Chanos describes, and more like a market hedging on timing while the capacity race continues.
The September Quarter Will Show Whether This Is Discipline or Momentum
Nebius has genuine advantages the altnets never had: a contracted backlog above $40 billion, an asset-backed facility priced at SOFR plus 250 basis points against real cash flows rather than unsecured junk debt, and a business already generating a 41% adjusted EBITDA margin, something few altnets ever managed. Those are not cosmetic differences.
But the balance sheet evidence through June 2026 does not yet show a company financing its buildout mainly off its own operating economics. It shows one financing it through debt and equity issuance, at an accelerating pace, ahead of the cash generation to match. The $5.75 billion convertible raise and the ATM proceeds not yet reflected in the June numbers mean the September quarter, when Nebius next reports, is the one that actually tests the thesis: does debt growth decelerate the way it briefly did in the second quarter, or does the near-doubling pattern from the first quarter reassert itself as the buildout pushes past 5 gigawatts of contracted power. Investors betting that this time is different should treat that print as the evidence, not the earnings-call rhetoric that will accompany it.
See whether Nebius’s next debt and cash flow print backs up management’s own prepayment defense on TIKR for free →
Should You Invest in Nebius Group N.V.?
The only way to really know is to look at the numbers yourself. TIKR gives you free access to the same institutional-quality financial data that professional analysts use to answer exactly that question.
Pull up Nebius Group N.V. stock and you’ll see years of historical financials, what Wall Street analysts expect for revenue and earnings in the quarters ahead, how valuation multiples have moved over time, and whether price targets are trending up or down.
You can build a free watchlist to track Nebius Group N.V. alongside every other stock on your radar. No credit card required. Just the data you need to decide for yourself.
Access Professional Tools to Analyze NBIS stock on TIKR for Free →
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!






