


Key Stats for Dell Stock
- Friday’s Performance: 12%
- 52-Week Range: $110 to $568
- Valuation Model Target Price: Around $570
- Implied Upside: 1%
Analyze your favorite stocks like Dell Technologies with TIKR (It’s free) >>>
What Happened?
Dell Technologies stock jumped about 12% to $567 per share on Friday, reaching a record high as investors grew more confident that the AI infrastructure boom can keep expanding beyond GPU servers into traditional compute, Storage, networking, and enterprise deployments. Hewlett Packard Enterprise rose 12.4% on the same day, while Dell also competes with Super Micro Computer and Lenovo across servers and enterprise infrastructure, making the broader strength in hardware names another sign that AI spending remains robust.
Dell stock surged because Oracle’s latest results reinforced expectations for continued heavy AI infrastructure spending, while RBC Capital initiated coverage with an Outperform rating and a $640 price target. Oracle reported $19.3 billion of quarterly revenue, up 30%, while cloud infrastructure revenue jumped 121% to $7.4 billion, and the company maintained plans for roughly $90 billion to $95 billion of fiscal 2027 capital spending. For Dell, that spending matters because expanding AI data centers require servers, Storage, networking, and related infrastructure, giving the company several ways to benefit beyond GPU server shipments alone.
This week, Dell CFO David Kennedy said the company continues to see an “accelerating appetite for infrastructure,” after booking $60.9 billion of AI server orders in Q2 and ending the quarter with a $95 billion backlog. Traditional servers and networking grew 122%, Storage increased 26%, and Dell now expects $192 billion of fiscal 2027 revenue, while management said demand for both AI and traditional servers continues to outpace supply. Storage is particularly important because Dell-owned products include more software and services, giving the company a higher-margin growth lever alongside hardware-heavy AI systems.
Analyst actions added further support to the rally. Evercore ISI raised its Dell price target to $650 from $575, while RBC Capital initiated coverage with a $640 target and an Outperform rating. HPE provides a useful peer comparison after its latest quarterly revenue increased 34%, including about 35% growth in server revenue, reinforcing that strong infrastructure demand extends beyond Dell. The bigger takeaway is that Dell’s opportunity is broadening beyond AI server shipments into Storage, traditional compute, enterprise modernization, and operating leverage as customers build out more complete AI infrastructure.

Value Dell Technologies instantly (Free with TIKR) >>>
Is Dell Undervalued?
Under valuation assumptions, the stock is modeled using:
- Revenue Growth (CAGR): Around 31%
- Operating Margins: Around 11%
- Exit P/E Multiple: 12x
The unusually high around 31% revenue growth assumption reflects Dell’s near-term AI infrastructure ramp, including its $95 billion AI server backlog, rather than an expectation that the company can sustain 30%+ growth indefinitely. Continued traditional server demand and the early stage of enterprise AI adoption provide additional growth opportunities as more companies move beyond experimental deployments.
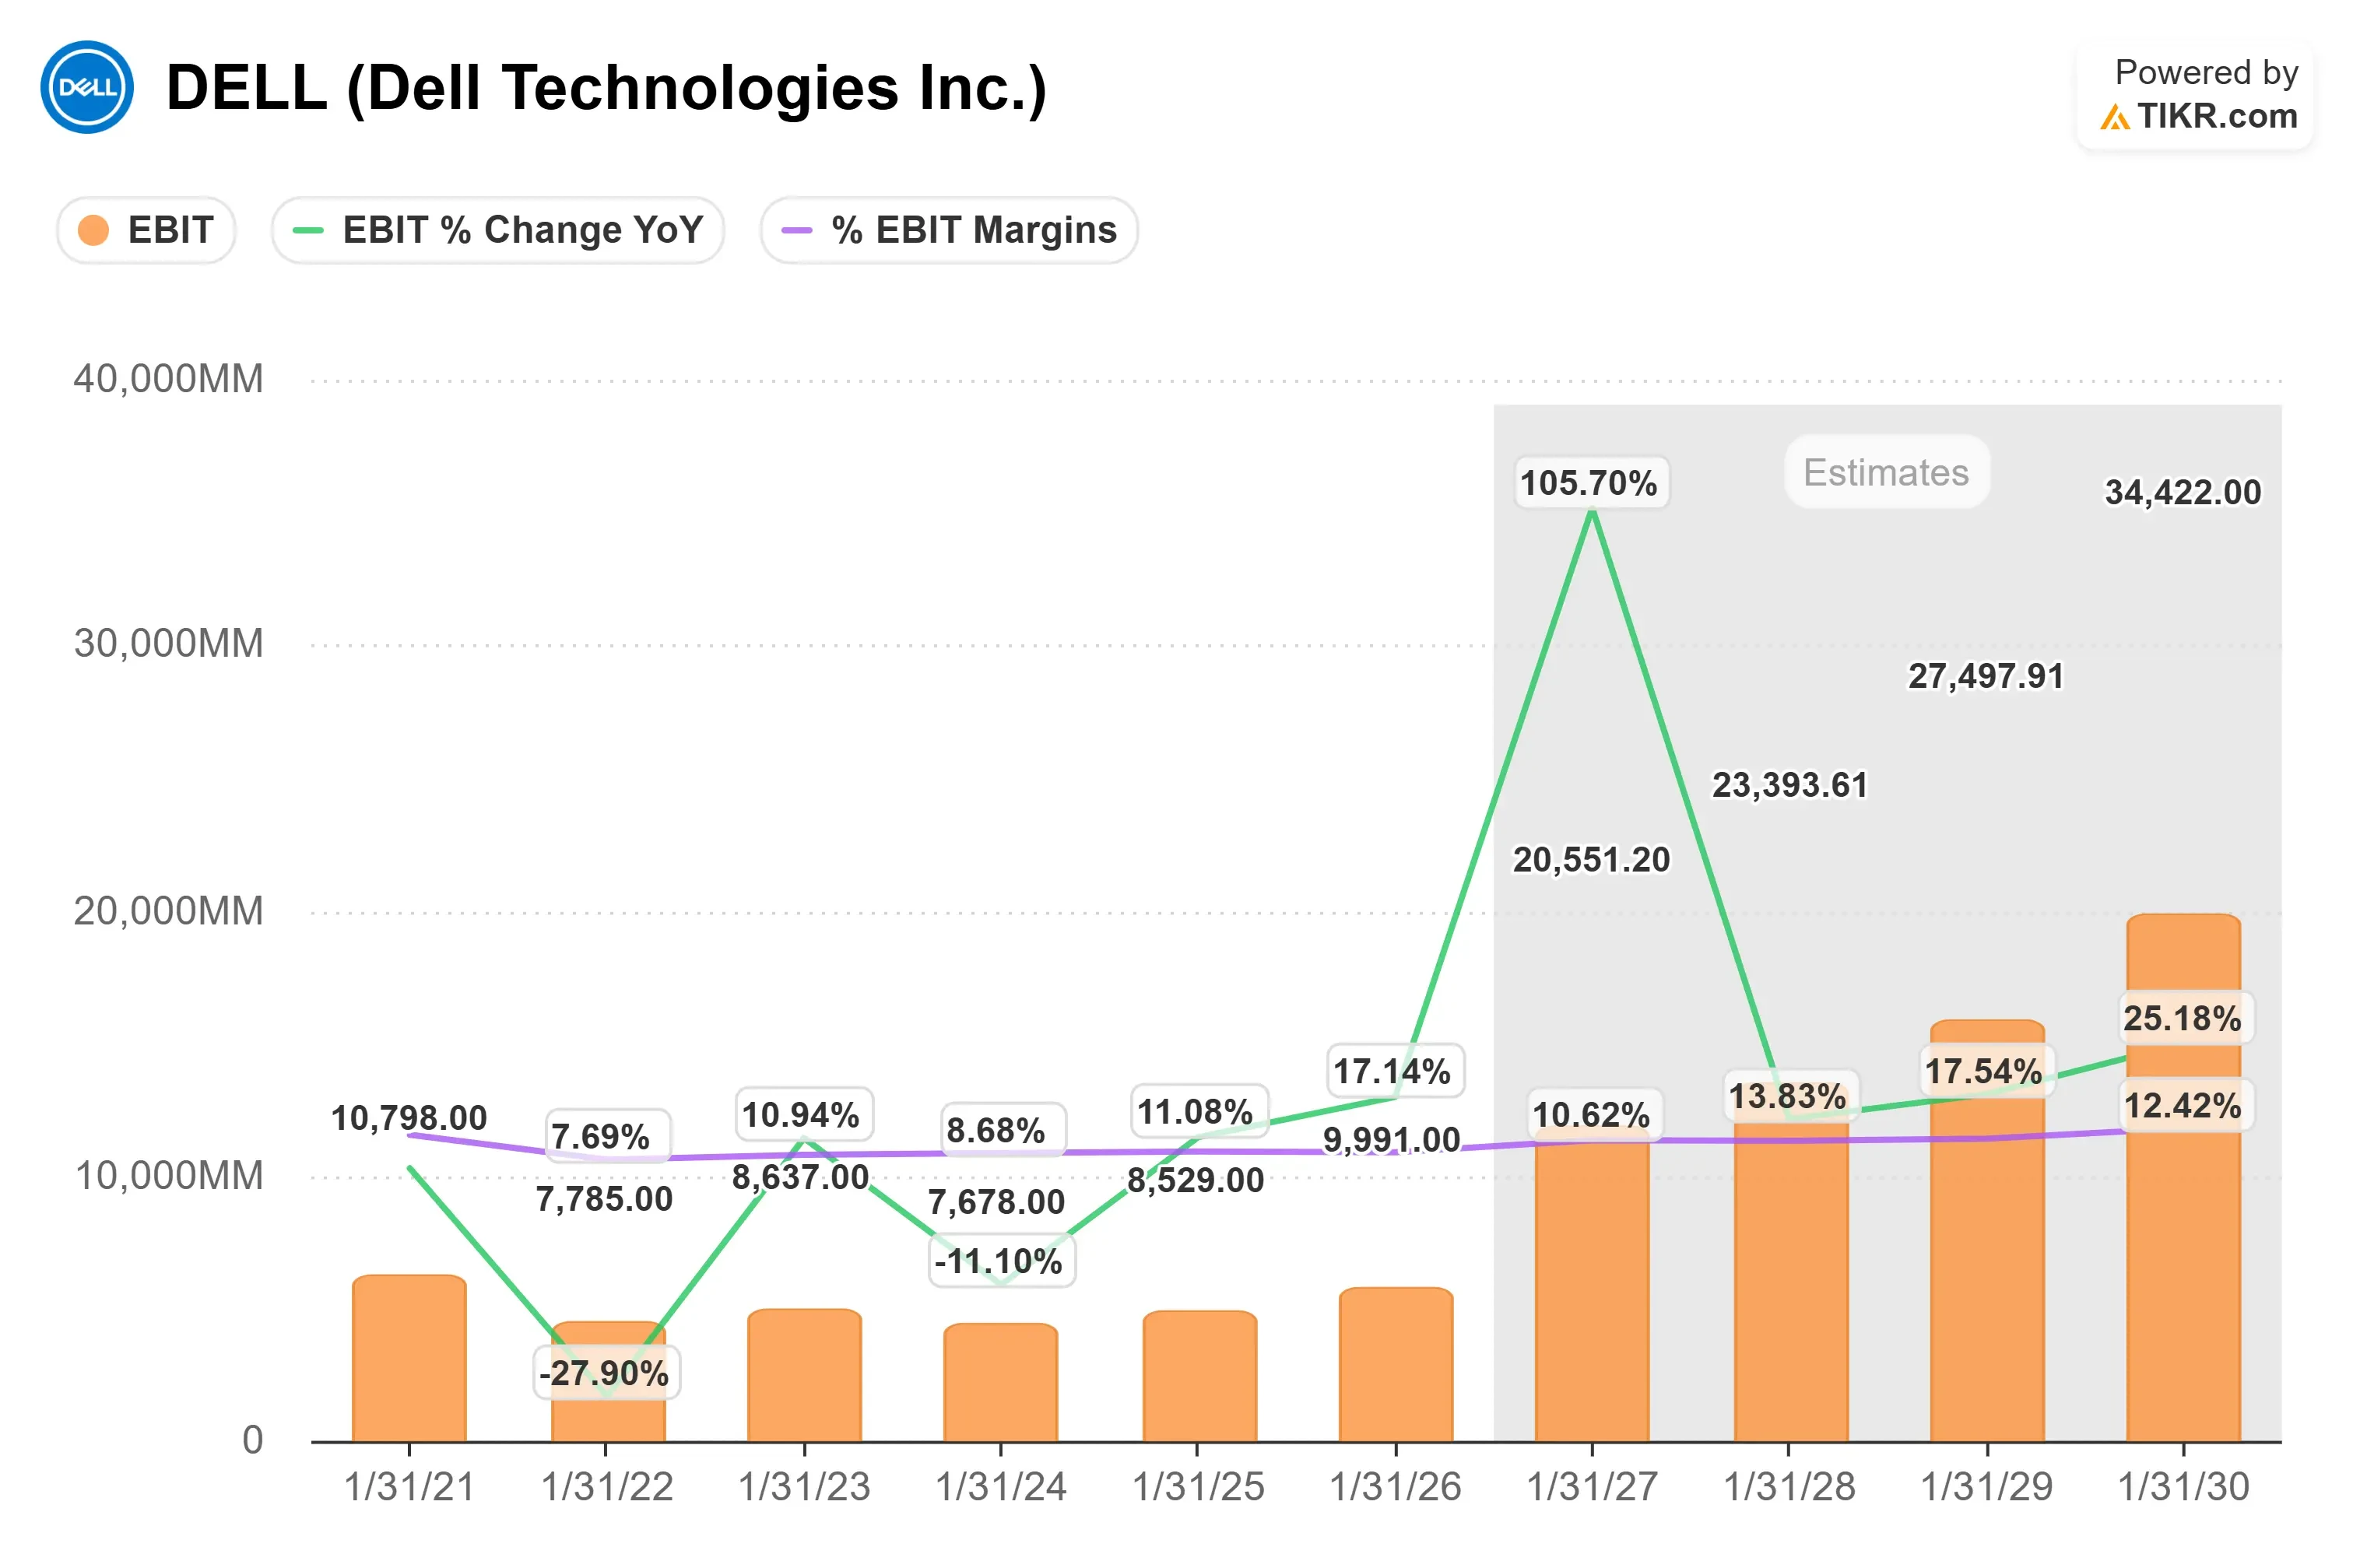
The around 11% operating margin assumption depends on Dell turning rapid infrastructure growth into higher-quality earnings. AI servers generate enormous revenue but carry lower margin rates, while Storage, software, services, and operating scale can contribute more profit per dollar of sales. The TIKR EBIT chart supports that thesis, with consensus estimates showing EBIT rising materially over the coming years and EBIT margins reaching around 12% by fiscal 2030.
See analysts’ growth forecasts and price targets for Dell Technologies (It’s free) >>>
The 12x exit P/E looks relatively restrained rather than aggressive based on Dell’s historical valuation figures in the TIKR model. That means the thesis does not depend on investors assigning Dell a dramatically richer multiple, making backlog conversion, Storage growth, and margin execution more important to future returns.
Based on these assumptions, the valuation model estimates a target price of around $570, compared with Dell’s recent price near $567, implying about 1% total upside over roughly 2.4 years and leaving little valuation cushion at current levels.
At current prices, Dell Technologies appears fairly valued, with stronger returns likely requiring continued AI order strength, successful backlog conversion, sustained Storage growth, and improving EBIT margins to drive earnings above what the current valuation already reflects.
How Much Upside Does Dell Stock Have From Here?
Investors can estimate Dell Technologies’ potential share price, or what any stock could be worth, in under a minute using TIKR’s New Valuation Model tool.
All it takes is three simple inputs:
- Revenue Growth
- Operating Margins
- Exit P/E Multiple
From there, TIKR calculates the potential share price and total returns under Bull, Base, and Bear scenarios so you can quickly see whether a stock looks undervalued or overvalued.
If you’re not sure what to enter, TIKR automatically fills in each input using analysts’ consensus estimates, giving you a quick, reliable starting point.
Value Dell Technologies in under 60 seconds with TIKR (It’s free) >>>



