Key Takeaways
- Intel shares rose 4% today after New Street Research upgraded the stock to Buy from Neutral with a $125 price target.
- New Street argues that AI agents will keep server CPUs in short supply for years, and Intel’s own data center results back up that demand.
- New Street’s 2030 earnings forecast is only a little above Wall Street’s, so the target mostly needs the current consensus to hold.
- Intel reports third-quarter results on Thursday, Oct. 29, and the data center margin is the number to watch.
Intel (INTC) stock rose 4% today after New Street Research upgraded the chipmaker to Buy from Neutral with a $125 price target before the open.
Analyst Pierre Ferragu’s case is all about server chips:
“Agentic AI is driving a sustained increase in server CPU demand, with supply constraints set to persist for years, while Intel is getting rid of bad nodes and adding capacity,” he wrote.
The shortage is already in Intel’s numbers
New Street estimates Intel’s server capacity can grow more than 50% in 2027. By 2030, it sees $50 billion of server CPU revenue for Intel, even as Intel’s share of a market topping $220 billion slips to 20% to 25%.
Intel’s own results back up the demand. Data Center and AI revenue jumped 59% to $6.3 billion in the second quarter, and the segment’s operating margin hit 39.5%, up from 16.1% a year earlier.
Some of that is pricing, though. Server prices fell 4% in 2025 before Intel raised them during this year’s shortage, and those margins could slip once supply loosens.
TIKR tracks 50 analysts on Intel. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Intel, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Intel’s Analyst Ratings
The target leans on Wall Street’s own math
New Street’s target rests on its forecast of $7.10 in EPS for 2030. That’s only a bit above the $6.59 consensus for that year, and the consensus path is already steep…

New Street thinks a data center beat could lift those estimates next year. And its $125 target isn’t far from the $117 consensus.
The price is the harder part. Intel traded at 51x forward earnings at the last close…
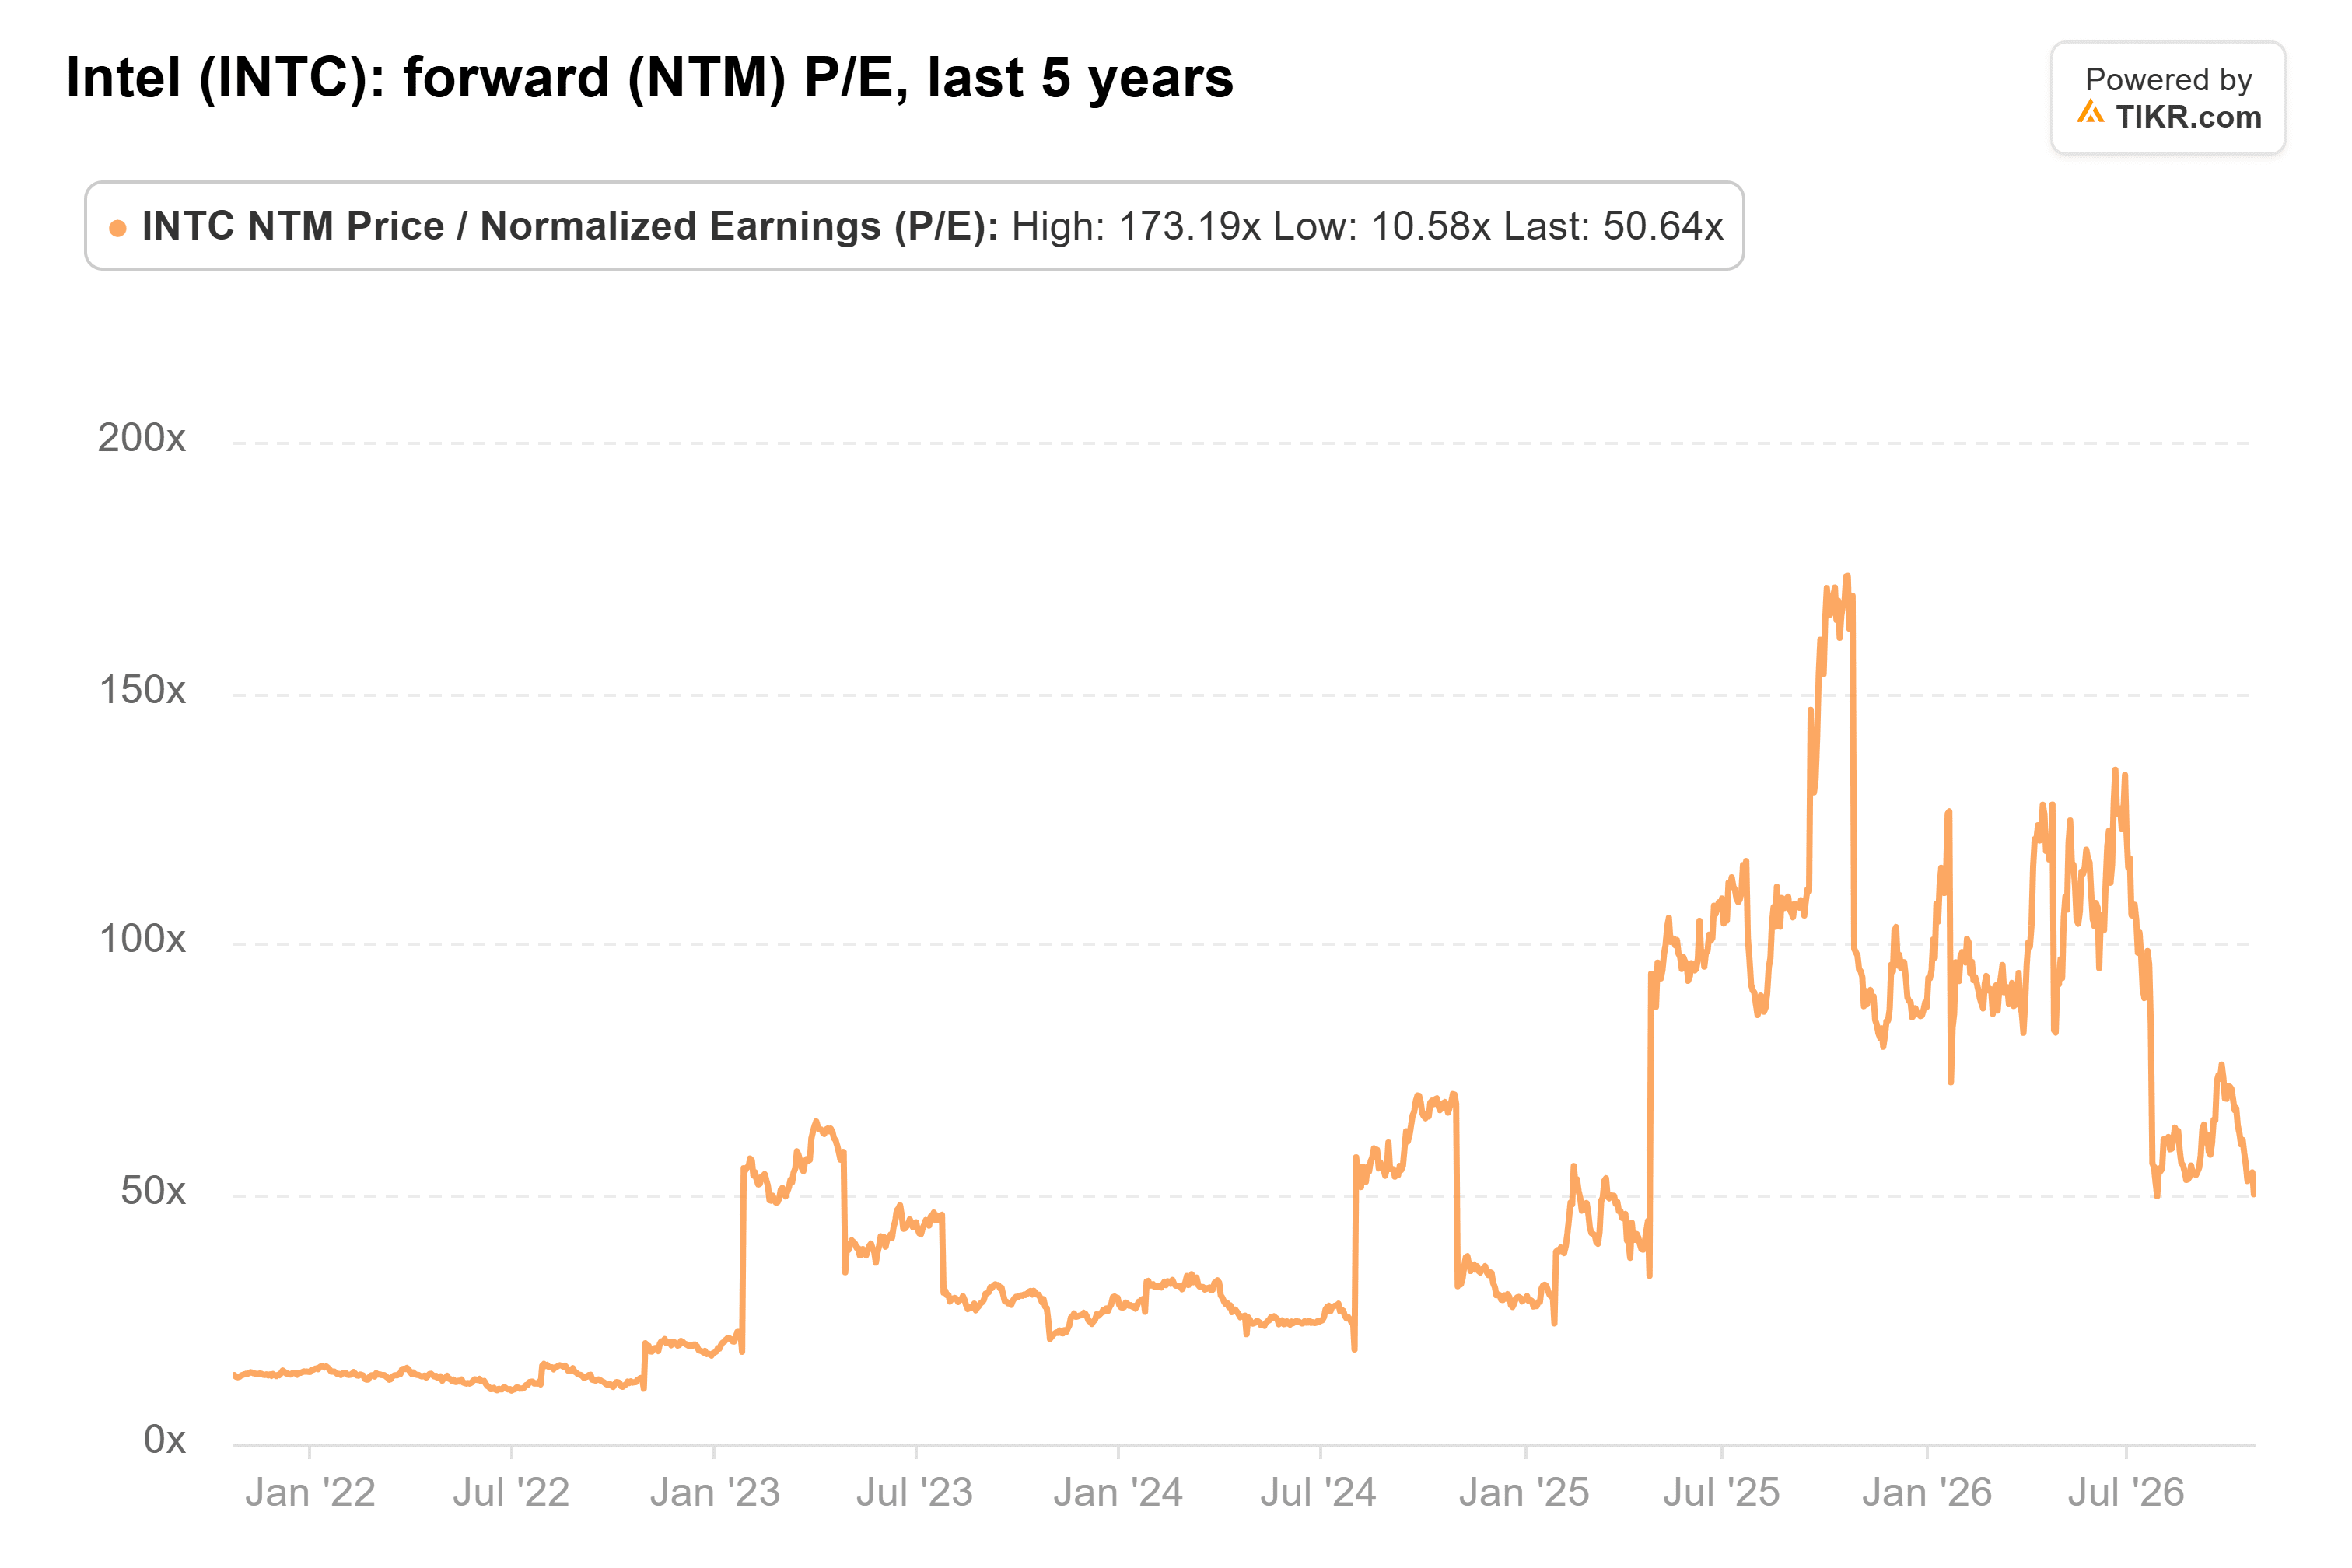
That’s right at its five-year average of 50x, but years of tiny earnings inflate that average (the multiple hit 173x a year ago). From 2014 to 2022, Intel traded between 10x and 18x.
Thursday is the first test
Intel reports third-quarter results on Thursday, Oct. 29, after the close. Management guided for $15.8 billion to $16.8 billion of revenue, a 42% non-GAAP gross margin and $0.38 of non-GAAP EPS. Intel has topped its own guidance seven quarters running.
The number to watch is the data center margin. If it holds near the second quarter’s 39.5%, the shortage is still paying off.
My take: the server shortage is the strongest part of Intel’s story, and New Street’s target doesn’t ask for much more than Wall Street already expects. At around 51x forward earnings, though, the stock needs Thursday’s report to keep proving it.
So what is Intel stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Intel could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!