Key Takeaways
- Record Quarter: Q3 net income reached ~$2B, over $100M above June guidance, as yields rose nearly 2.5% YoY and cruise costs ex-fuel per ALBD climbed only 1.8%.
- Fuel Offset: A $150M fuel price hit absorbed more than $150M of operating gains, so full-year EPS guidance rose only $0.02 to $2.24.
- Forward Book: 2027 is half booked with occupancy and pricing at record levels.
- Credit Upgrade: S&P moved Carnival to investment grade as total debt fell below $24B from its $36B 2023 peak, with $1.2B of buybacks done.
Net income beat guidance by $100 million, yet full-year EPS rose only $0.02. Pull up Carnival’s income statement on TIKR for free →
Carnival Beats on Every Operating Line, but Fuel Caps the EPS Raise at $0.02
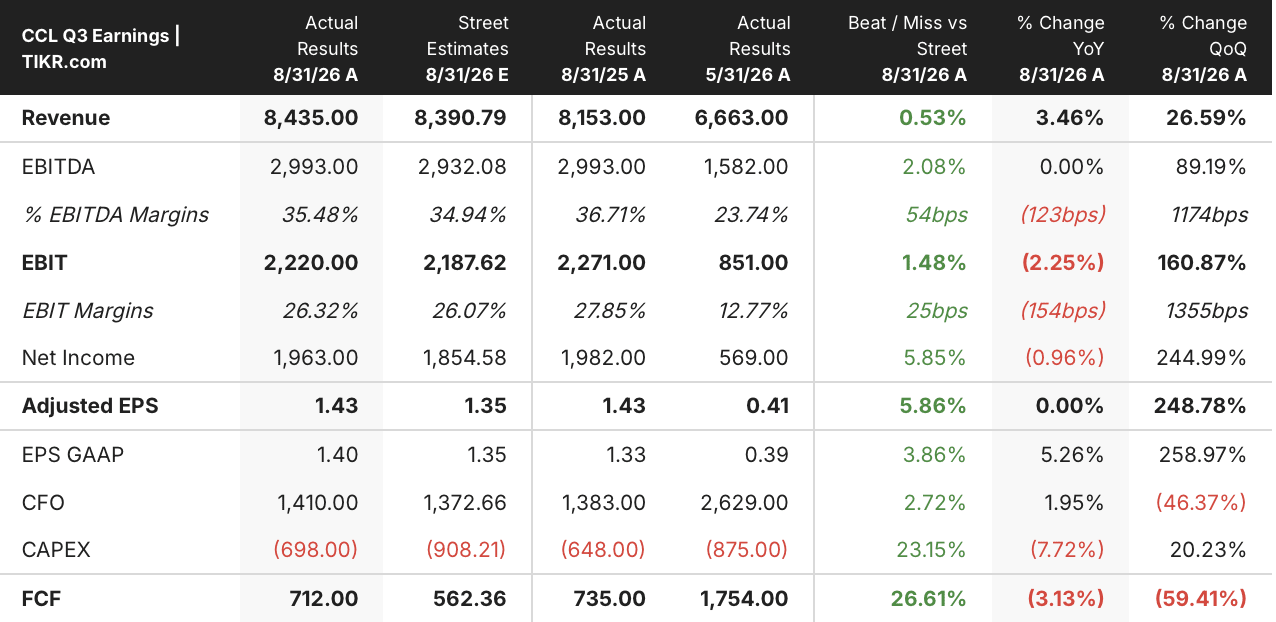
Carnival Corporation (CCL) posted record revenues, yields and net income in Q3 2026, then lifted full-year EPS guidance just $0.02 to $2.24 because a $150 million fuel price hit offset more than $150 million of operating improvement.
The quarter itself ran ahead of June guidance on every operating line. Net income reached about $2 billion, beating the guide by more than $100 million, or $0.08 per share, while yields (net revenue per available lower berth day, or ALBD, the industry’s capacity unit) rose nearly 2.5% year over year, 1.2 percentage points better than guided. Cruise costs excluding fuel per ALBD climbed only 1.8%, 100 basis points better than the guide.
That outperformance did not reach the full-year number intact. Operations added $0.12 per share to the guide, $0.08 of it from yields, and buybacks added $0.01, but higher fuel prices took back $0.11.
CEO Josh Weinstein addressed the fuel swing directly on the Q3 earnings call: “Yes, fuel can be a volatile input cost with a track record of prices going up and down. But amidst that noise, let’s not lose sight of our underlying operational improvement.” The evidence sits in consumption. Fuel use per ALBD has fallen 26% since 2019, which CFO David Bernstein valued at nearly $750 million in savings at September guidance fuel prices, and Carnival still declines to hedge, preferring to burn less over paying counterparties to smooth prices.
The forward book gives that case its footing. Carnival is half booked for 2027 with occupancy and pricing both at record levels, and customer deposits hit a third-quarter record of about $7.6 billion, up about 7% on flat capacity over the next 12 months.
Two drags sit inside that book. Carnival Rewards, the loyalty program Carnival Cruise Line launched September 1, defers a slice of revenue and weighs on yields until 2028, and the first quarter of 2027 still carries residual damage from this spring’s booking disruption.
Cash flow runs the other way. Carnival has repurchased $1.2 billion of stock, or 45 million shares, in six months, and cut total debt below $24 billion from a $36 billion peak in 2023. S&P’s upgrade made it the second agency to rate Carnival investment grade and released the collateral, leaving no secured debt. Carnival stock closed at $25 on September 30, down 2% on the day, one session after a quarter that beat guidance on yields and costs.
Customer deposits hit a Q3 record of $7.6 billion. Explore Carnival’s revenue history on TIKR for free →
Wall Street Averages a $34 Target on Carnival Stock, Above the $25 Close
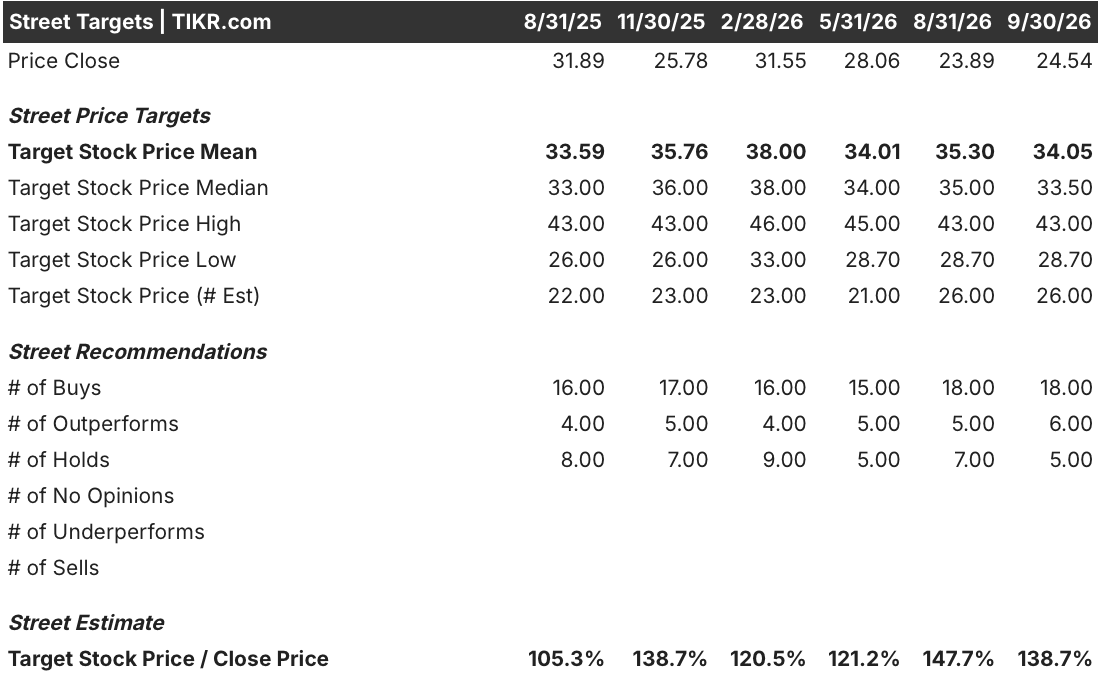
The 26 analyst price targets on Carnival stock average $34 as of September 30, or 139% of the $25 close, with a low of $29 and a high of $43. Ratings lean the same way, with 24 Buy or Outperform calls against 5 Holds and no Sells, and TIKR’s $43 mid-case target matches the top of the Street’s range.
TIKR Values Carnival Stock at $43, a 76% Gain by November 2030
TIKR’s mid-case model values Carnival stock at $43 by November 2030, implying 76% total return from the current price of $25, or 15% annualized over 4.2 years.

A 15% annualized return is a fast clip for a cruise operator adding almost no capacity, so pricing and cost control, not new ships, carry the gain.
The Q3 call supports that path: Carnival beat June guidance on yields by 1.2 percentage points and on costs by 100 basis points, and 2027 is already half booked at record occupancy and pricing.
TIKR’s model sees $43 by November 2030. Test your own Carnival assumptions on TIKR for free →
So what is CCL stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what CCL stock could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Carnival Corporation for free→
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!