Key Stats for PINS Stock
- Past week performance: -1.0%
- 52-week range: $14 to $35
- Valuation model target price: $28
- Implied upside: 49.2% over 2.2 years
Unlock 5 years of Pinterest projections and see what buybacks add (It’s free) >>>
Pinterest Keeps Growing, but the Market Isn’t Buying It
Pinterest (PINS) shares slipped 1.0% over the past week and trade near $19. That leaves the visual discovery platform about 46% below its 52-week high of $35. The weak price contrasts with revenue still growing at double-digit rates. Investors seem more worried about the next few quarters than the last one.
September brought a pair of key headlines. Pinterest launched Visual Search Ads, which let brands bid for top spots in search results and product close-ups. These ads target shoppers comparing items, and advertisers usually pay more to reach them. Meanwhile, CFO Julia Donnelly leaves on October 30, and Vikram Naidu will serve as interim finance chief.

Q2 results set the tone. Revenue rose 18% to $1.18 billion, and monthly active users hit a record 640 million. On the earnings call, CEO Bill Ready said the results “reflect the progress we’re making against our strategic priorities.” Yet shares fell about 7% after hours because Q3 guidance implied slower growth.
Donnelly explained the slowdown on that call. She said “in Q2, we saw a nearly one-point benefit from World Cup-related spend that will not repeat in Q3.” Q3 revenue guidance of $1.19 billion to $1.21 billion implies 13% to 15% growth. Going forward, Visual Search Ads must help offset those fading tailwinds.
Spot shifts in Pinterest’s analyst targets as the CFO handoff unfolds (It’s free) >>>
Pinterest Is Priced for Stagnation Despite Double-Digit Growth
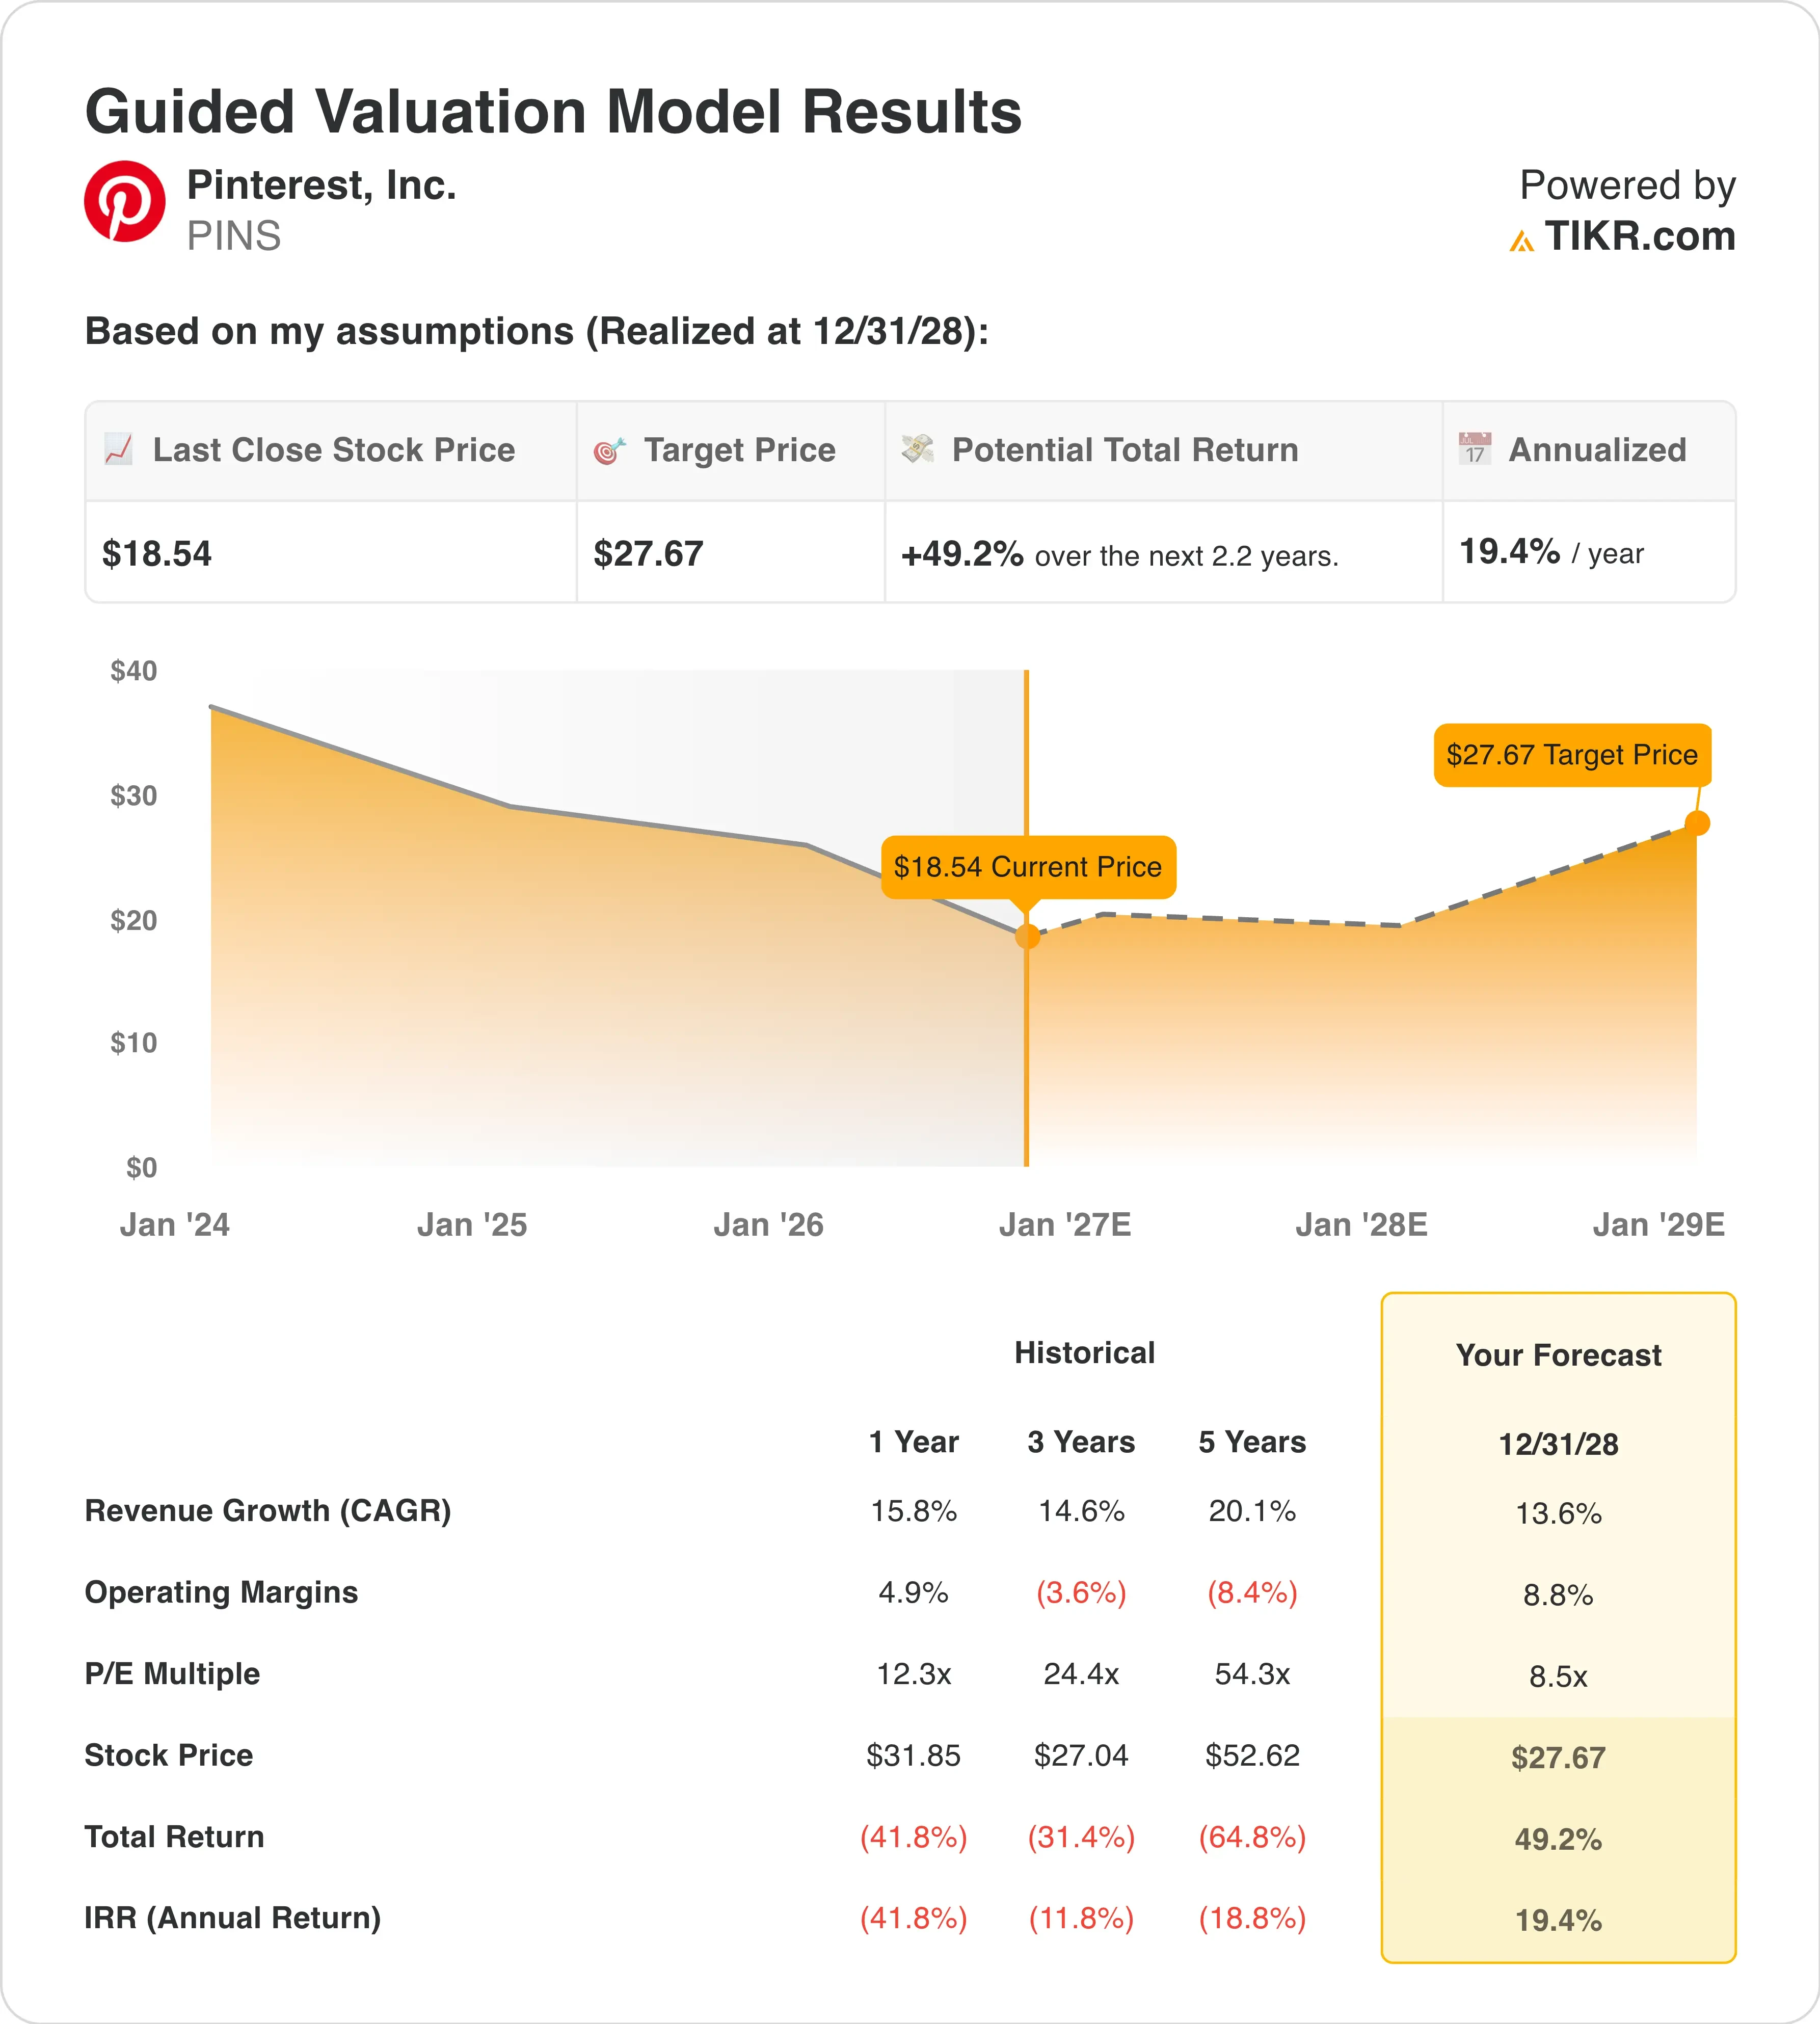
Under valuation model assumptions realized through 12/31/28, the stock is modeled using:
- Revenue Growth (CAGR): 13.6%
- Operating Margins: 8.8%
- Exit P/E Multiple: 8.5x
Based on these inputs, the model estimates a target price of $28. This implies a 49.2% total return from the $19 share price and a 19.4% annualized return over 2.2 years.
Such a return clears the 15% bar that signals real undervaluation. Notably, the model needs no heroic assumptions to get there. Revenue growth of 13.6% a year sits below the 14.6% pace of the past 3 years. And the 8.5x exit multiple simply matches today’s forward valuation.

The multiple sits at the heart of this story. Pinterest’s price-to-earnings ratio has contracted about 35.7% a year over the past 5 years. At 8.5x forward earnings, the market prices Pinterest like a company with little growth ahead. Yet analysts expect revenue to grow 14.7% a year over the next 2 years.
Margins give the model its lift. Operating margin reached 4.9% over the past year after averaging negative 3.6% over 3 years. The model assumes 8.8% by 2028, and management targets about 30% adjusted EBITDA margins in 2026. Visual Search Ads could push margins higher if they raise prices per ad.
Capital returns add another layer. Pinterest repurchased over $2 billion of stock this year at about $18 per share, backed by Elliott’s $1 billion investment. That buyback shrinks the share count and lifts earnings per share. Compared with Snap at 7.4x forward earnings, Pinterest offers better profits for a modest premium.
Rerun Pinterest’s valuation at a higher multiple and see the upside grow (Free with TIKR) >>>
Pinterest Takes On the Social and Shopping Ad Giants
Meta Platforms (META) sets the pace in social advertising. Its Q2 revenue grew 28% to $60.8 billion, well ahead of Pinterest’s 18%. Operating margin fell to 31% on legal and severance charges, but it still far exceeds Pinterest’s 6.3%. Scale lets Meta spread AI costs across billions of users.
Amazon (AMZN) is the rival for shopping budgets. Its advertising revenue grew 26% to $19.8 billion in Q2, fueled by sponsored products and AI shopping tools. Visual Search Ads aim straight at that spending, where shoppers are close to buying. Winning even a sliver of those budgets would matter for a $10.5 billion company.
Snap is the closest peer on size. Its Q2 revenue grew 19% to $1.60 billion, slightly faster than Pinterest. But Snap posted a negative 5.1% operating margin over the past 12 months and carries $1.57 billion of net debt. Pinterest, by contrast, holds a small net cash position.

Valuation puts Pinterest in an unusual spot. It trades at 8.5x forward earnings and 6.8x forward EV/EBITDA, below Snap’s 7.2x on cash profit. Gross margin of 79.5% also tops Snap’s 57.3%. So Pinterest pairs stronger economics with a discount multiple, which the model reads as mispricing.
Pinpoint if stronger monetization and AI tools can support the $28 target >>>
What’s Driving PINS Stock Going Forward?

Q3 results on November 5 will test the slower guidance. Management expects revenue of $1.19 billion to $1.21 billion and adjusted EBITDA of $335 million to $355 million. A beat would suggest the World Cup and Prime Day effects were smaller than feared. But a miss would reinforce the market’s skepticism.
Visual Search Ads enter beta across all Pinterest ad markets in the coming weeks. The format works with Performance+, Pinterest’s automated ad buying suite. Early advertiser adoption is the key signal, since Pinterest has not published performance data yet. Holiday shopping season gives the launch a natural test.
The CFO search adds near-term uncertainty. Pinterest has begun an external search but has not set a successor timeline. No accounting or control issue has surfaced alongside the departure. Still, investors will want continuity on buybacks and margin targets.
Index changes have also reshaped the shareholder base. In June, Pinterest moved from Russell growth benchmarks into the Russell 2500 Value index. That shift shows how far the multiple has fallen. Going forward, steady double-digit growth could win back growth investors and lift the valuation.
Rank ad-driven stocks by forward P/E and see where Pinterest lands (Free with TIKR) >>>
What is Pinterest stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Pinterest could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use. Value PINS for free.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!