Key Takeaways:
- Agentic Commerce: Mastercard launched Agent Pay for Machines, the only network protocol enabling AI agents to make purchases at machine speed, opening a new addressable market.
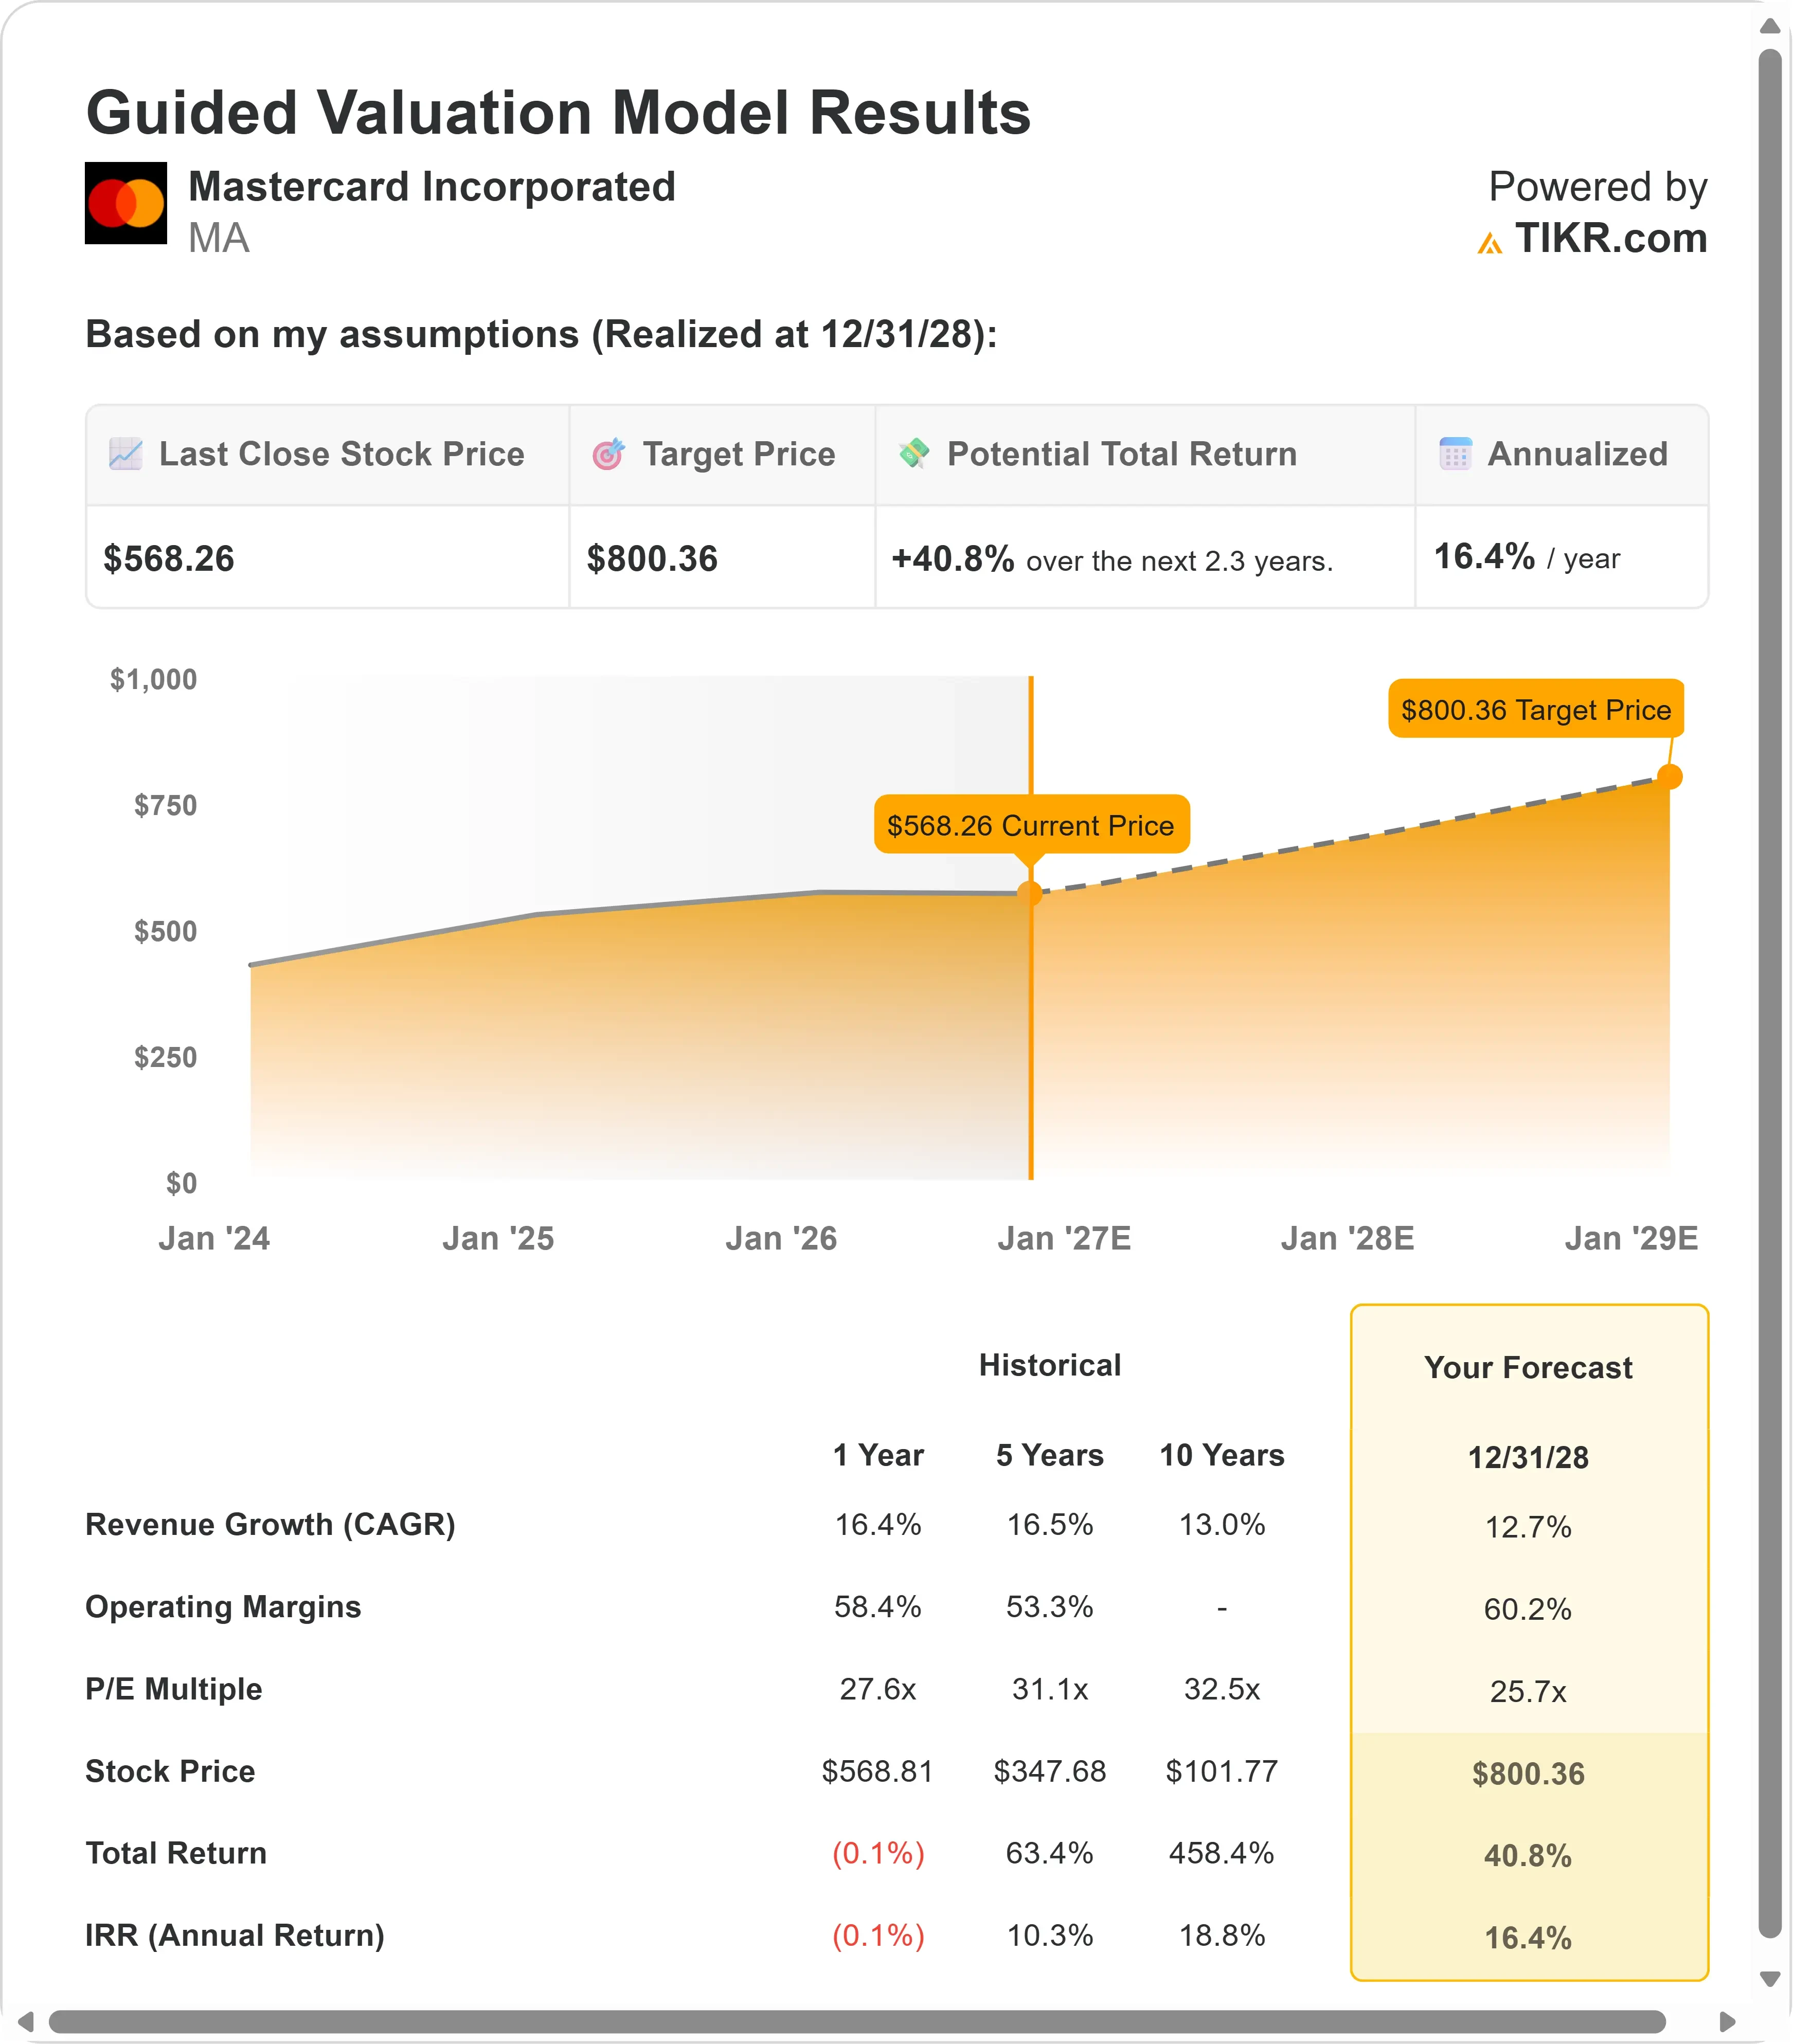
- Price Projection: Based on current assumptions, MA stock could reach $800 by December 2028.
- Potential Gains: This target implies a total return of 41% from the current price of $568.
- Annual Return: Investors could see roughly 16% annual growth over the next 2.3 years.
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free)>>>
Mastercard (MA) delivered a strong Q2, with net revenue up 12% and adjusted net income up 16%, both ahead of expectations.
Value-added services, the company’s fastest-growing segment, grew net revenue 18% year-over-year.
CEO Michael Miebach pointed to a mix of secular tailwinds and disciplined execution behind the results, even as the company navigates a leadership transition with CFO Sachin Mehra moving to a new role and Ling Hai stepping in.
- Worldwide gross dollar volume grew 8% year-over-year, while cross-border volume, a high-margin business, grew 12%.
- The company added over 230 million net new Mastercard-branded cards into the market over the trailing 12 months.
- Switched transactions grew 9%, with token penetration now above 40% of all switched transactions.
Despite the strong quarter, shares are roughly flat over the past year, leaving room for the stock to catch up with underlying business growth.
See analysts’ full growth forecasts and estimates for MA stock (It’s free) >>>
What the Model Says for Mastercard Stock
Mastercard’s growth rests on a simple idea: only about a third of consumer transactions globally are carded today, and commercial payments have even further to go.
The company is chasing that gap through partnerships, government disbursement programs, and new payment rails.
Security has become a particularly strong growth driver.
Mastercard’s Threat Intelligence product identified more than 7 million card testing transactions across 192 countries in its first three quarters, preventing an estimated $172 million in fraud.
Management described cybersecurity as now sitting at the center of boardroom conversations, giving Mastercard a natural entry point to sell more services into existing relationships.
The company is also positioning early for how payments evolve. Its Agent Pay platform lets AI agents make purchases on a consumer’s behalf using existing card infrastructure, while Agent Pay for Machines targets an entirely new category: machine-to-machine payments for things like API calls and compute.
Alongside this, Mastercard continues building out stablecoin capabilities, including its pending acquisition of BVNK, expected to close in Q3, which will let customers move between different digital assets and fiat currency.
Our Valuation Assumptions
Estimate a company’s fair value instantly (Free with TIKR) >>>
Our Valuation Assumptions
TIKR’s Valuation Model lets you plug in your own assumptions for a company’s revenue growth, operating margins, and P/E multiple, and calculates the stock’s expected returns.
Here’s what we used for Mastercard stock:
1. Revenue Growth: 12.7%
This is a touch below Mastercard’s 2025 full-year growth of 16.4%, and close to its ten-year average of 13%.
Management guided net revenue growth to the high end of the low double-digit range for the full year, so this assumption aligns with that outlook rather than extrapolating the recent acceleration in value-added services.
2. Operating margins: 60.2%
Mastercard’s operating margin for 2025 full year already sits at 59.2%, among the highest of any large-cap company.
The model assumes modest further expansion, supported by the growing share of value-added services revenue that’s network-linked, which carries strong incremental margins as it scales alongside the core payment network.
3. Exit P/E Multiple: 25.7x
Mastercard trades at 26.7x forward earnings today, well below its longer-term averages of 30x-plus over the past three, five, and ten years.
The model assumes slight compression to 25.7x, treating the current discount as roughly where the stock settles rather than assuming a snap-back to historical premium levels.
Based on these inputs, TIKR’s model projects MA could reach $800 per share by the end of 2028, a 41% total return, or about 16% annualized.
Build your own Valuation Model to value any stock (It’s free!) >>>
What Happens If Things Go Better or Worse?
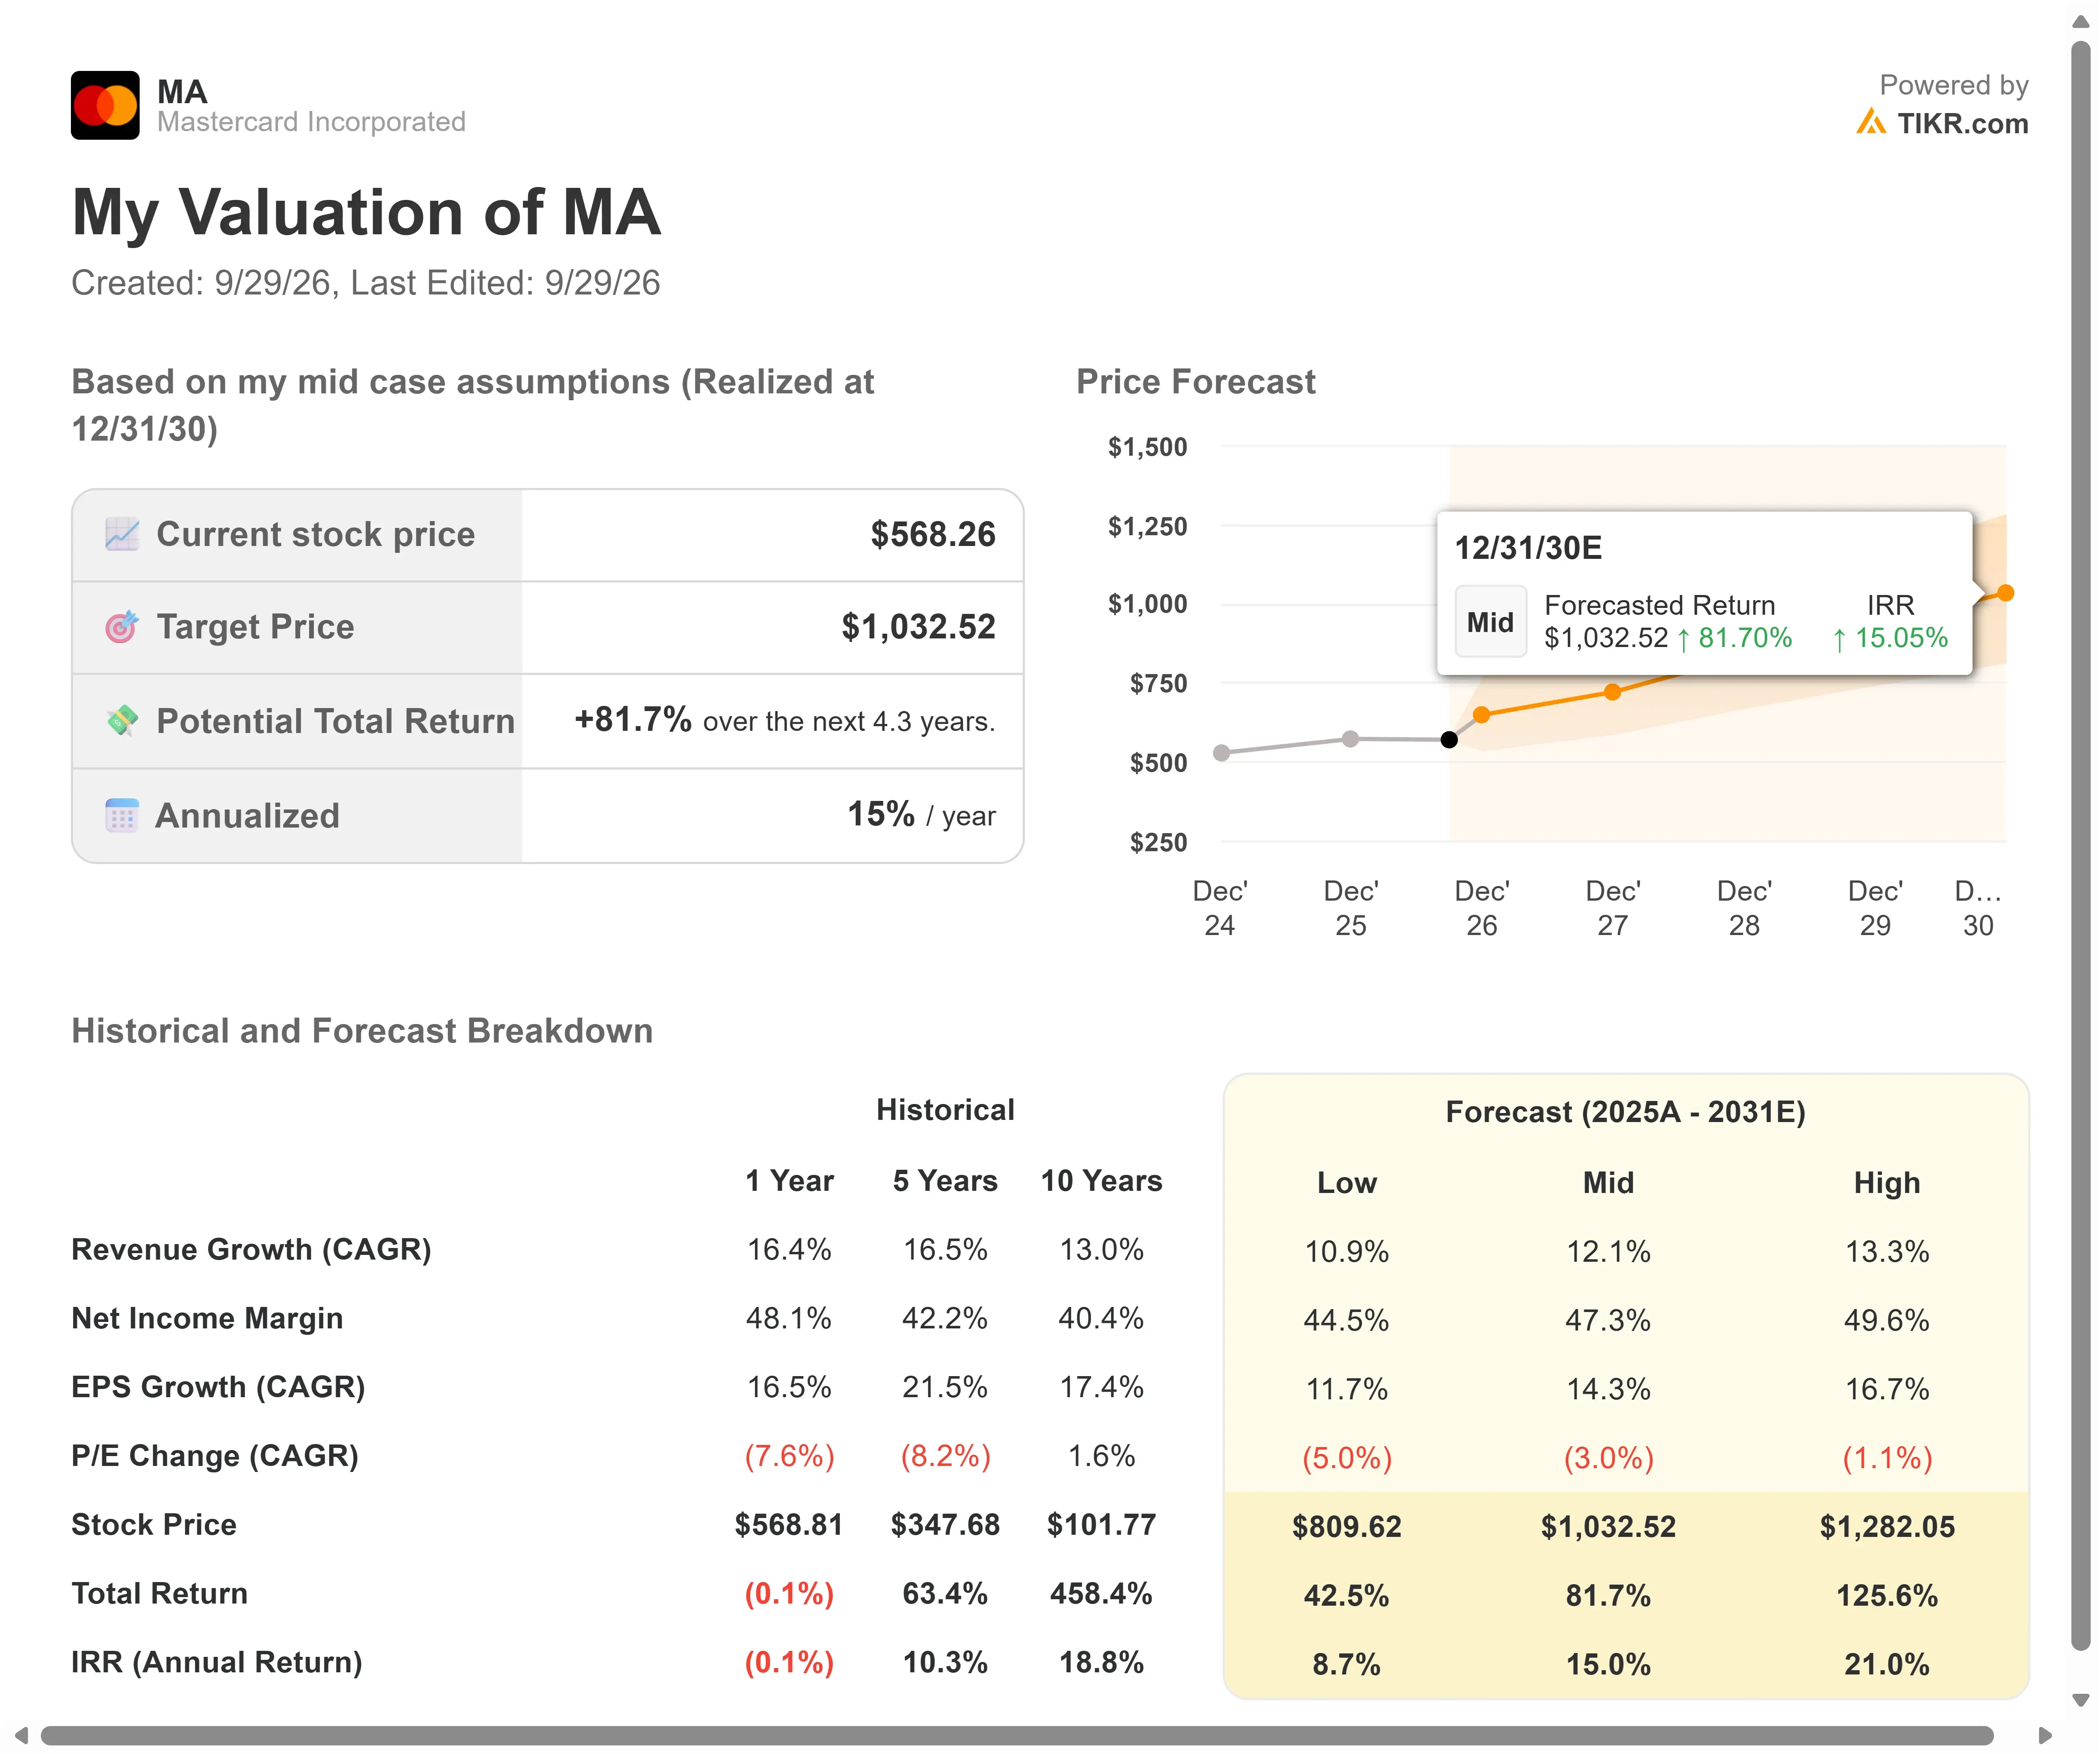
Mastercard operates a globally diversified business, but currency swings, geopolitical disruptions, and competitive dynamics in payments can still move results. Here’s how MA stock might perform under different scenarios through December 2030:
- Low Case: If revenue growth slows to 10.9% and net income margins reach 44.5%, investors could still see a 42.5% total return, or 8.7% annually.
- Mid Case: With 12.1% growth and 47.3% margins, the total return comes to 81.7%, or 15% annually.
- High Case: If growth accelerates to 13.3% with margins at 49.6%, returns could hit 125.6% total, or 21% annually.
See what analysts think about MA stock right now (Free with TIKR) >>>
The range largely reflects how quickly new growth areas like agentic commerce, stablecoins, and expanded switching partnerships convert into meaningful revenue alongside Mastercard’s already mature core payments business.
How Much Upside Does Mastercard Stock Have From Here?
With TIKR’s new Valuation Model tool, you can estimate a stock’s potential share price in under a minute.
All it takes is three simple inputs:
- Revenue Growth
- Operating Margins
- Exit P/E Multiple
If you’re not sure what to enter, TIKR automatically fills in each input using analysts’ consensus estimates, giving you a quick, reliable starting point.
From there, TIKR calculates the potential share price and total returns under Bull, Base, and Bear scenarios so you can quickly see whether a stock looks undervalued or overvalued.
See a stock’s true value in under 60 seconds (Free with TIKR) >>>
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!