Key Stats for ROKU Stock
- Past 2 weeks performance: -2.9%
- 52-week range: $79 to $160
- Valuation model target price: $170
- Implied upside: 11.5% over 2.2 years
Size up what Roku is worth without Fox using 5 years of consensus forecasts (It’s free) >>>
Fox’s Offer Now Sets the Ceiling for Roku
Roku (ROKU) shares slipped 2.9% over the past 2 weeks and now trade near $153. The streaming platform has nearly doubled from its 52-week low of $79. Yet the stock now moves on its pending sale to Fox Corporation more than on results. In short, investors treat it as a merger bet.
Roku holders would receive $96 in cash plus 0.9693 Fox shares for each Roku share. That package carried an initial value of about $160 per share. In September, the Department of Justice issued a second request, a formal demand for more data in an antitrust review. This extends the timeline, although Fox still expects closing in H1 2027.
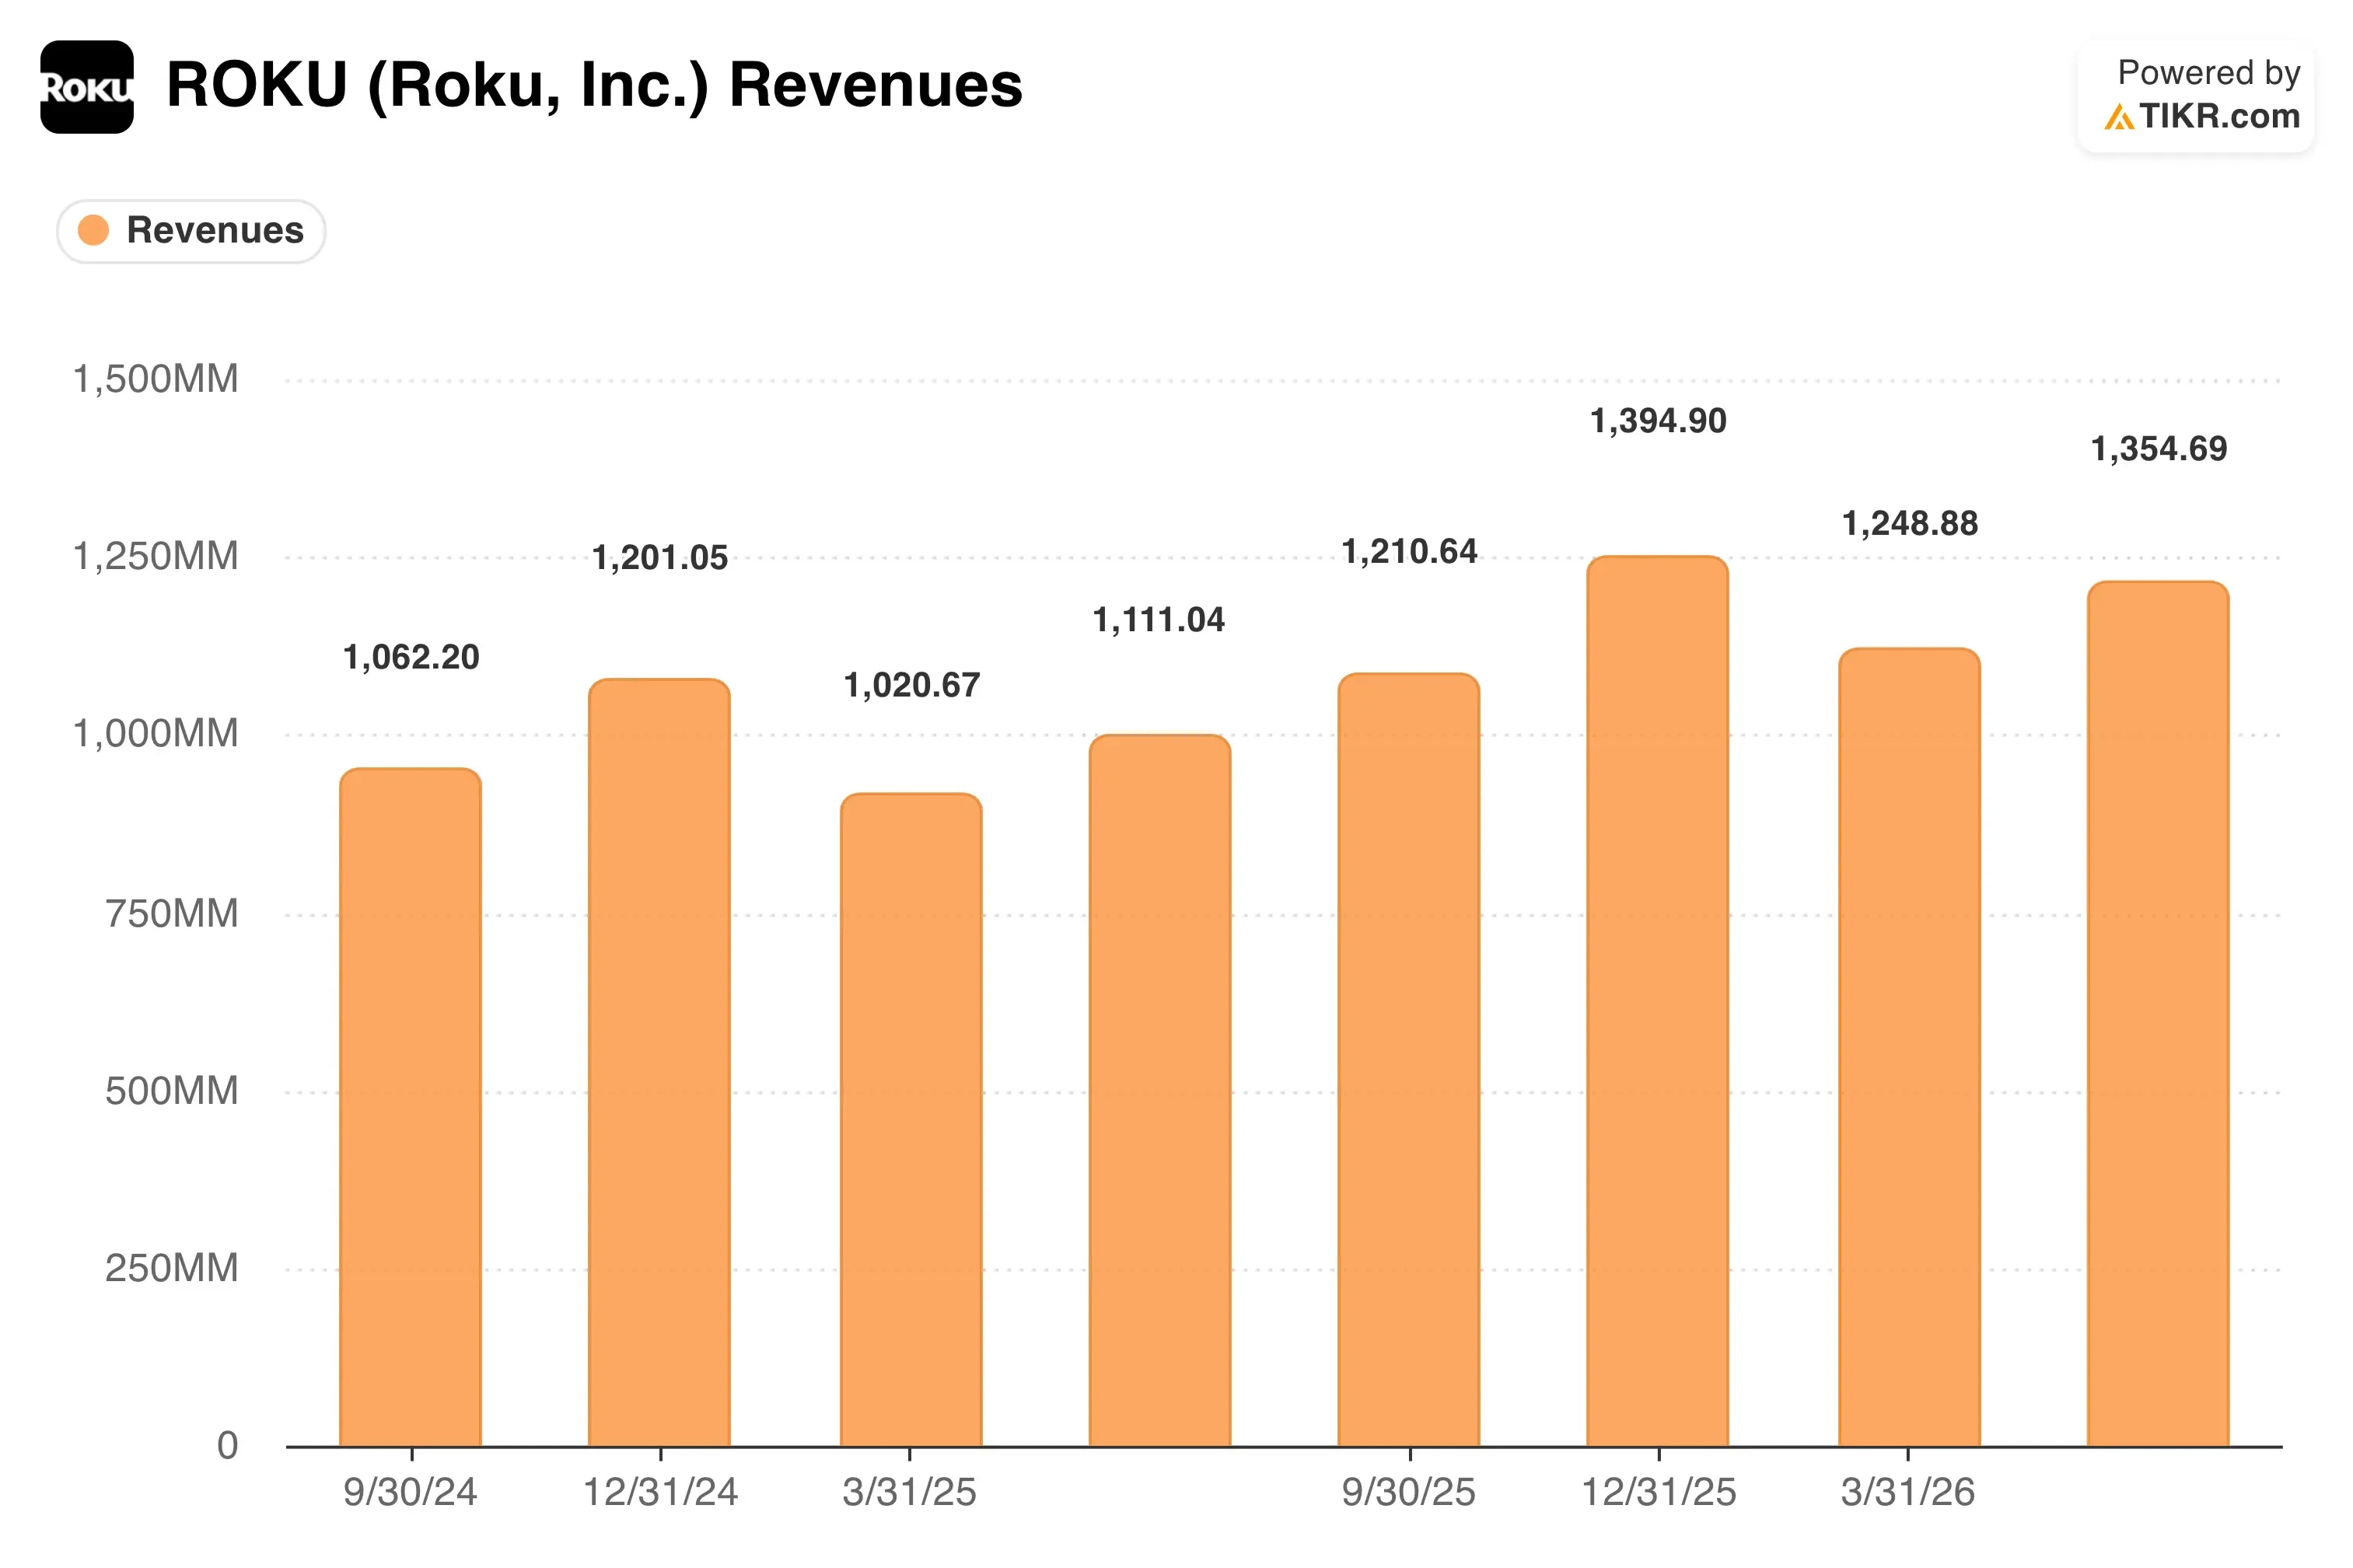
Meanwhile, the operating business keeps delivering. Q2 revenue rose 22% to $1.35 billion, while platform revenue from ads and subscriptions jumped 25% to $1.22 billion. Net income reached $164 million versus $10.5 million a year earlier. Because of the deal, Roku skipped its earnings call and stopped giving guidance.
Management made its case in the Q2 shareholder letter instead. CEO Anthony Wood and CFO Dan Jedda called the deal “an extraordinary opportunity to accelerate our vision.” Shareholders vote on the merger on October 14. If ROKU stock holds near $153, the market is pricing in modest risk that the deal slips or changes.
Follow Roku’s ARR acceleration quarter by quarter with free analyst estimates (It’s free) >>>
A Rich Multiple Leaves Roku Little Room to Run
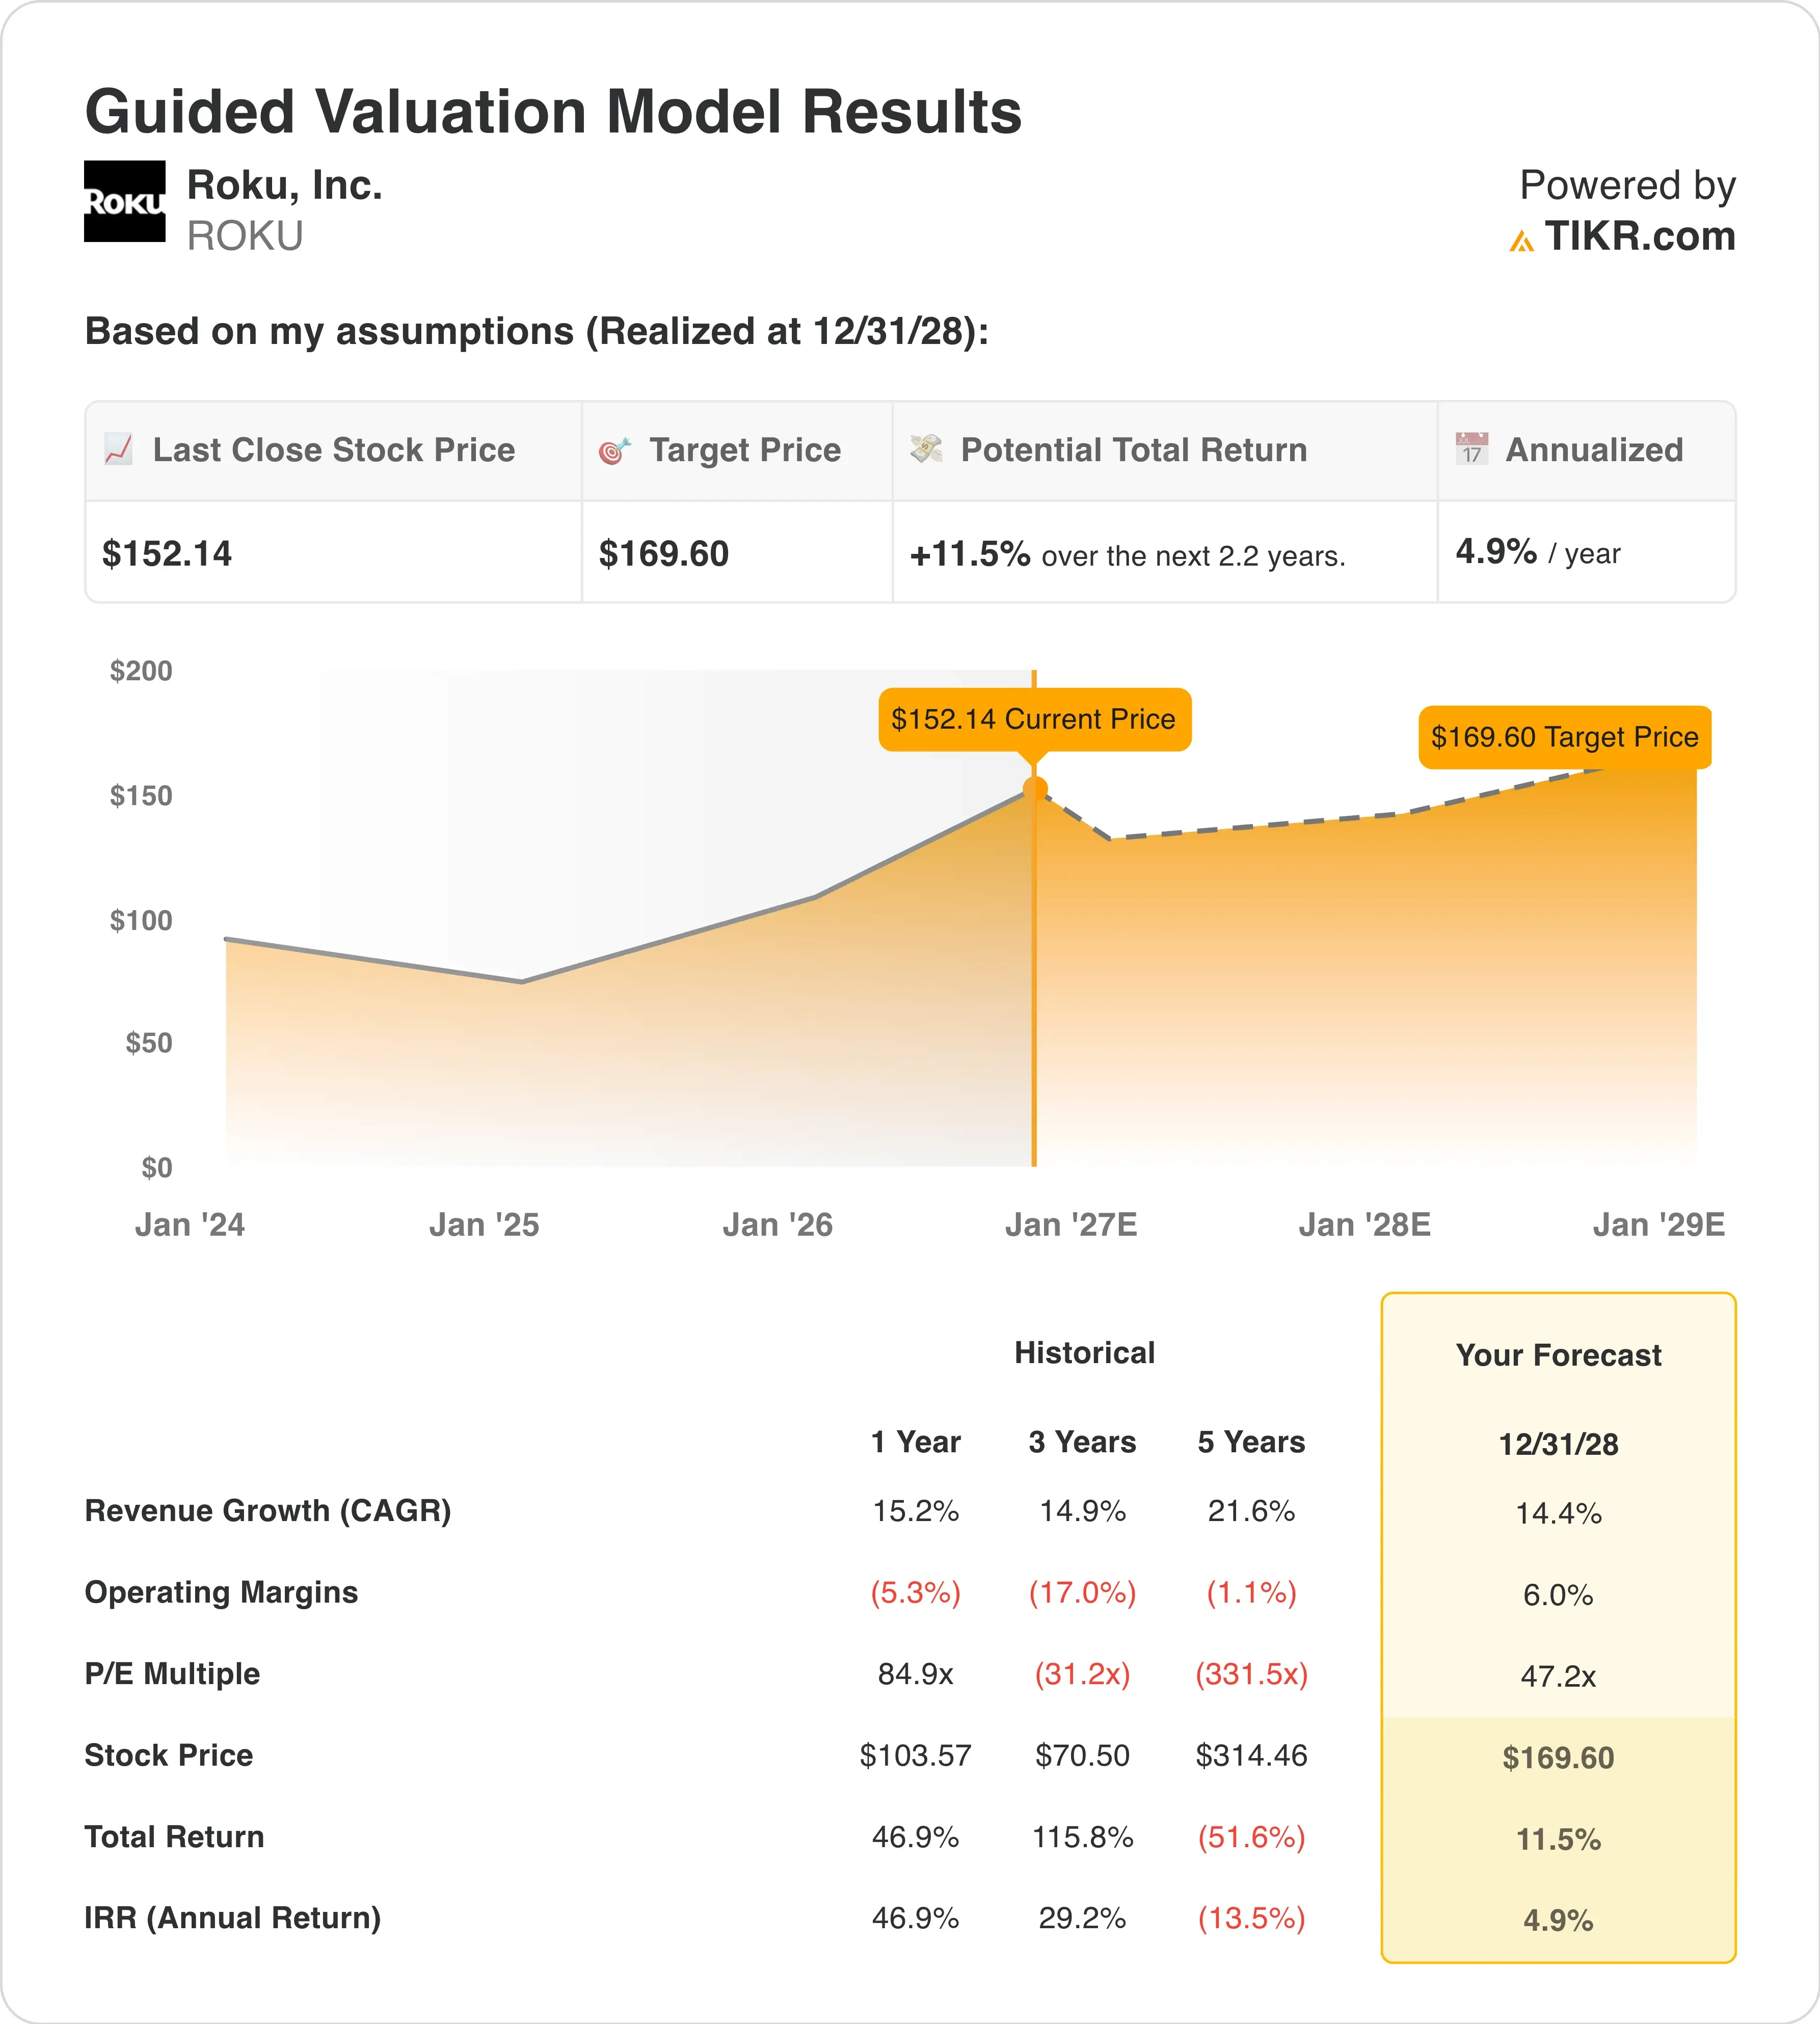
Under valuation model assumptions realized through 12/31/28, the stock is modeled using:
- Revenue Growth (CAGR): 14.4%
- Operating Margins: 6.0%
- Exit P/E Multiple: 47.2x
Based on these inputs, the model estimates a target price of $170. This implies an 11.5% total return from the $152 share price and a 4.9% annualized return over 2.2 years.
Such a return sits below the 5% level that signals limited upside. So Roku looks fully valued on a standalone basis after its big run. The stock already trades above 47x next year’s expected earnings. Instead of assuming expansion, the model simply holds that multiple steady.
Revenue assumptions look reasonable. The model uses 14.4% annual growth, close to Roku’s 14.9% pace over the past 3 years. Platform revenue drives that growth because ads and subscriptions carry higher margins than devices. Roku also said its redesigned home screen improved household retention in the U.S.
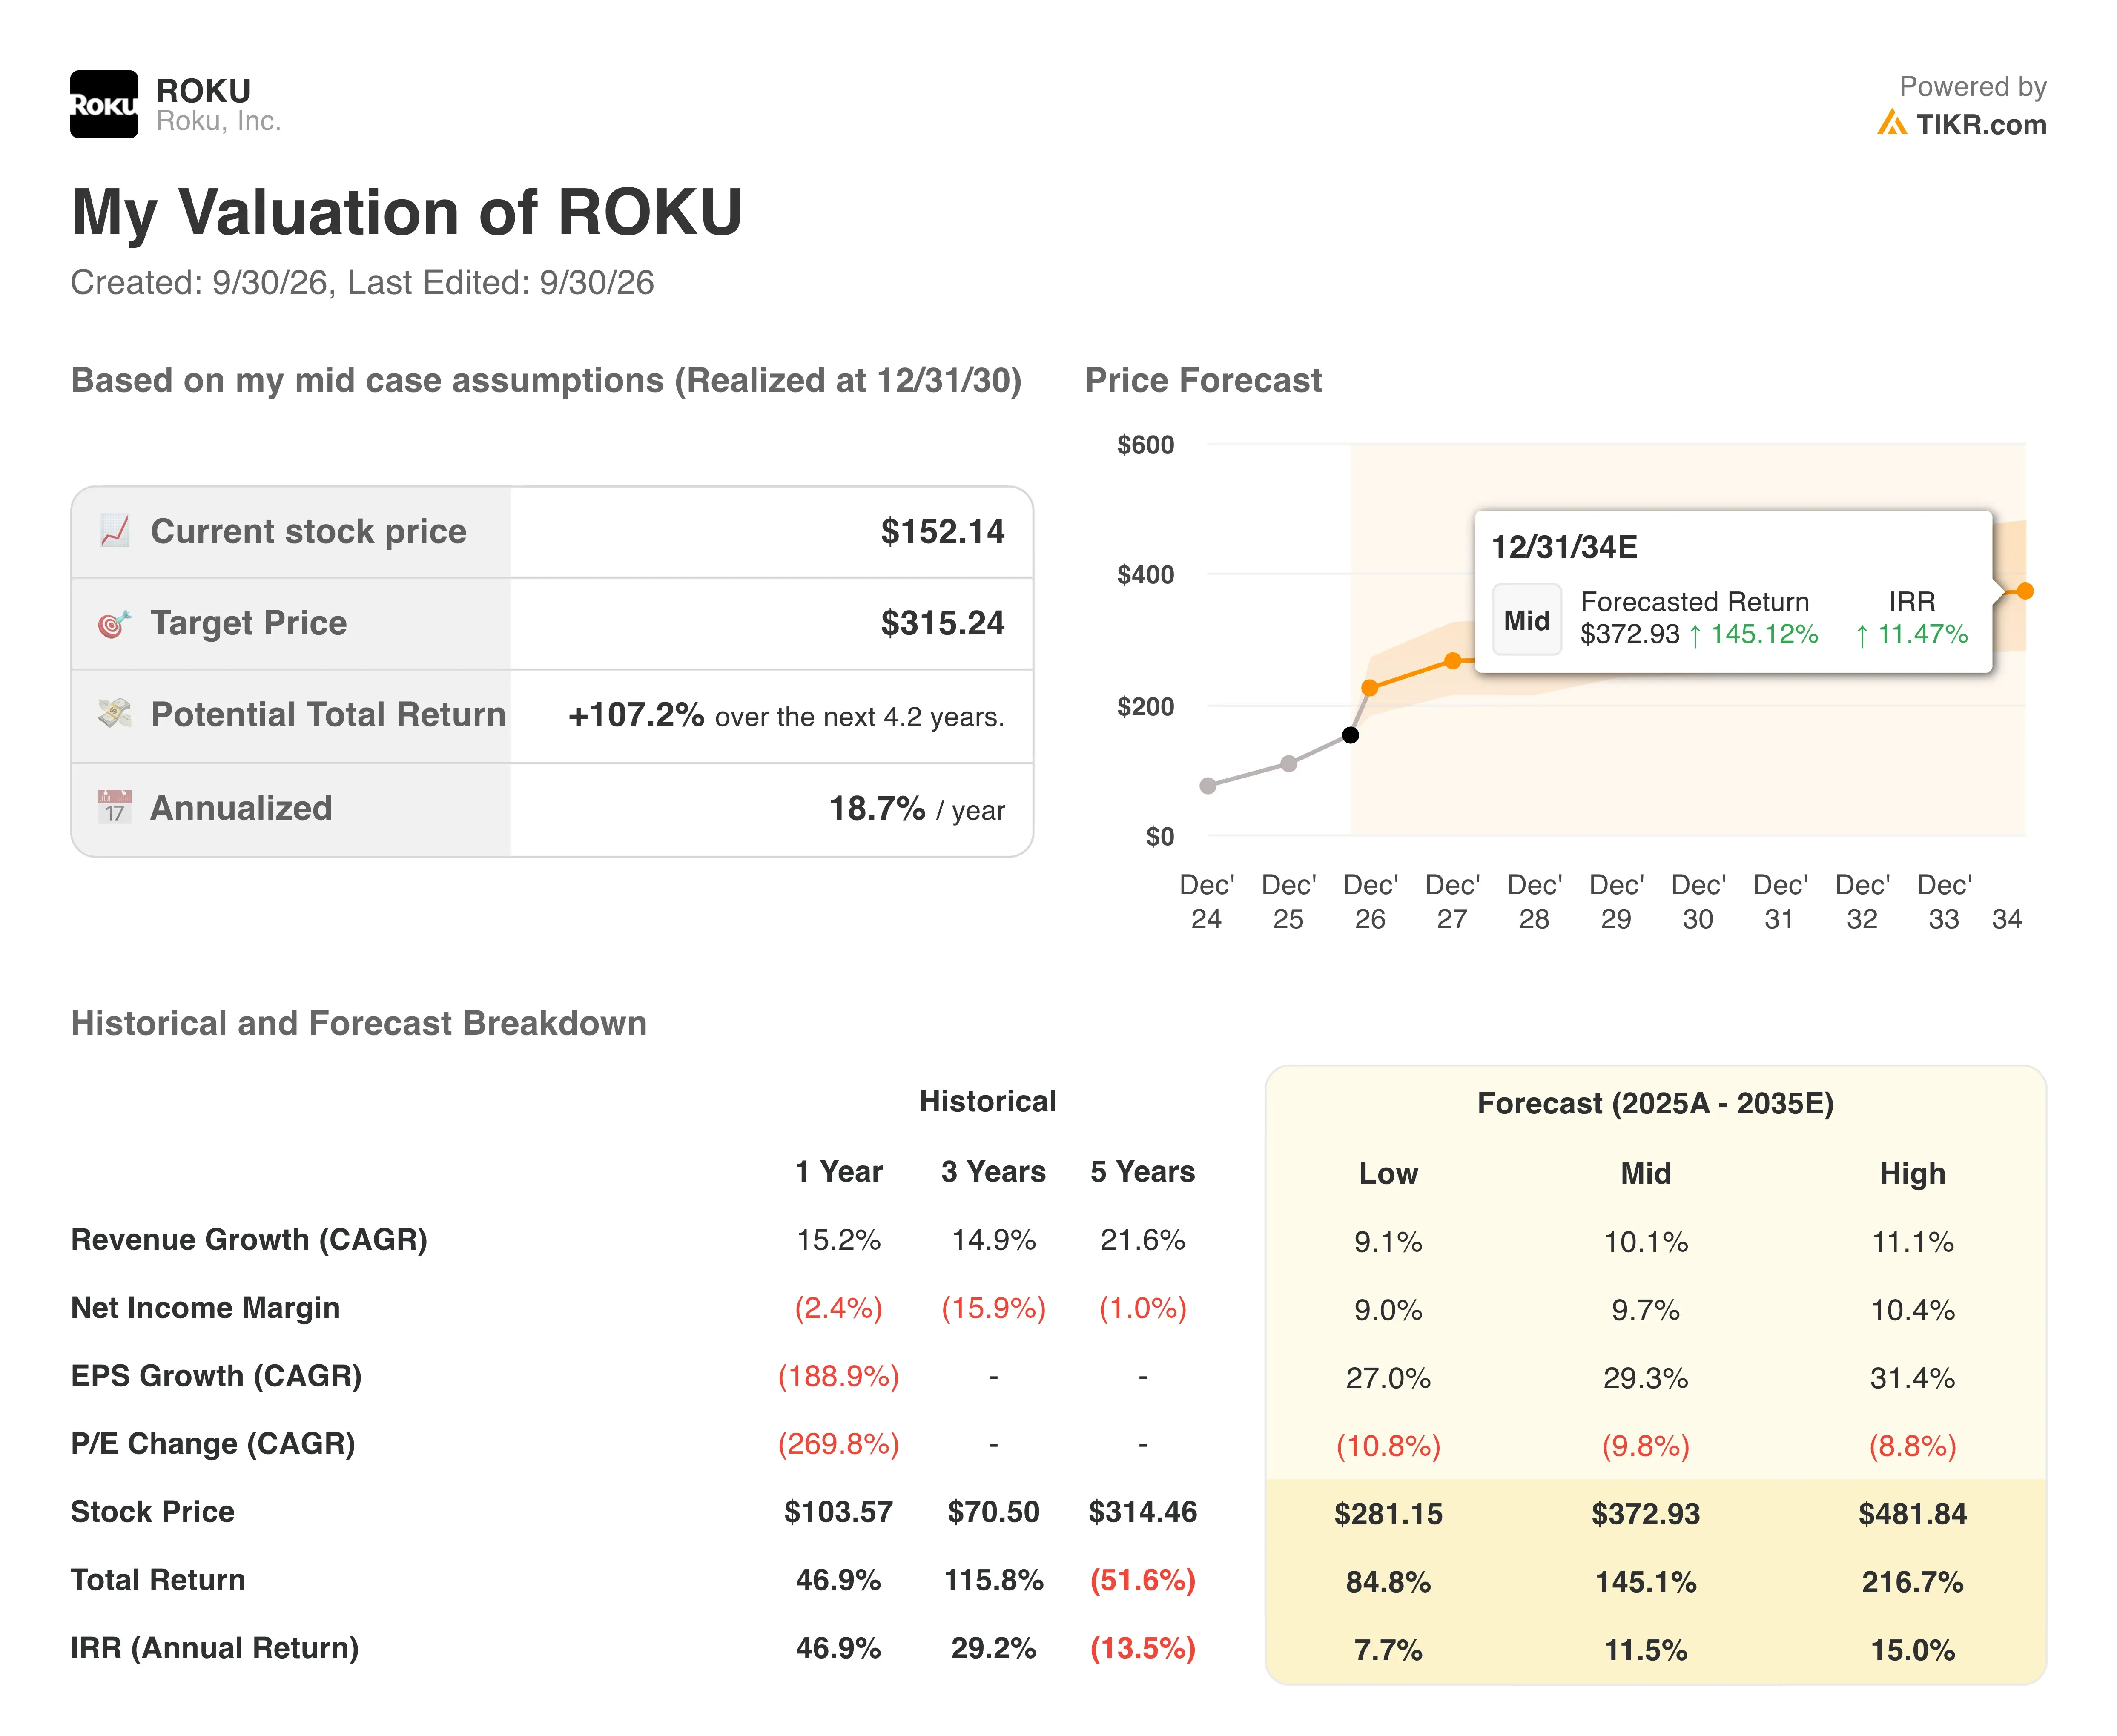
Margins tell a recovery story. Roku’s operating margin averaged negative 17.0% over 3 years but turned positive at 5.8% over the last 12 months. The model asks for 6.0% by 2028, only a small step up. Before the deal, Roku targeted $1 billion in free cash flow by 2028, which hints at more upside.
Roku also carries a richer earnings multiple than larger rivals Amazon (AMZN) and Alphabet (GOOGL). Meanwhile, the deal value limits how far shares can climb before closing. Wall Street’s average target of $162 sits just above today’s price. That tight gap shows how firmly Fox’s offer anchors expectations.
Challenge Roku’s 47x earnings multiple with your own growth and margin inputs (Free with TIKR) >>>
Roku Is Matching Big Tech on Ad Growth
Amazon (AMZN) is Roku’s toughest rival, thanks to Fire TV devices and Prime Video ads. Amazon’s advertising revenue grew 26% to $19.8 billion in Q2. Over the same quarter, Roku’s advertising revenue rose 25% to $673 million. So the smaller player is keeping pace with a giant on growth.
Alphabet (GOOGL) competes through Google TV and YouTube. YouTube ad revenue grew 13% to about $11.1 billion in Q2. Roku nearly doubled that growth rate, helped by NBA playoff and World Cup viewing. Streaming hours on Roku also rose 7% to 37.9 billion.
Subscriptions give Roku another lever. Subscription revenue climbed 26% to $548 million, since Roku sells access to dozens of streaming services. That model earns Roku a cut without paying for most of the content. Roku markets itself as an open, partner-friendly platform, and Fox has pledged to keep it that way.
Scale remains the main gap. Roku reaches more than 100 million streaming households, including over half of U.S. broadband homes. Yet its $22.6 billion market value is tiny next to its tech rivals. Fox’s sports content and Tubi service would add the premium inventory advertisers want.
Measure if platform monetization and 100 million households can support the $142 target >>>
What’s Driving ROKU Stock Going Forward?
The DOJ review is now the main event. Roku and Fox must substantially comply with the second request before the waiting period restarts. So far, regulators have not announced a challenge or any required asset sale. But any hint of remedies could widen the gap between Roku’s price and the offer.
Fox’s own share price also matters. The $96 cash portion is fixed, while the rest moves with Fox stock. If Fox shares rise, the deal becomes worth more to Roku holders. Conversely, a Fox selloff would drag Roku lower even if its business keeps growing.
Shareholders vote at a special meeting on October 14. Q3 results follow around November 3, likely without guidance or a call again. Strong numbers would mostly reassure investors about downside if the deal fails.
Industry trends support the standalone case. Roku research found Canadian daily streamers spend nearly 80 hours a year choosing what to watch. That friction makes Roku’s home screen and search tools more valuable to advertisers. Going forward, those strengths give Roku a solid fallback if regulators block the Fox deal.
Run Roku’s bull, base, and bear cases in under 60 seconds (Free with TIKR) >>>
What is Roku stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Roku could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use. Value ROKU for free.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!