Key Takeaways
- Record Print: Q4 revenue hit a record $54.23B (up 379% YoY) on an 87-= % gross margin, producing non-GAAP diluted EPS of $33.42 against $3.03 a year ago.
- Next-Quarter Guide: A $60B to $63B revenue guide for Q1 FY27 sits beside EPS of $38.15 ± $1.00, a 13% sequential step at the revenue midpoint.
- Data Center Surge: Core Data Center revenue rose 56% QoQ to $18.0B.
- CFO Margin Floor: CFO Mark Murphy called Q1 FY27’s ~86% gross margin the floor for the year, with higher margins expected after.
A record 87% gross margin, yet management guides the next quarter lower. Compare Micron’s margin history against its guidance on TIKR for free →
Micron Posts an 87% Gross Margin and Guides Higher as Price Gains Slow
Micron Technology (MU) posted fiscal Q4 2026 revenue of $54.23 billion on September 30, up 31% from the prior quarter and 379% from a year earlier. Micron stock now stands on quarterly non-GAAP diluted earnings per share of $33.42, against $3.03 twelve months ago.
Price did the work. DRAM average selling prices (ASPs) rose in the high-teens percent range from the prior quarter and NAND ASPs rose approximately 30%, against bit shipment growth of a mid-single-digit percentage in DRAM and approximately 10% in NAND. That pricing power carried gross margin to 87% and operating income to $44.64 billion.
The Core Data Center Business Unit captured the sharpest move: revenue jumped 56% sequentially to a record $18.0 billion at a 90% gross margin, while data center solid-state drive (SSD) revenue alone reached nearly $10 billion, more than 10 times the year-ago quarter.
Management guided fiscal Q1 2027 revenue to $60 billion to $63 billion and EPS to $38.15 plus or minus $1.00, yet it pointed gross margin down to 86%. Higher-cost inventory explains the dip, because Micron absorbed most of its fiscal 2026 manufacturing incentive compensation increase into inventory in Q4, and those costs flow through the income statement in Q1. CFO Mark Murphy set the marker on the Q4 earnings call: “We anticipate fiscal Q1 to be the floor for gross margins in fiscal 2027.” Margins rise from that base through the rest of the year, he said, though price increases will arrive at a slower pace.
Contracted demand backs the guide. Micron has signed 26 strategic customer agreements (SCAs), multi-year take-or-pay contracts that it estimates will cover over 35% of revenue through 2030, and customer financial commitments under them have grown to $32 billion, the vast majority in cash deposits. Three-quarters of that revenue carries a defined pricing framework, most of it with floor and ceiling prices, which limits the swing in both directions.
With no line of sight to when DRAM supply and demand return to balance, management will lift fiscal 2027 capital spending above prior plans, mostly for construction that opens cleanroom space in late calendar 2028 and beyond. Q4 net capex already ran to $10.77 billion, and adjusted free cash flow of $33.20 billion covered it three times over.
What does $32 billion in customer commitments do to Micron’s revenue visibility? Explore MU’s revenue and margin history on TIKR for free →
Analysts Flipped Their Micron Stock Target From 27% Below the Price to 42% Above
As of September 29, 36 analysts rate Micron stock a Buy and 9 more rate it an Outperform, against 3 Holds and 2 negative ratings (1 Underperform, 1 Sell).

The mean price target climbed from $674 on May 28 to $1,521, while the stock rose from $924 to $1,065 over the same stretch. That move turned a mean target sitting 27% below the price into one 42% above it. The 46 analysts setting targets span a low of $361 to a high of $2,200, with a median of $1,545.lok
TIKR Values Micron Stock at $1,489 by August 2030, a 40% Return
TIKR’s mid-case model values Micron stock at $1,489 by August 2030, implying a 40% total return from the current price of $1,065, or 9% annualized.
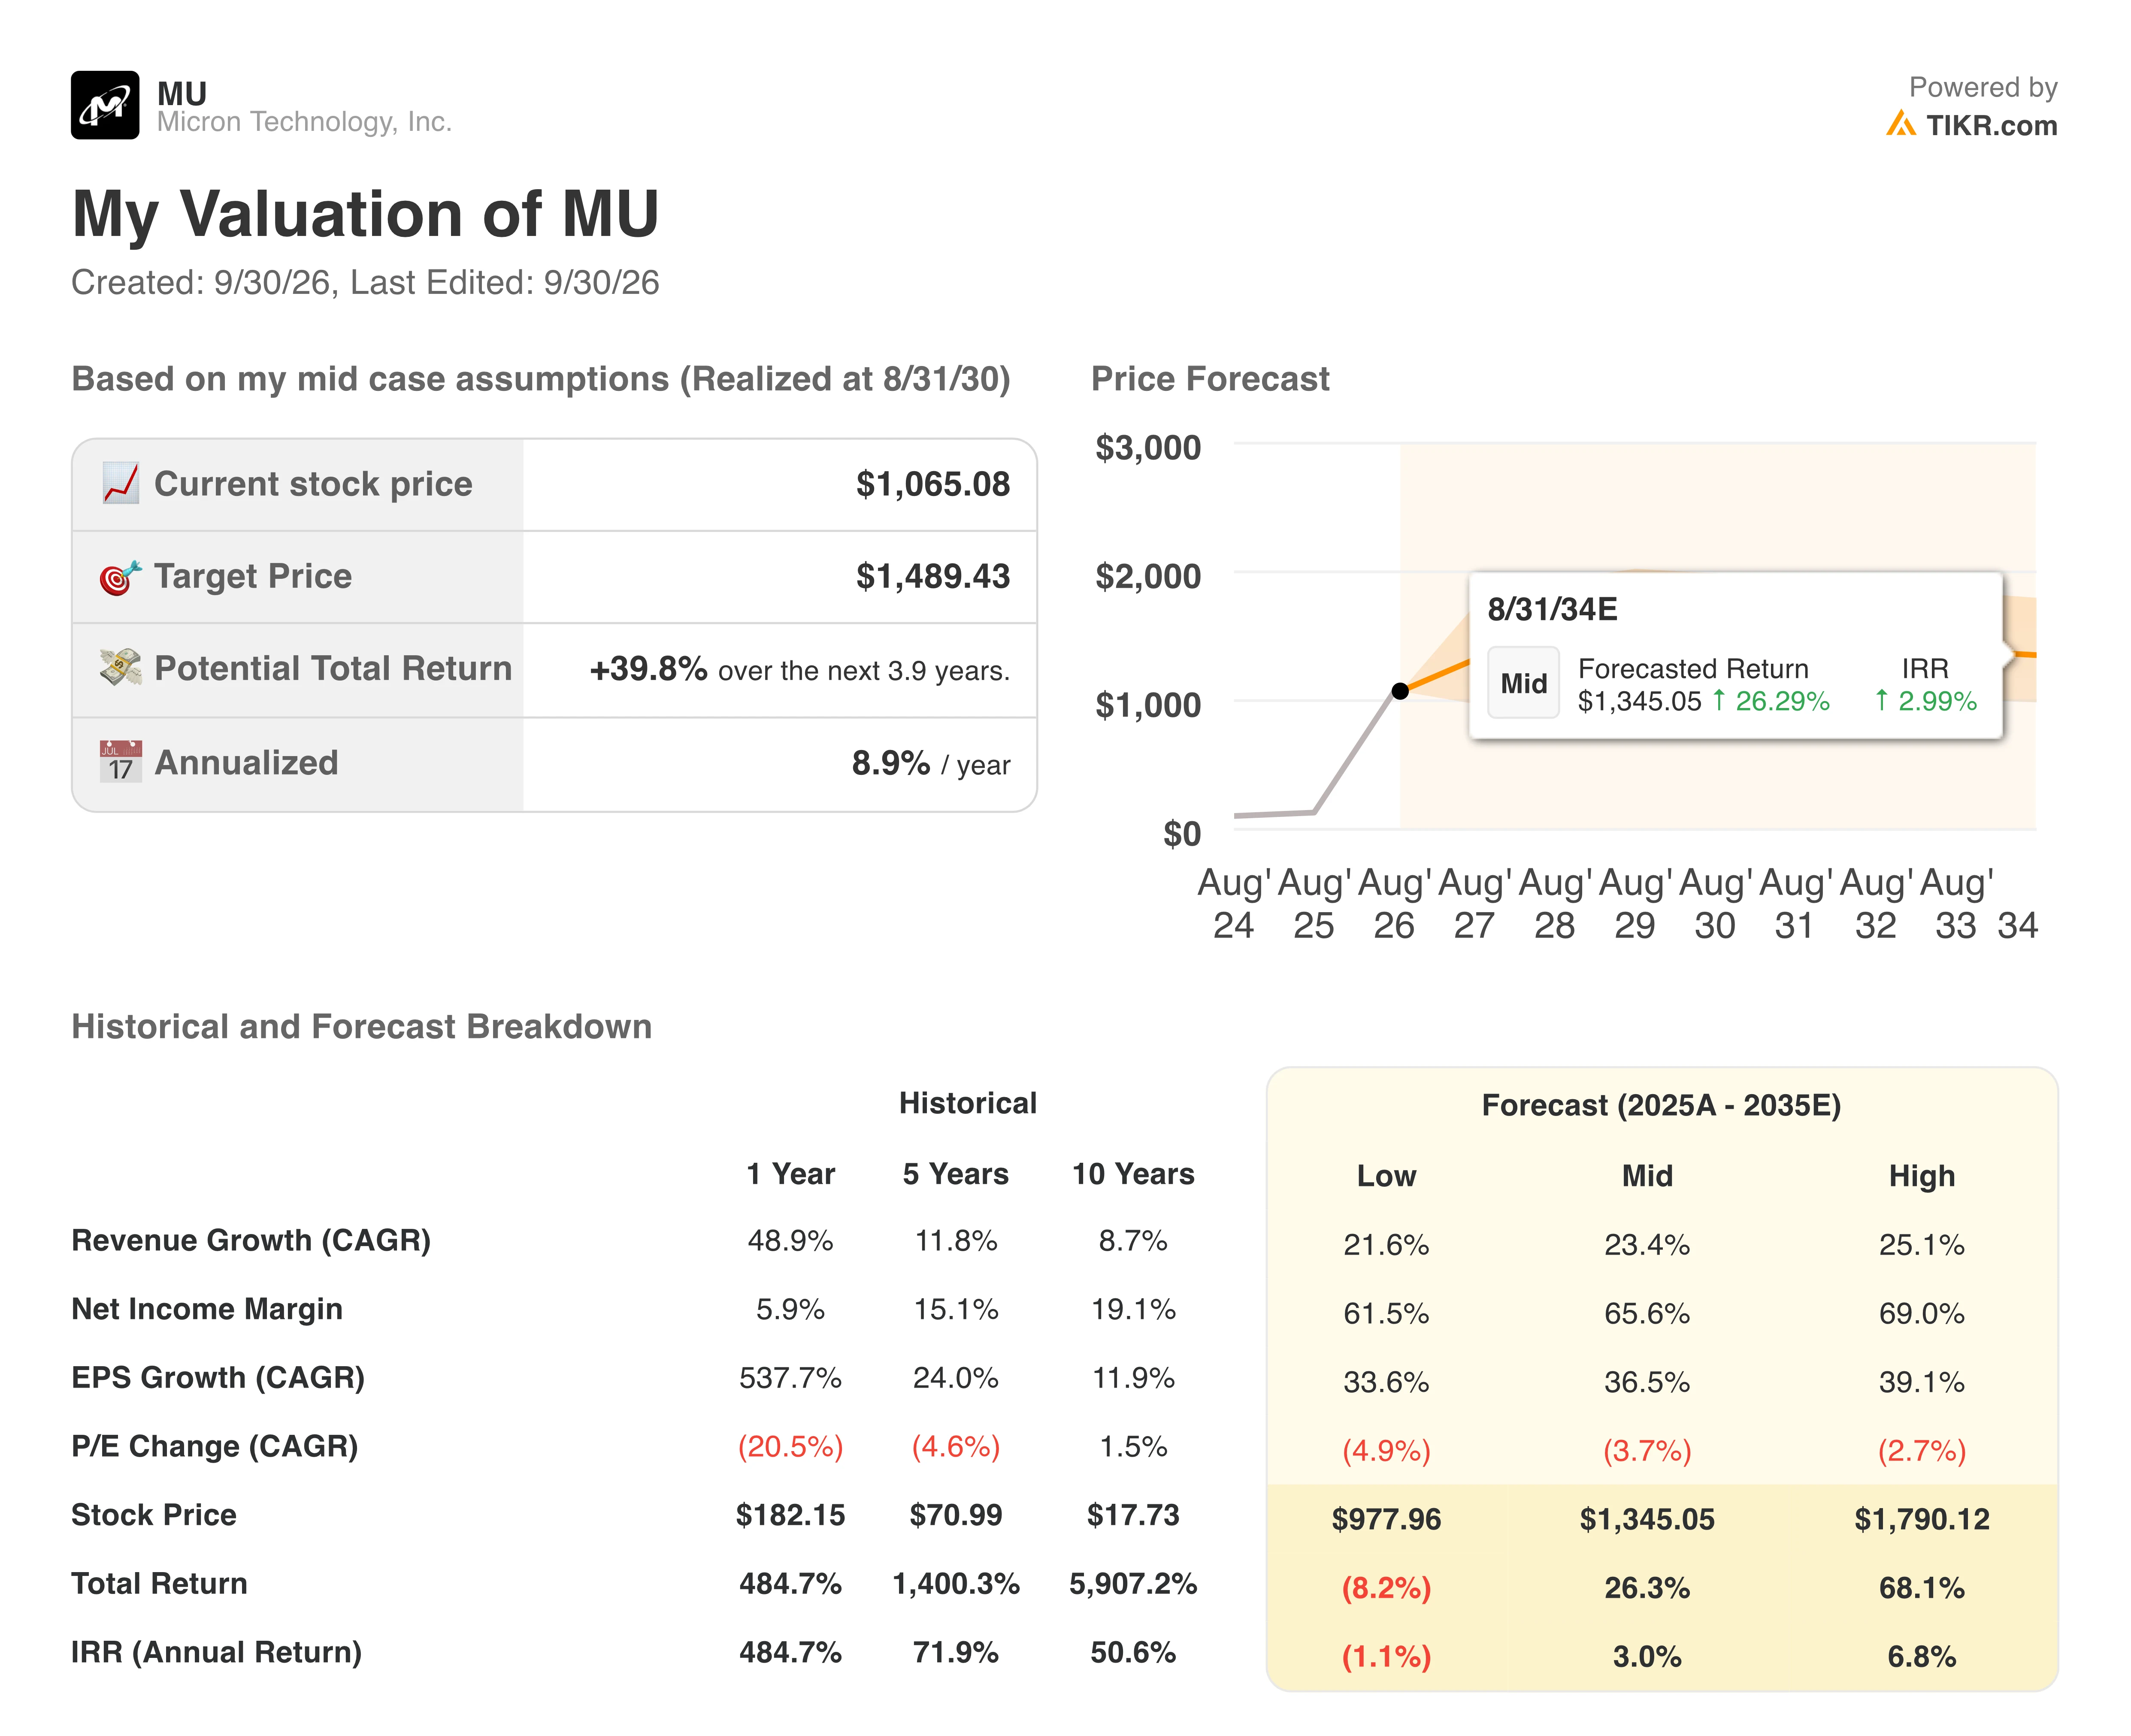
A 9% annualized rate lands near what broad equity markets have historically delivered, so the model prices Micron stock as a market-rate compounder even after a quarter that produced $33.42 of EPS.
The Q4 call supplies the support: a Q1 revenue guide of $60 billion to $63 billion and SCAs covering over 35% of revenue through 2030 give the forecast a contracted base. Management sees no line of sight to supply and demand balancing, which keeps the pricing behind that base in place.
TIKR’s mid-case model lands at $1,489 for Micron by August 2030, and you can rebuild it with your own inputs. Run your own MU valuation on TIKR for free →
So what is Micron Technology stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what MU stock could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Micron Technology for free→
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!