Key Takeaways
- Broadcom is reportedly raising $60 billion to fund chips for Anthropic, on top of a loan of up to $42 billion to lease Broadcom’s chips.
- That makes Broadcom both Anthropic’s chip supplier and its lender, so more of its growth now depends on a single customer.
- $60 billion of new debt alone would nearly double the $66.5 billion of total debt Broadcom carried at the end of fiscal 2025.
- Analysts expect revenue to rise from $63.9 billion in fiscal 2025 to $272 billion by fiscal 2028, and Anthropic’s IPO, reportedly as early as mid-November, is the next thing to watch.
Broadcom (AVGO) is all in on Anthropic.
Broadcom has started lining up $60 billion to finance chips for Anthropic, according to Bloomberg. That’s on top of a loan of up to $42 billion that Broadcom would provide to Anthropic to lease its chips, a deal TIKR covered earlier.
Put those two figures together, and you’re looking at $102 billion.
For some perspective, analysts expect Broadcom to generate about $106 billion in revenue during fiscal 2026, which ends in October.
So Broadcom is tying up an amount roughly equal to an entire year of revenue with a single customer.
The relationship has also changed. Broadcom is selling Anthropic the chips and helping finance those purchases, making Broadcom a lender to one of its largest AI customers.
Let’s talk about the debt
Broadcom’s total debt sat right around $40 billion from fiscal 2021 through 2023. It jumped to $68.9 billion in fiscal 2024 after the VMware deal and slipped to $66.5 billion in fiscal 2025, according to TIKR…
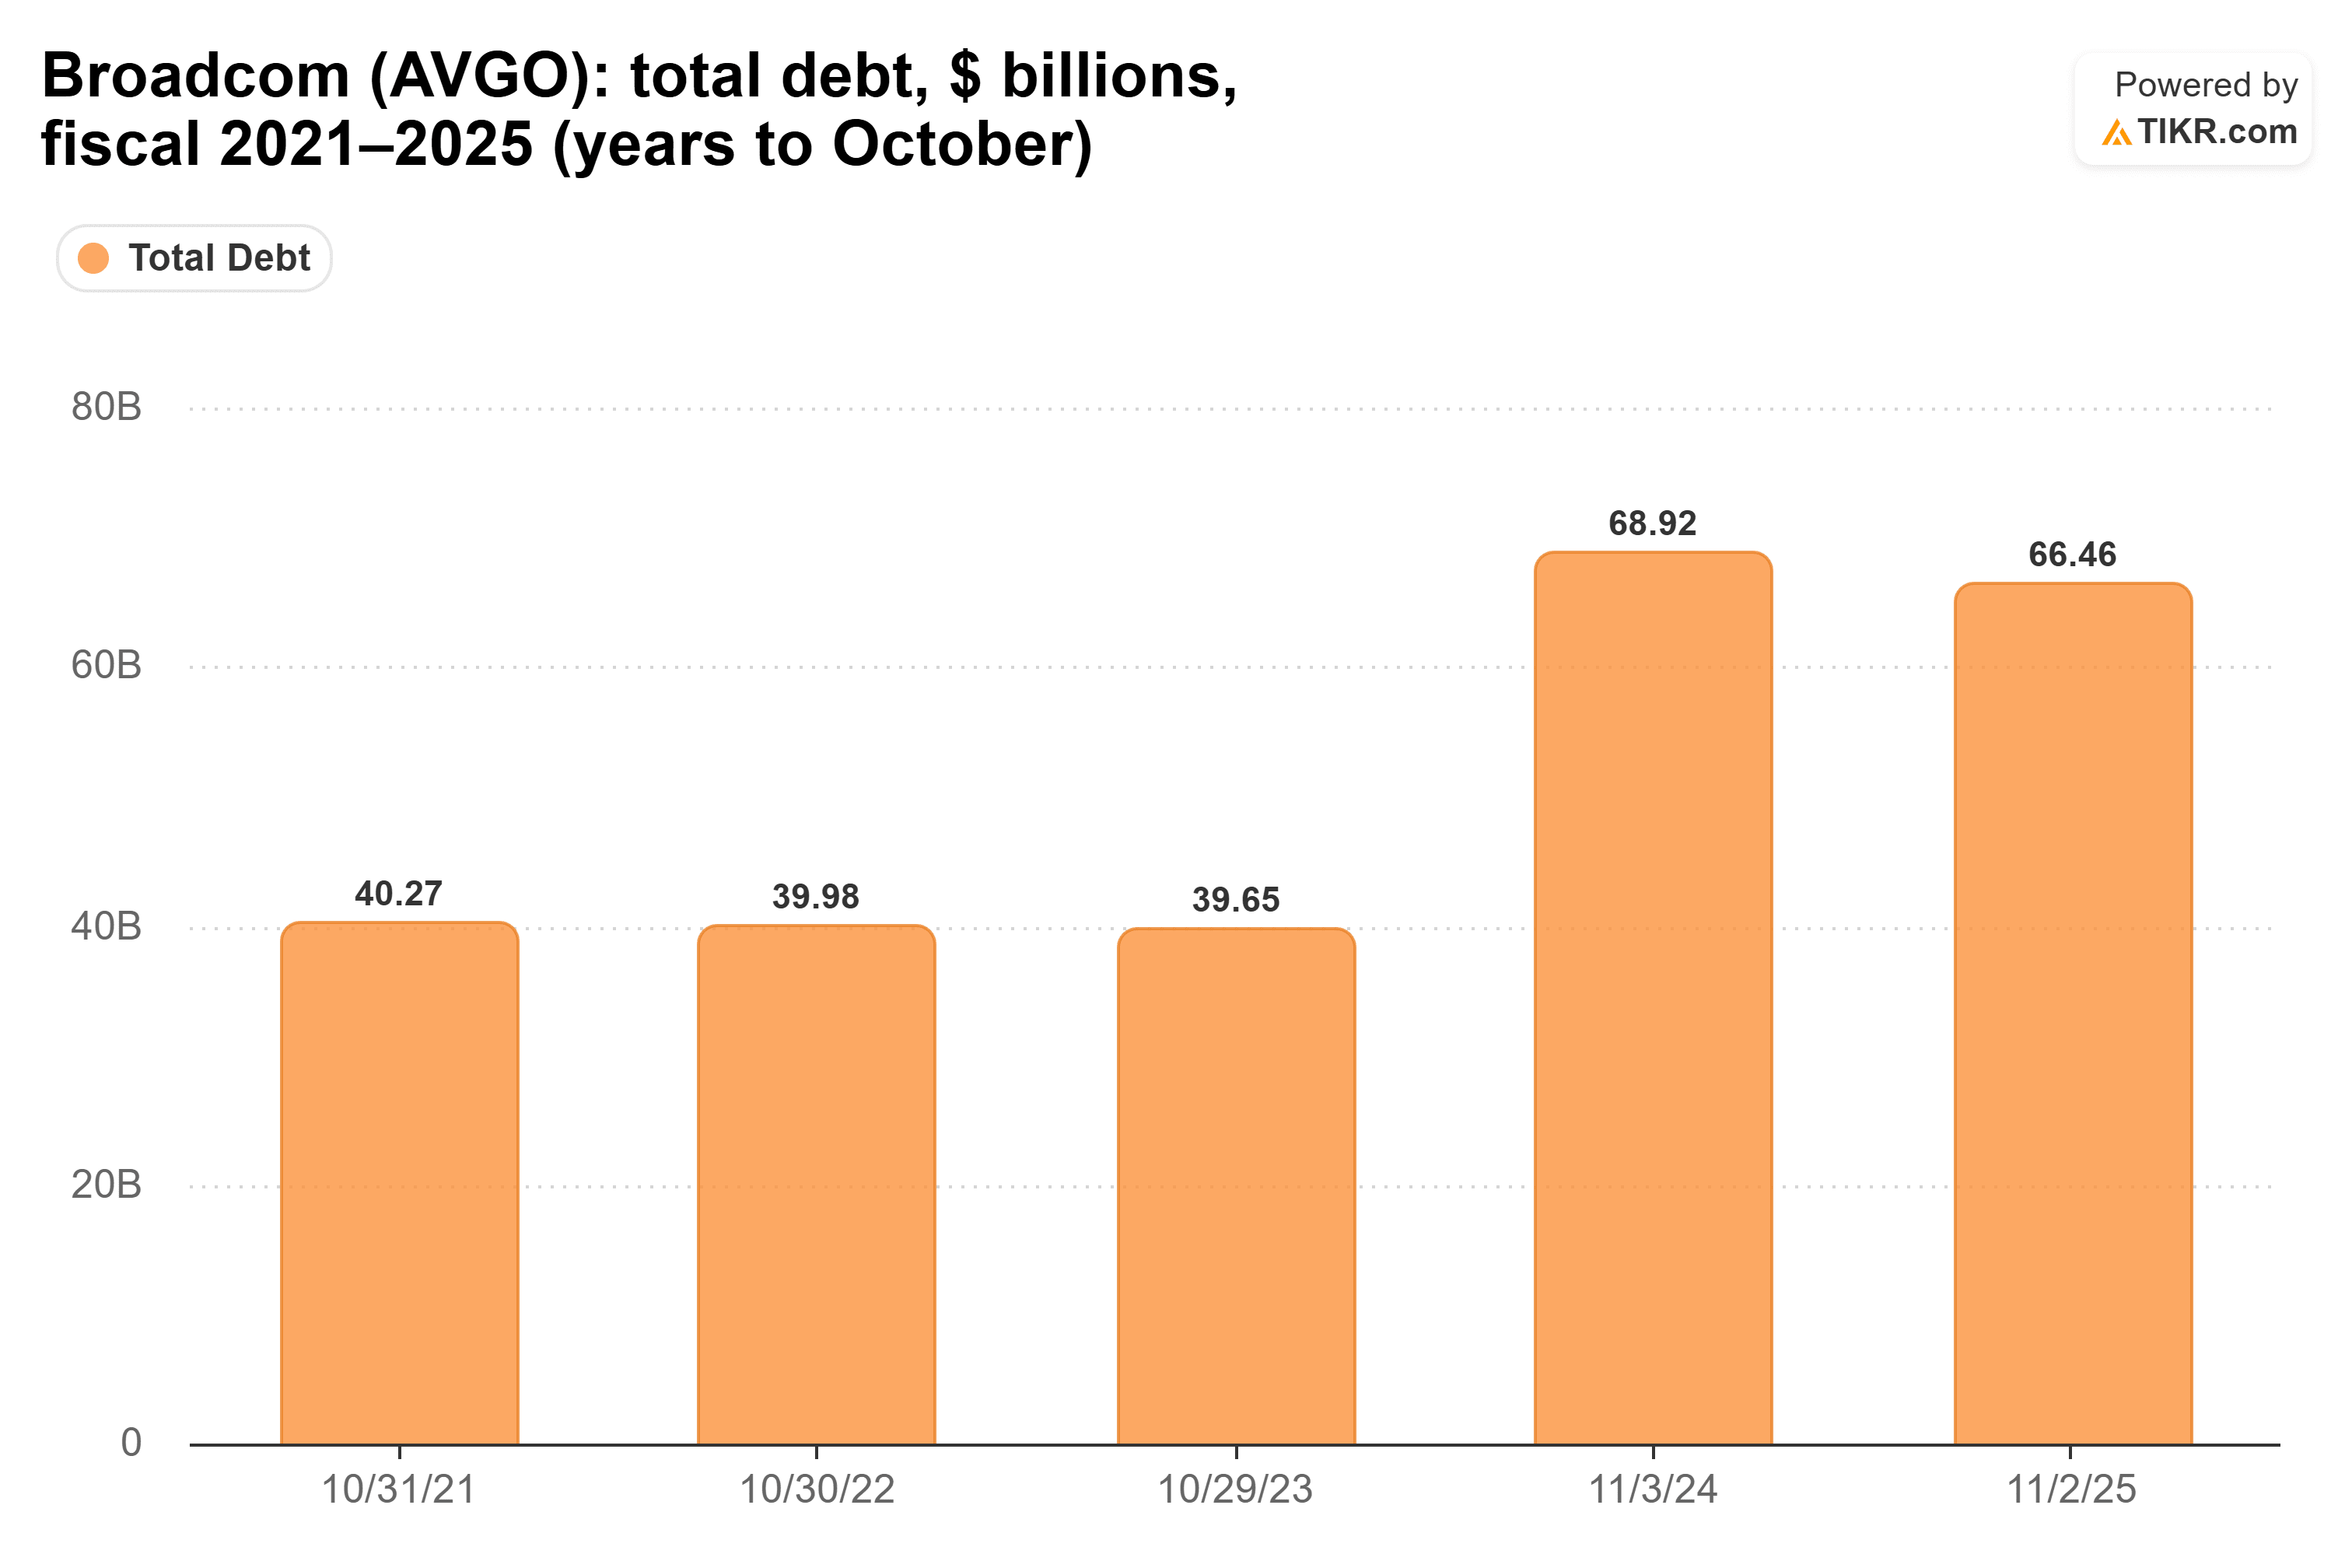
Broadcom spent the past year paying down its VMware debt. Now, this financing pushes the total sharply in the other direction.
The math is straightforward. Add $60 billion of new debt to $66.5 billion, and Broadcom is looking at roughly $126.5 billion, nearly double the previous total. Keep in mind that this is before any paydown and before factoring in how the $42 billion loan gets funded.
The growth it’s paying for
So why would Broadcom take on this much debt after spending a year paying some of it down? The answer comes down to what analysts expect from the business next.
Broadcom’s revenue climbed from $35.8 billion in fiscal 2023 to $63.9 billion in fiscal 2025. Analysts now expect that figure to reach $106 billion in fiscal 2026, $174 billion in fiscal 2027, and $272 billion in fiscal 2028, based on estimates from 40 to 49 analysts.

More than quadrupling revenue in three years gives Broadcom plenty of room to take on debt.
But there’s another layer to this deal. Broadcom is now helping finance the growth of one of its own customers. When a company lends money to a customer to buy its products, the opportunity and the risk sit in the same place.
If Anthropic keeps growing, Broadcom benefits from both sides of the deal, selling the chips and collecting on the loans. If Anthropic runs into trouble, Broadcom feels the impact on both sides, too.
Isn’t the loan safe?
The obvious counterpoint is that the chips themselves back the financing, while a public Anthropic would have access to plenty of cash to repay the debt. Anthropic is reportedly considering an IPO as early as mid-November.
That’s a reasonable argument. A successful IPO would give Anthropic a significant cash cushion. And if the chips secure the loans, as you would expect with a lease arrangement, Broadcom isn’t lending against nothing.
The problem is that AI chips are most valuable when a customer needs a lot of computing power. If Anthropic’s growth slows enough to make repayment difficult, the value of that collateral could fall at the same time. Broadcom would also face weaker chip orders from the same customer.
That leaves Broadcom with less protection in the exact situation where the financing becomes a problem.
So is $102 billion a smart bet?
I think the bet makes sense. Analysts expect Broadcom’s revenue to more than quadruple by fiscal 2028, and the company would not commit this much capital to Anthropic without seeing the customer as an important part of that growth. Financing a customer that is expanding this quickly can make good business sense.
Still, owning Broadcom now means taking on some exposure to Anthropic’s risk from both sides of the relationship. Broadcom is supplying the chips and lending Anthropic the money to buy them. Investors need to account for that concentration when valuing the stock.
Anthropic’s IPO, reportedly possible as early as mid-November, should provide a clearer picture of the company’s financial position and whether it can support this level of spending on its own.
So what is Broadcom stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Broadcom could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!