


Key Takeaways
- Barclays repeated its Overweight rating and $252 price target on Oracle on Oct. 26. That target is 100% above the stock’s last close.
- Barclays’ case is that Oracle’s cloud infrastructure growth keeps speeding up and its funding has improved, backed by a $664 billion backlog.
- Oracle trades at 15x forward earnings, against a five-year average of 21x, and free cash flow is still negative.
- Barclays’ $252 needs about 30x next-twelve-months earnings, which looks out of reach within a year, though it’s close to what Oracle’s average multiple gives on fiscal 2028 estimates.
Oracle (ORCL) has lost 56% since its closing high last October. Barclays still thinks it can double from here.
On Monday, Oct. 26, Barclays analyst Raimo Lenschow repeated his Overweight rating and $252 price target, 100% above Oracle’s last close.
The cost of the build
In fiscal 2026 (the year to May 31, 2026), Oracle’s capital spending hit $55.7 billion and its free cash flow was negative $23.7 billion. To pay for its AI data centers, Oracle sold $25 billion of bonds, $5 billion of preferred stock and $20 billion of common stock between February and August.
Then Oracle’s Sept. 10 report showed another $5 billion of negative free cash flow, with $90 billion to $95 billion of capex planned for the year. Asked when free cash flow turns positive, CFO Hilary Maxson said, “We haven’t given a particular time frame on that yet, and we don’t expect to give that today.”
How Barclays gets to $252
Barclays’ case is that Oracle’s growth has turned a corner and should keep speeding up, and that funding has improved. The quarter to Aug. 31 backs up the first part: cloud infrastructure revenue rose 121% to $7.4 billion, and its backlog reached $664 billion. Management expects about half of it to become revenue within 36 months.
On funding, Oracle booked more than $30 billion of new AI contracts that management says won’t require more capital from Oracle.
TIKR tracks 43 analysts on Oracle. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Oracle, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Oracle’s Analyst Ratings
Does $252 add up?
The consensus target has fallen from about $350 a year ago to $237.
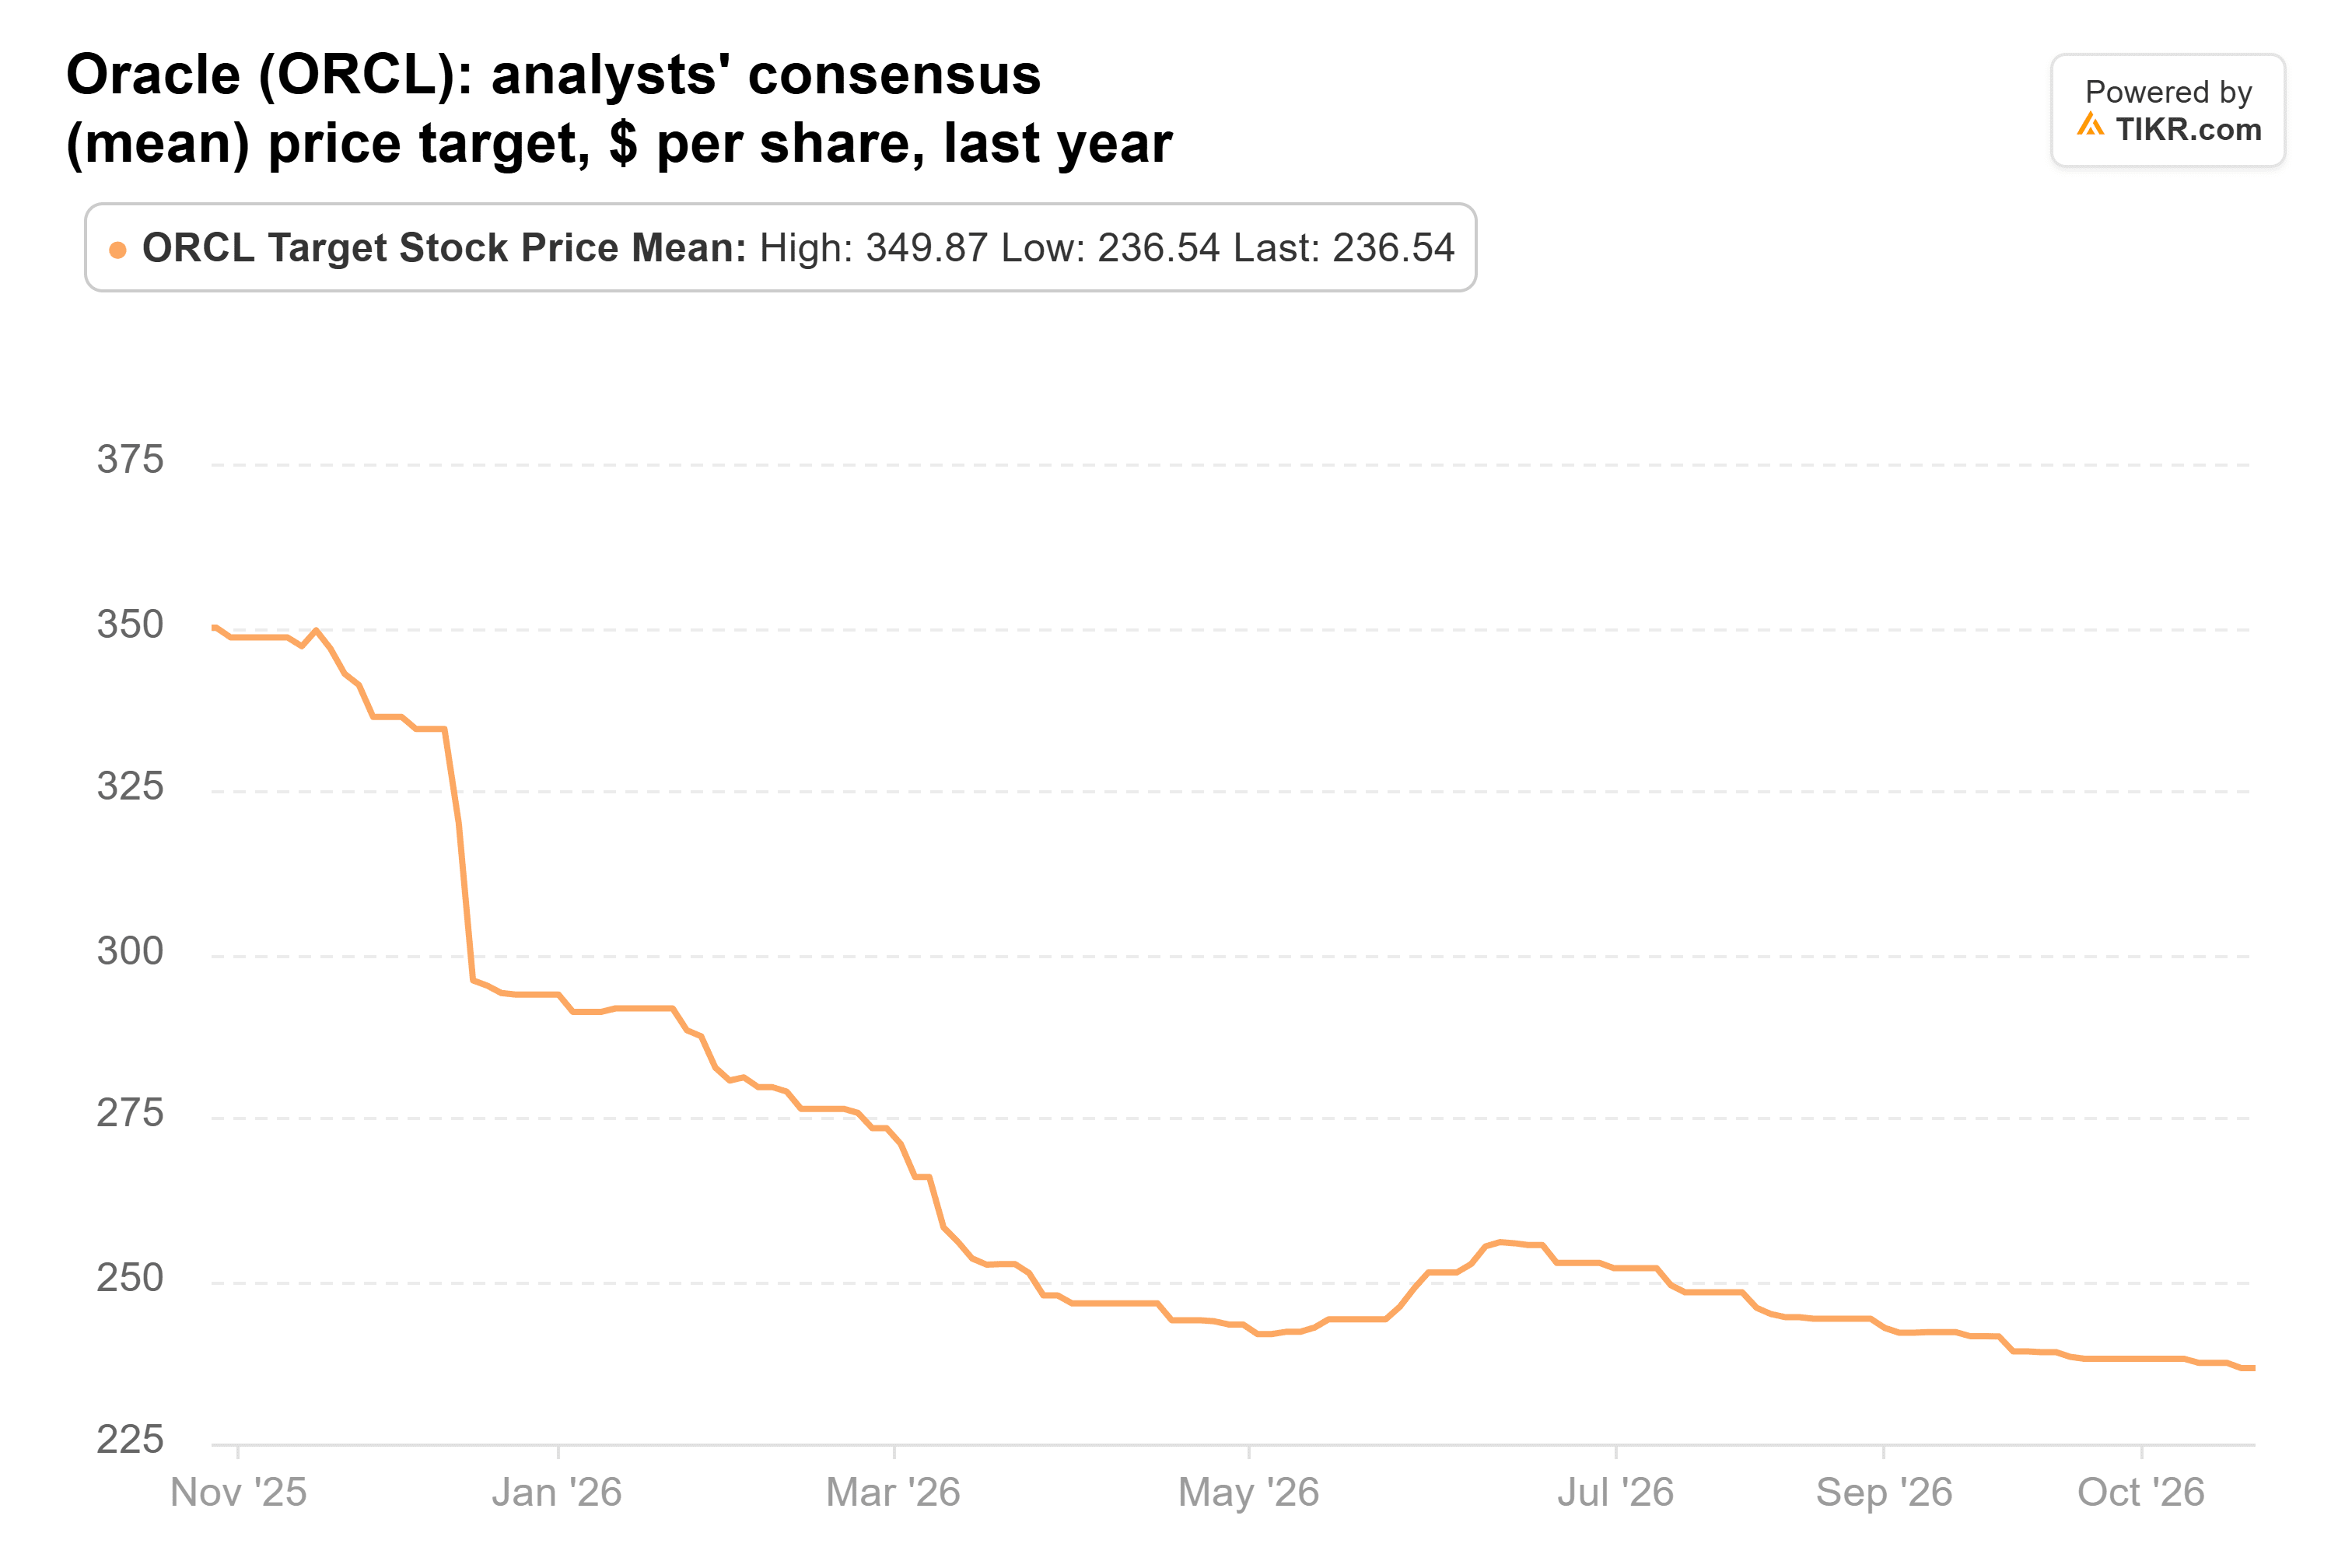
Targets run from $110 to $400, and Barclays’ is just 7% above the average.
Earnings estimates are holding up. Analysts expect $8.14 of normalized EPS in fiscal 2027 and $10.99 in fiscal 2028, both a little higher than 90 days ago.

But Oracle trades at 15x forward earnings, against a five-year average of 21x.

Barclays’ $252 is about 30x next-twelve-months earnings. At the 21x average, fiscal 2028’s $10.99 gets you to about $235.
A fair target, a year early
The biggest risk is who pays. S&P has said OpenAI accounts for about half of Oracle’s backlog, and total debt, leases included, reached $169.1 billion at Aug. 31.
My take: $252 is a fair price for what Oracle should earn in fiscal 2028, if that backlog pays. But reaching it within a year means the market paying about 30x, and I don’t see that until management says when free cash flow turns positive. The Oct. 28 Investor Day is management’s next chance to give a date.
So what is Oracle stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Oracle could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


