

Key Takeaways
- Ategrity shares fell 15% today after third-quarter earnings of $0.29 a share came in well short of analysts’ estimates.
- An investment loss caused the miss. The insurance business itself had its best quarter yet.
- Ategrity’s combined ratio hit a record low of 84.7%, and underwriting income rose 84% to $19.5 million.
- Management expects a fourth-quarter combined ratio below 87%, and analysts expect normalized EPS to rise every year through 2028.
Ategrity Specialty Insurance Company Holdings (ASIC) stock sank 15% today after its third-quarter earnings missed analysts’ estimates.
That’s a rough reaction to what CEO Justin Cohen called “an exceptional quarter of underwriting performance.” And the numbers back him up.
What exactly happened
Ategrity reported after Wednesday’s close:
- Diluted EPS was $0.29, down from $0.45 a year earlier and short of the $0.50 consensus
- Gross written premiums rose 14.7% to $165.0 million, with property up 25% and casualty up 10%
- The combined ratio was 84.7%, the lowest in company history, down from 88.7%
- Underwriting income rose 84% to $19.5 million
So how does an insurer post its best underwriting quarter ever and still miss?
Blame the portfolio
Net investment income rose 19% to $13.1 million. But Ategrity also booked $17.2 million of realized and unrealized investment losses. A year earlier, that line was a $9.2 million gain.
CFO Neil Adler said on Ategrity’s third-quarter call that the loss primarily reflected “a normalization of the substantial gains recorded earlier this year in our utility and infrastructure investments.” Even after the hit, investment gains are still $10.8 million for the first nine months.
Strip out the investment gains and losses in both years, and pretax income rose about 55%.
TIKR tracks 5 analysts on Ategrity Specialty Insurance Company Holdings. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Ategrity Specialty Insurance Company Holdings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Ategrity Specialty Insurance Company Holdings’ Analyst Ratings
What’s next
Management expects fourth-quarter premium growth to beat the E&S market by 15 to 20 points, with a combined ratio below 87%. And analysts expect normalized EPS to keep climbing, from $1.61 in 2025 to $3.02 by 2028…
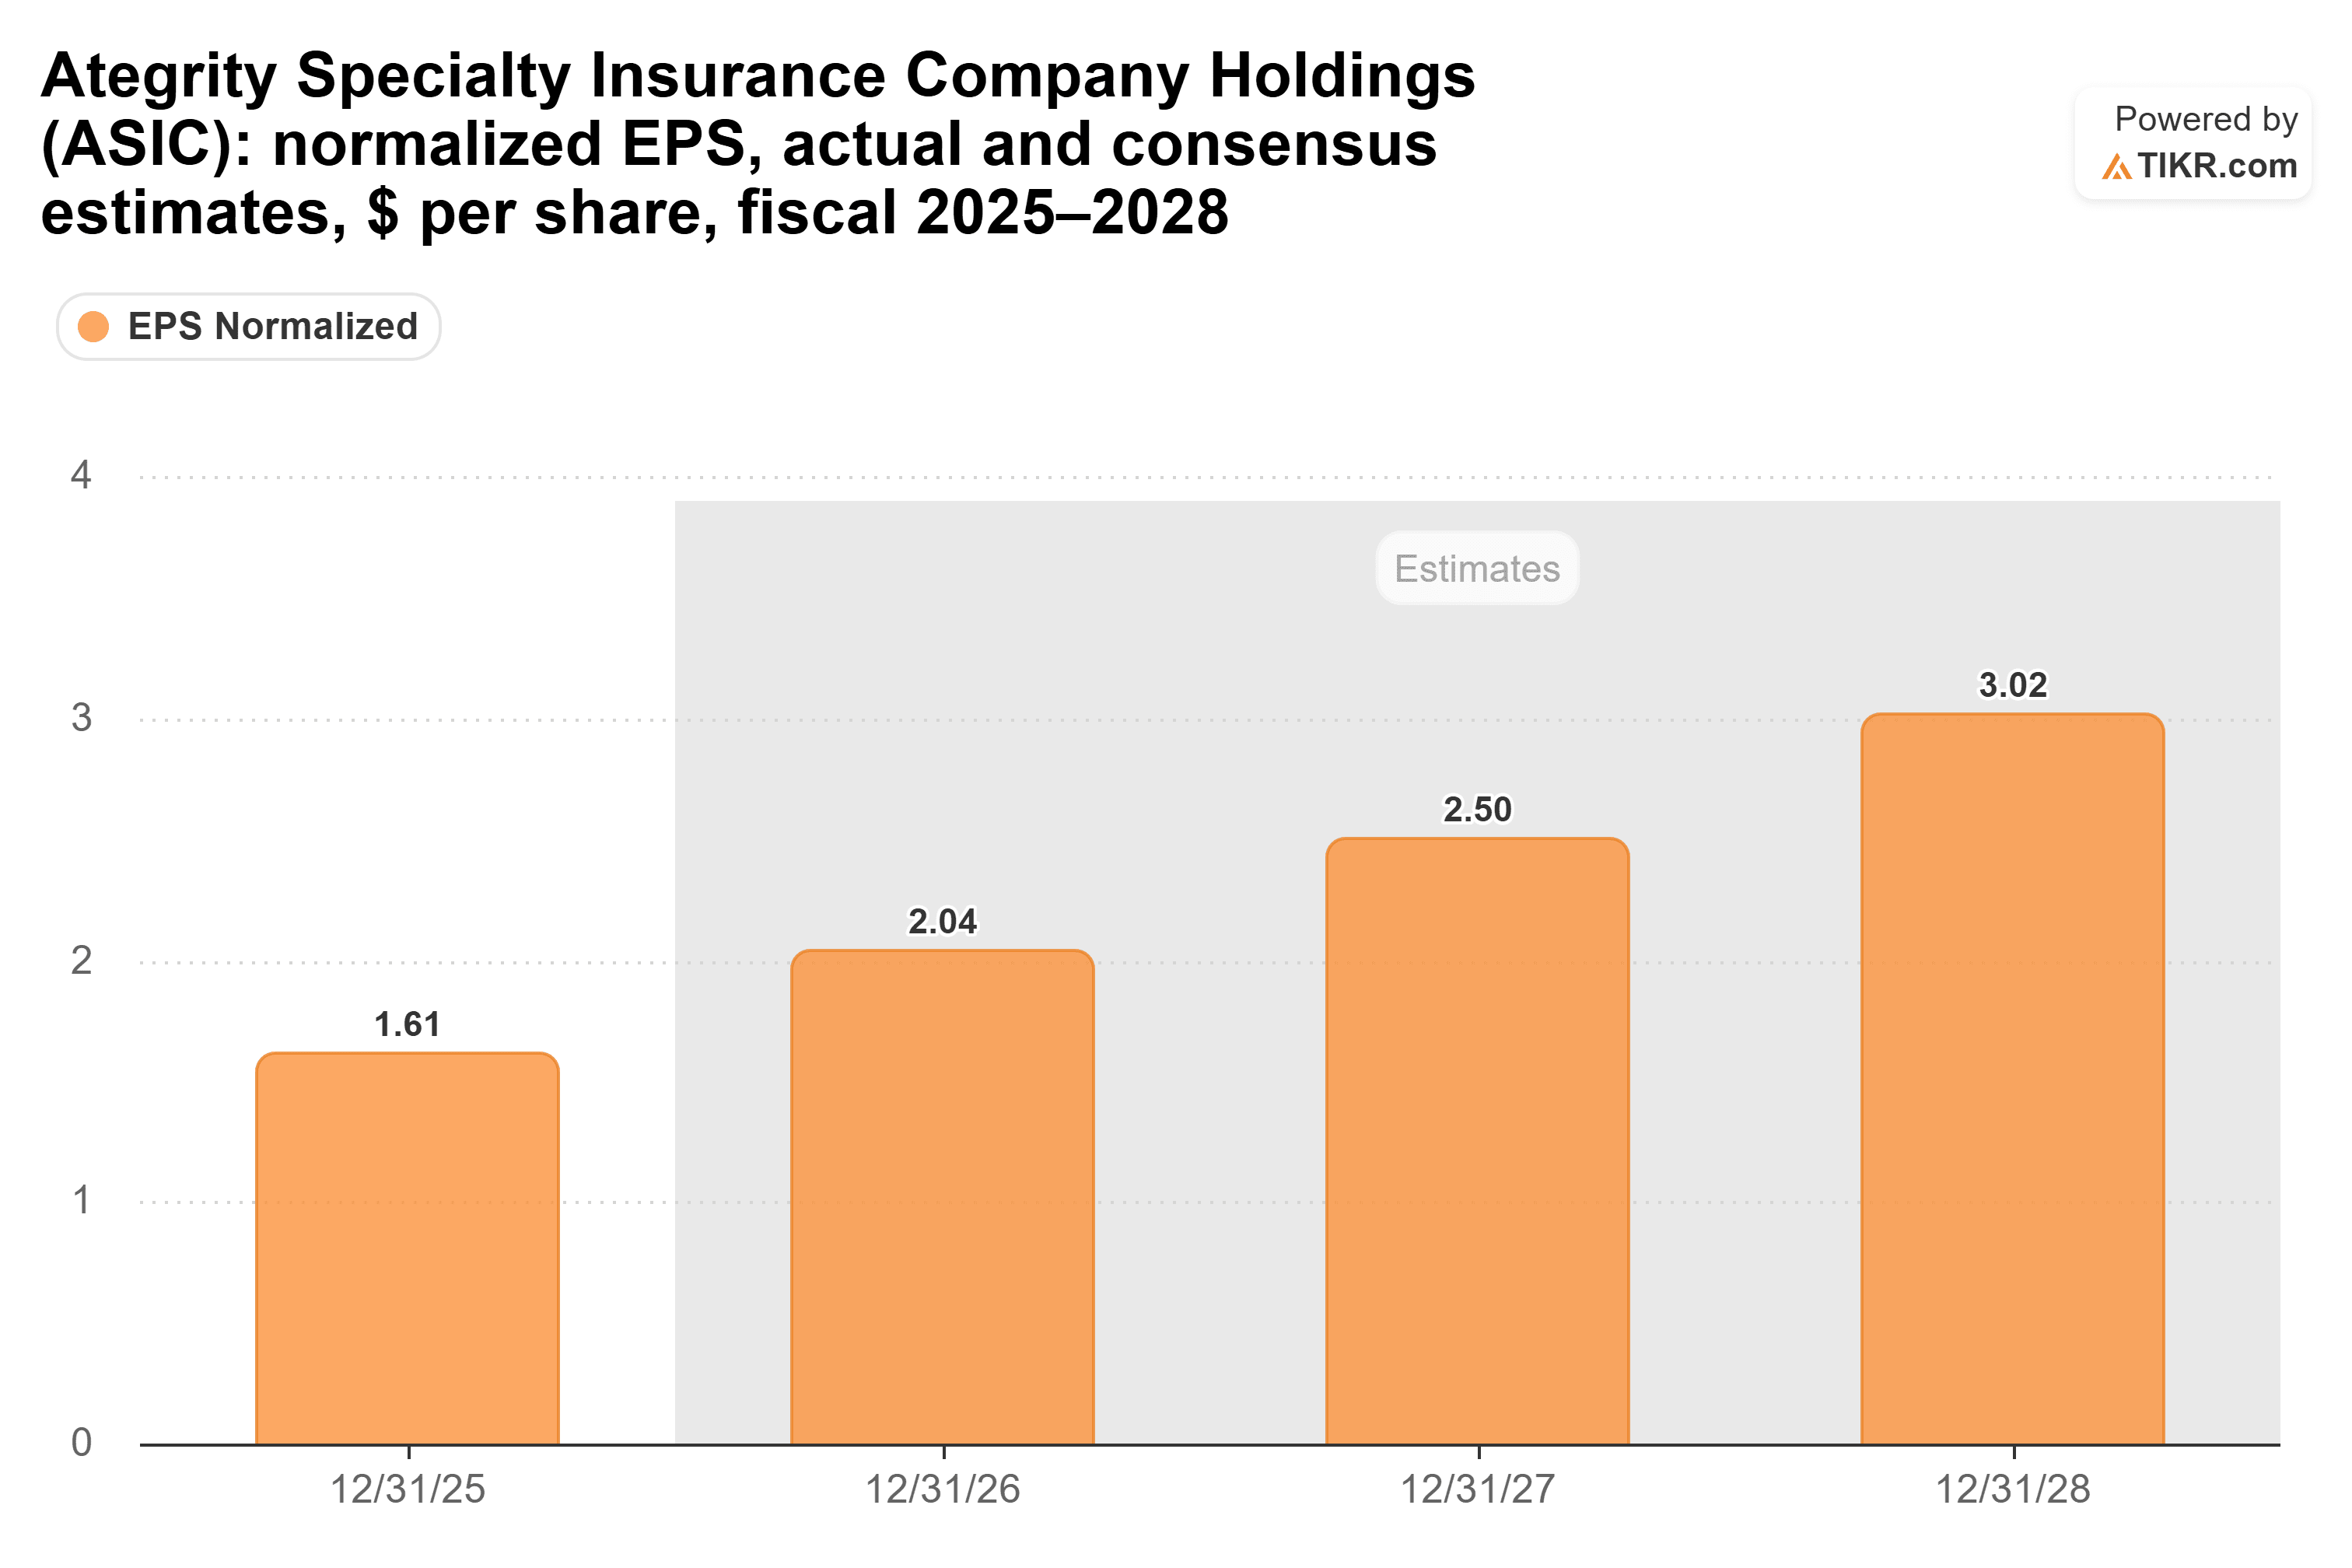
Nothing in this quarter’s underwriting gives them a reason to cut. Barclays trimmed its price target to $27 from $28 but kept its Overweight rating, while Citi raised its target to $29 from $28.50.
Growth is the risk. Premiums rose 20.4% over the first nine months, and Cohen said this quarter was held back by rate increases on new casualty business and a new underwriting system.
The stock also got cheaper. Ategrity traded at 12x forward earnings at Wednesday’s close, a bit above its one-year average of 11x…
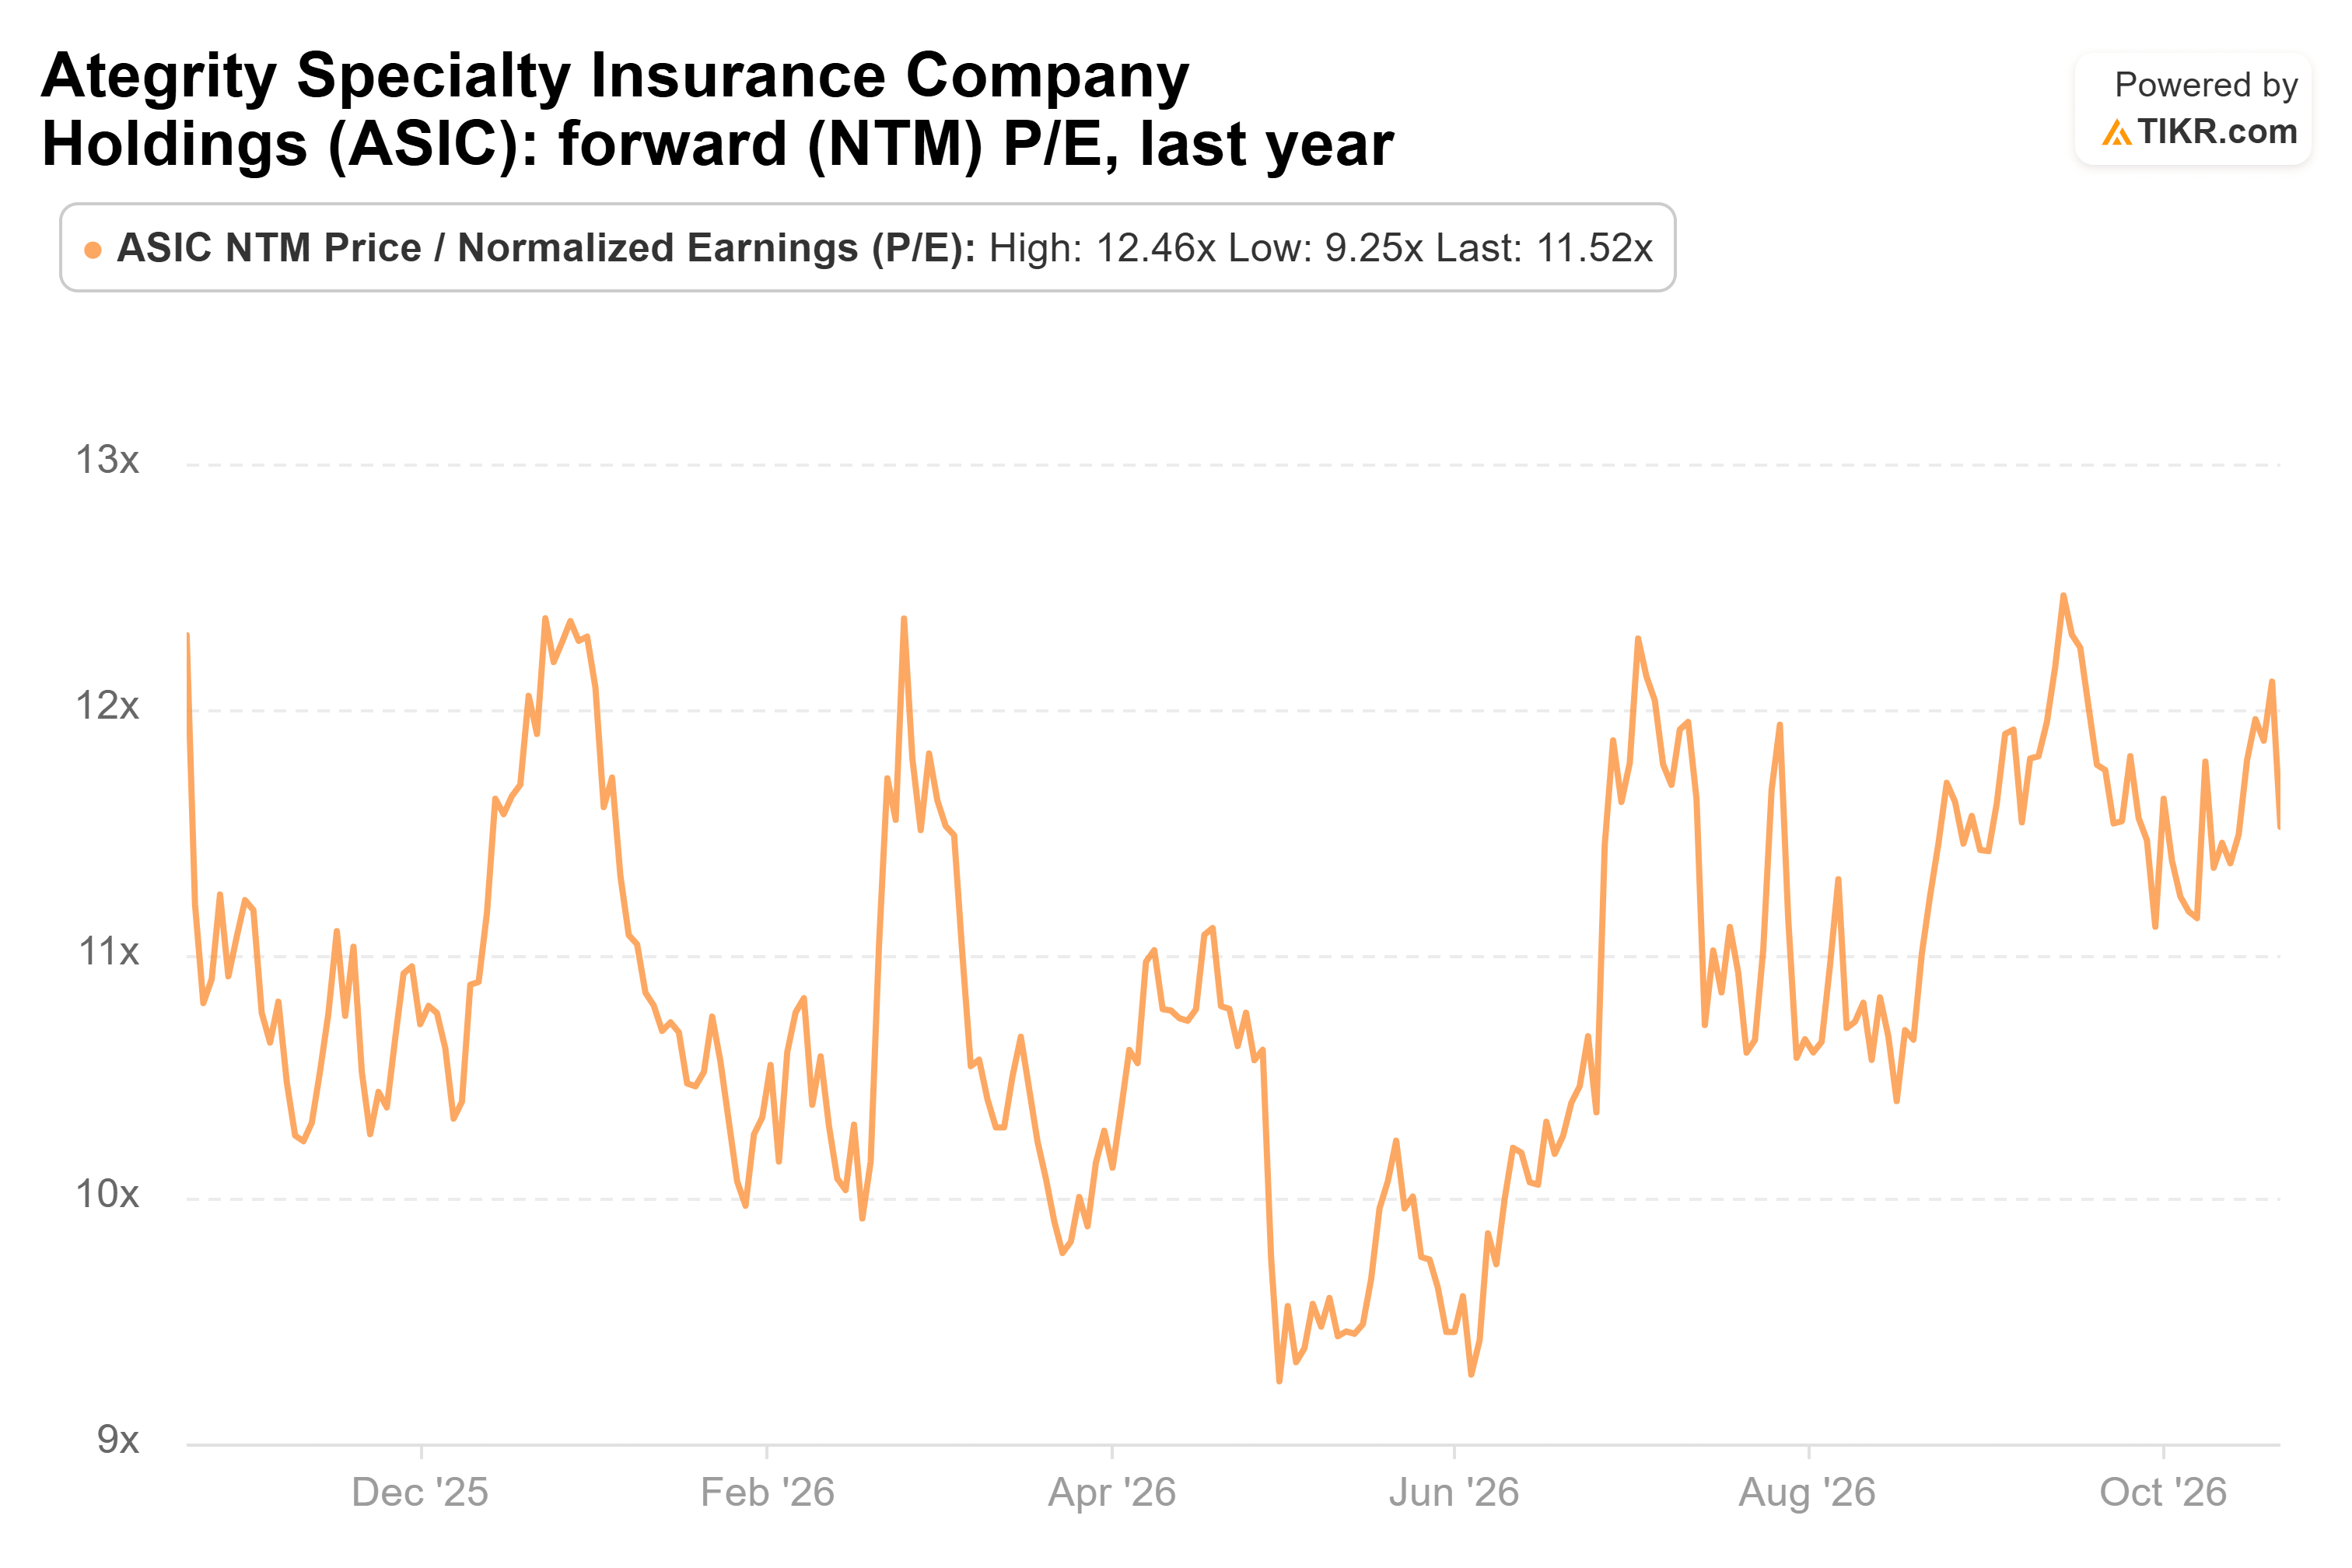
After today’s drop, it’s closer to 10x, near the low end of its range over the past year.
My take: the market is punishing a record underwriting quarter because of an investment line that’s still positive for the year. That looks like an overreaction. Of course, if premium growth keeps slowing from this year’s 20% pace, the discount could stick around.
So what is Ategrity stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Ategrity could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


