Key Takeaways
- Procter & Gamble shares jumped 6% after fiscal first-quarter core EPS of $2.00 and revenue of $23.3 billion beat Wall Street’s estimates.
- The quarter’s growth came mostly from higher volume, which shows demand for P&G’s products is holding up.
- P&G now expects commodity costs to take about $1.4 billion out of fiscal 2027 profit, up from about $1 billion, yet it kept its core EPS guidance of $6.89 to $7.11.
- Management expects cost pressure to build over the next few quarters, so margins are the number to watch.
Procter & Gamble (PG) shares are up 6% today, on a day the broader market is falling, after its fiscal first-quarter results beat Wall Street’s estimates this morning.
Even better: most of the growth came from shoppers buying more.
The details
For the quarter ended Sept. 30, P&G reported:
- Core EPS of $2.00, up 1% from a year ago and ahead of the $1.89 consensus
- Revenue of $23.3 billion, up 4%, against the $22.82 billion analysts expected
- Organic sales up 4%, with 2 points from volume, 1 from mix, and only a small lift from pricing
CEO Shailesh Jejurikar said “this strong start keeps us on track to deliver within our guidance ranges” for the fiscal year, which ends in June 2027.
Shoppers are buying more
Organic volume rose 2.4%, led by Fabric & Home Care at 4.3% on laundry and home care gains in North America and Europe. Price added just 0.4%.
That’s the healthiest kind of growth a staples giant can post, and shoppers traded up too (mix added 1.1%).
TIKR tracks 25 analysts on Procter & Gamble. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Procter & Gamble, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Procter & Gamble’s Analyst Ratings
The cost bill keeps growing
Margins are the catch. Core gross margin fell 150 basis points. Commodities and product reinvestment each cost 140 basis points, and 120 basis points of productivity savings made up only part of that.
And the bill is getting bigger. P&G now expects commodities to cost it about $1.4 billion after tax this fiscal year, up from about $1 billion when it first gave guidance this summer. Management said on P&G’s first-quarter call that oil above $100 a barrel would be an “increasing headwind” for the year.
Yet P&G kept its core EPS guidance of $6.89 to $7.11, a range that takes in analysts’ $6.98 consensus…
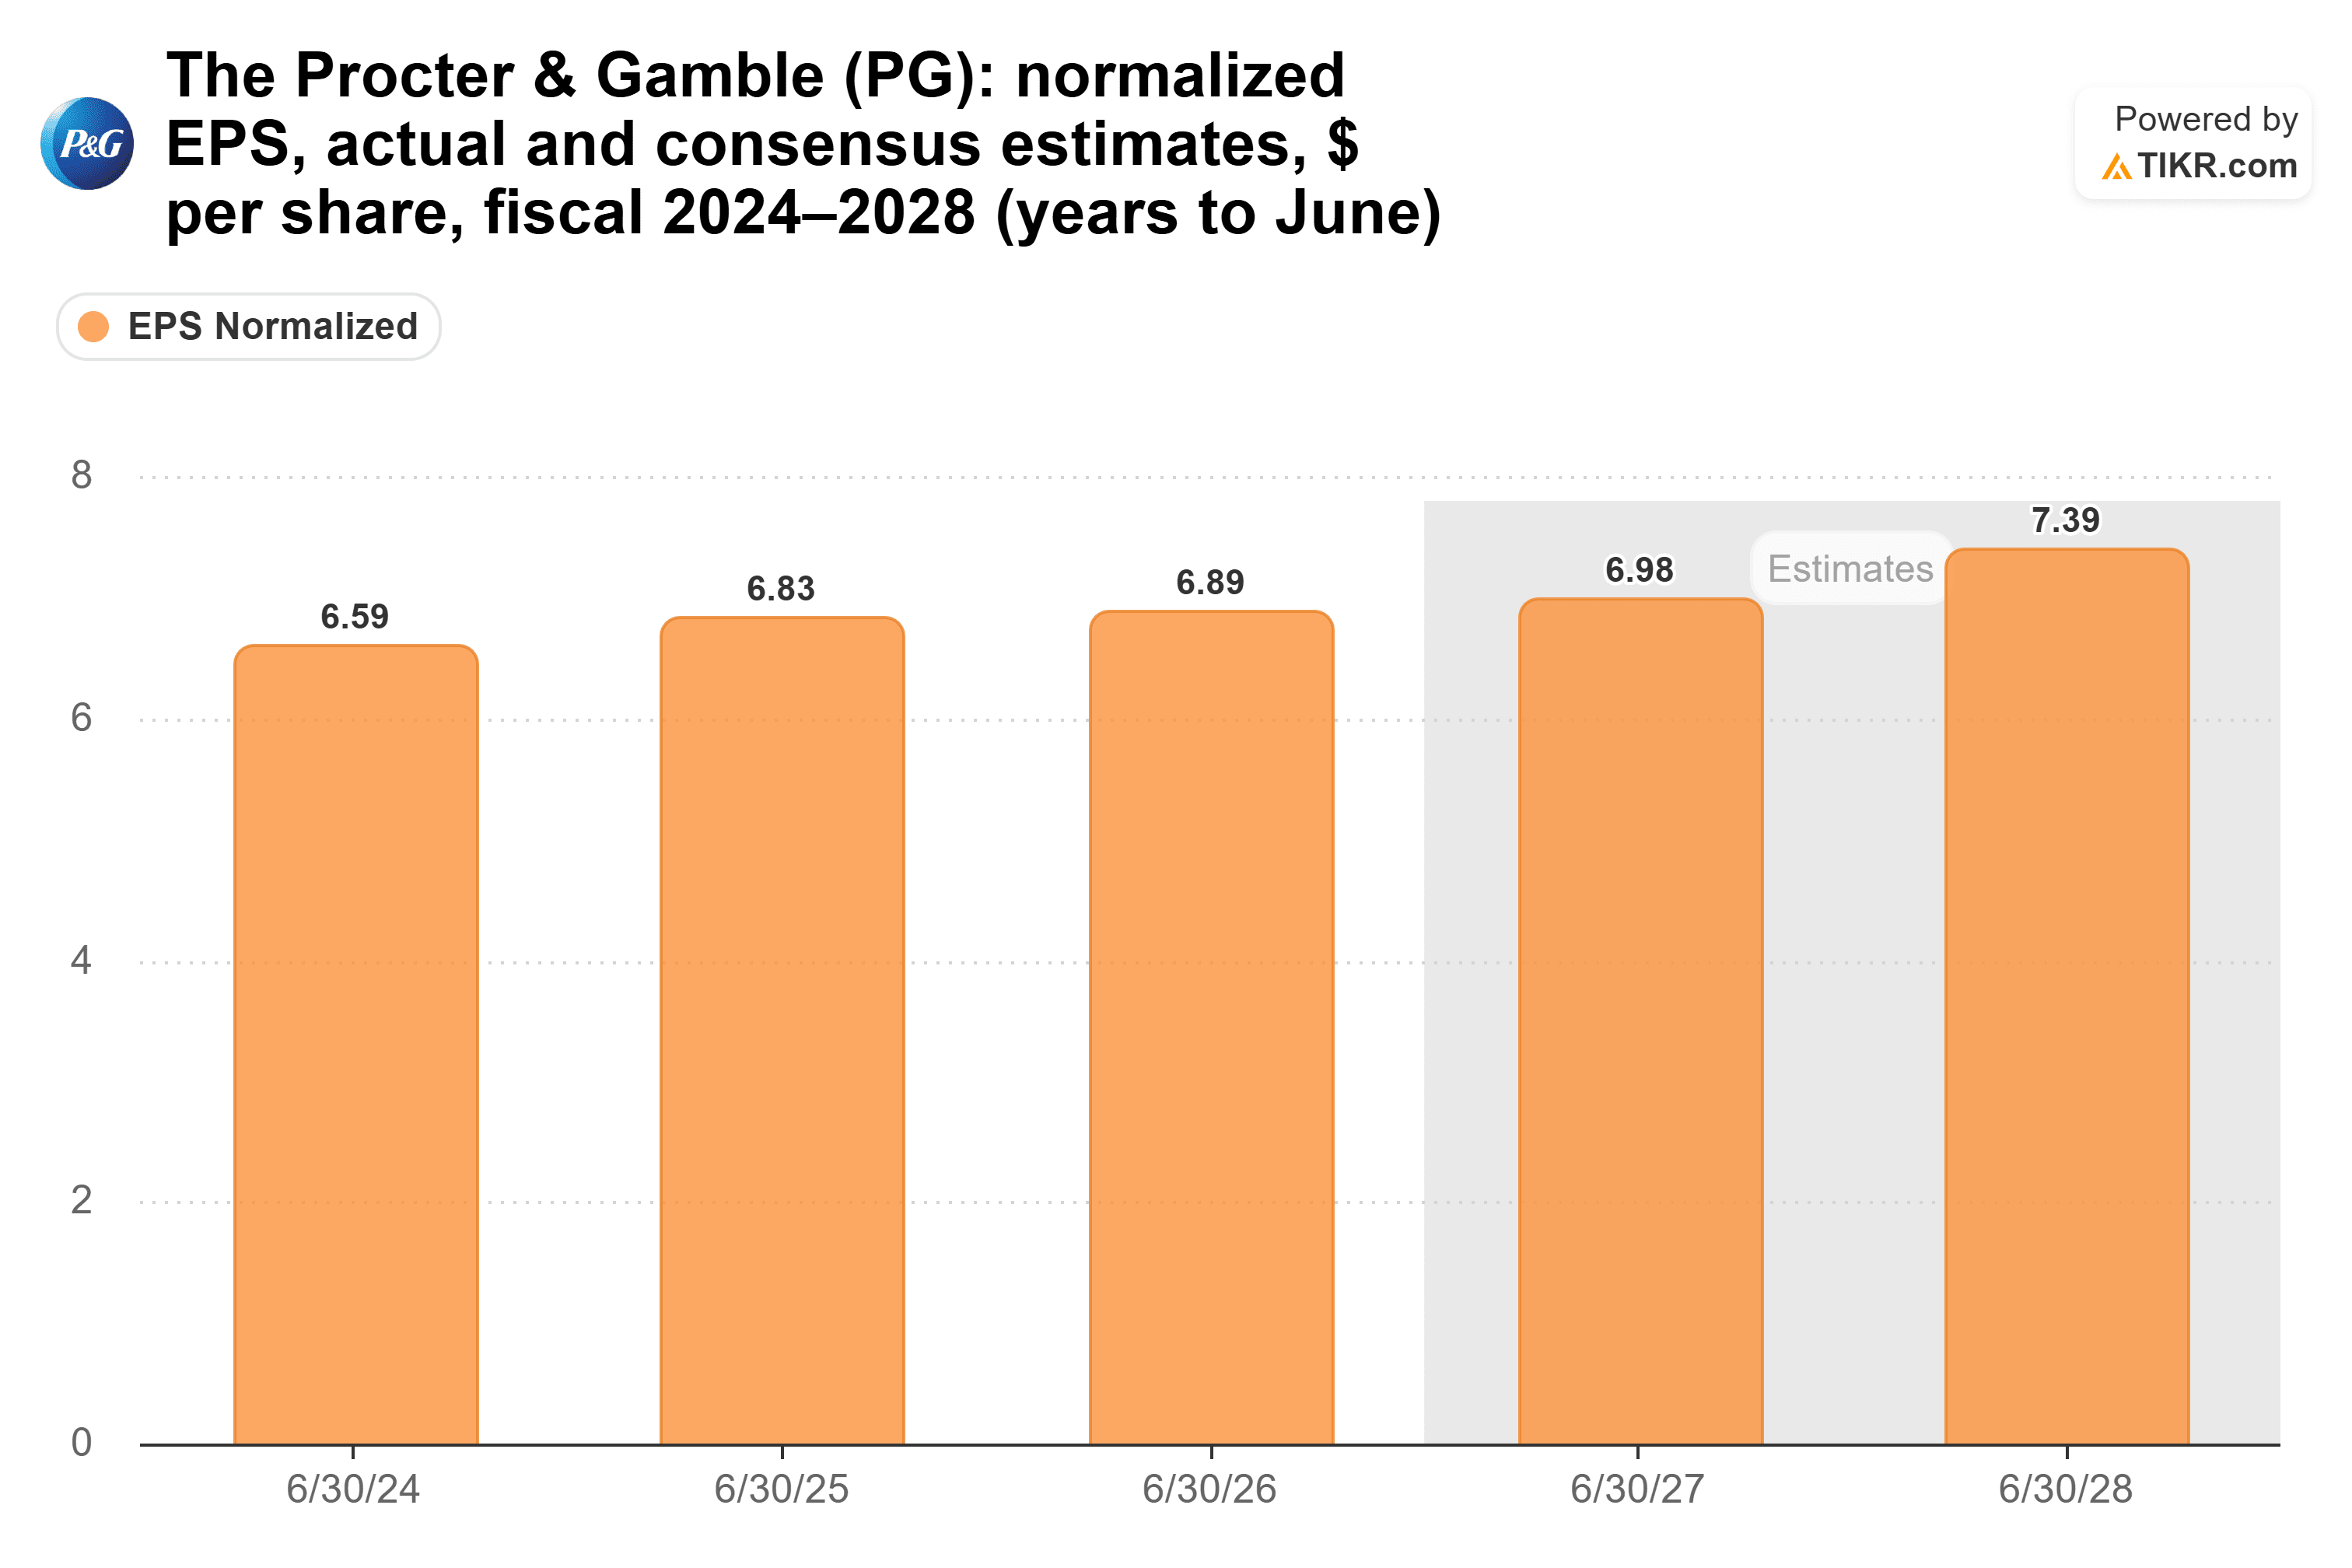
(P&G took on a cost bill $400 million bigger without moving its range, which gives analysts little reason to cut that number.)
Still priced like a staple
P&G traded at 23x forward earnings at yesterday’s close, around its five-year average…
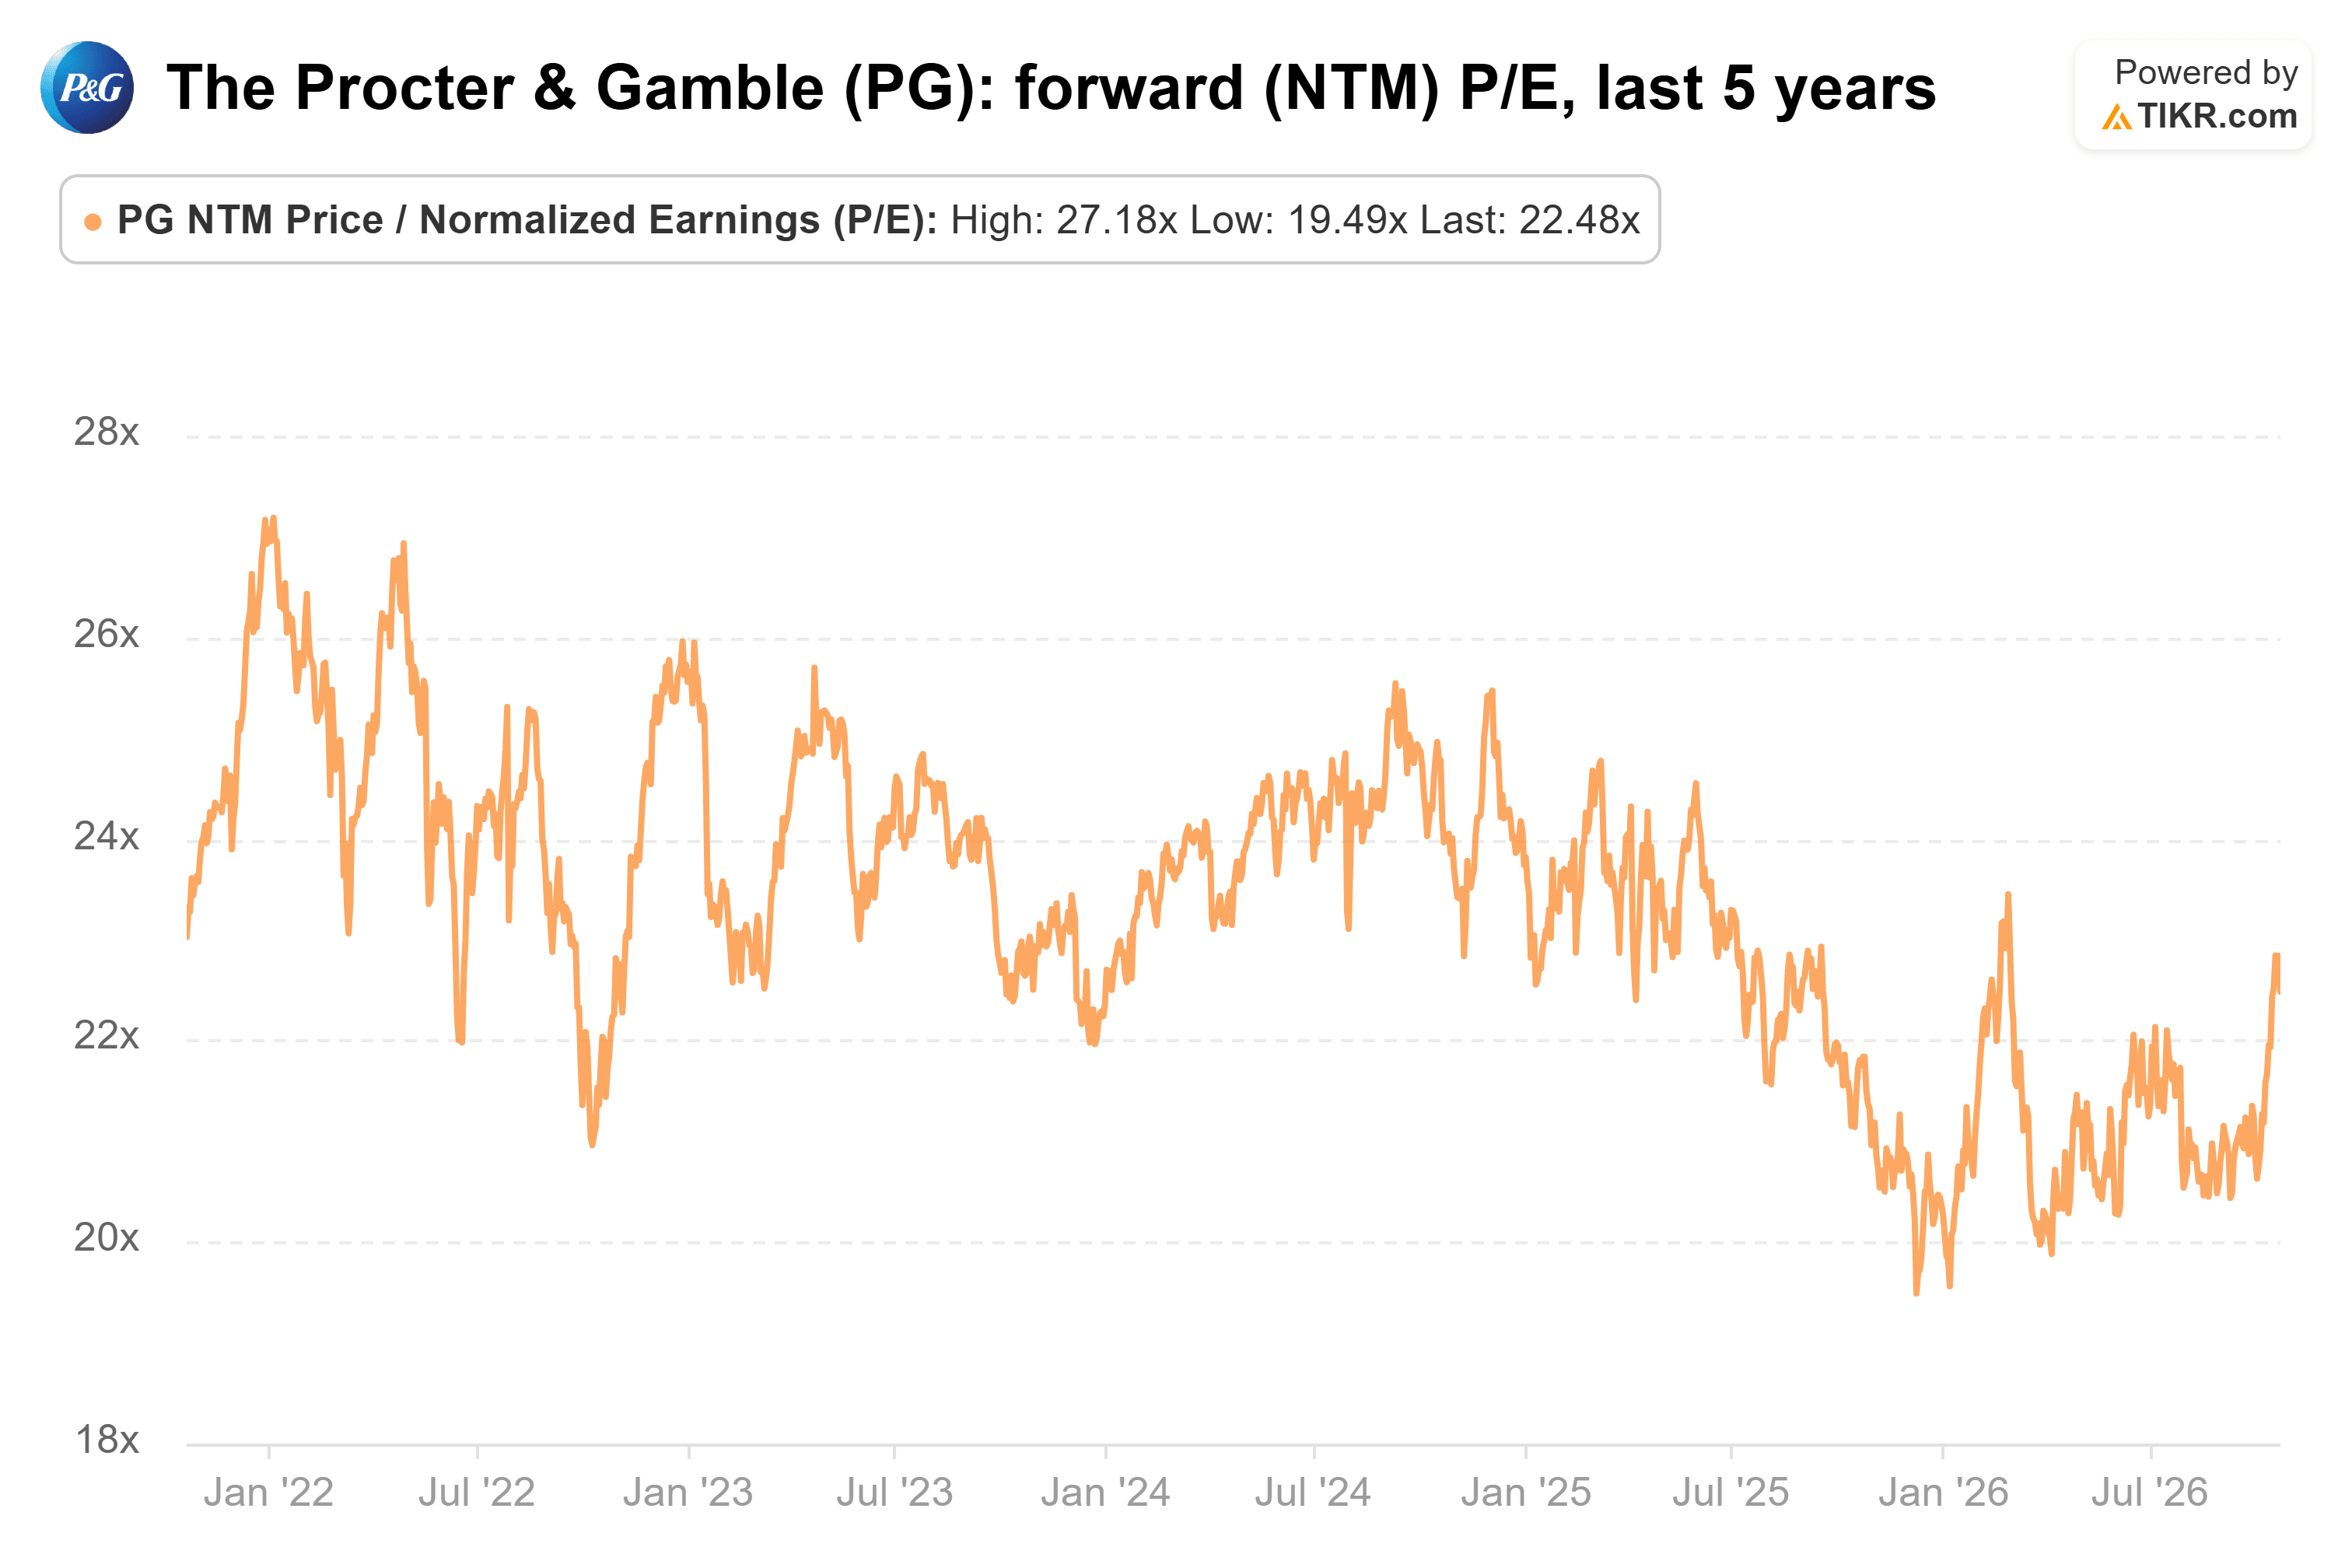
After today’s jump, it’s closer to 24x. That’s above the average but well below its 27x peak in early 2022.
My take: volume-led growth is exactly what you want from a defensive stock in a shaky market, and P&G just showed it can absorb a bigger cost bill and still hold its range. I’d want to see margins steady before expecting much more upside.
The next test is fiscal second-quarter results in January, when we’ll see whether higher oil starts eating into that guidance.
So what is Procter & Gamble stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Procter & Gamble could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Procter & Gamble for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!