

Key Takeaways
- Allegion shares rose 11% today after its third-quarter adjusted EPS of $2.60 and revenue of $1.17 billion beat Wall Street’s estimates.
- Management raised its 2026 adjusted EPS outlook to $9.05 to $9.10, above the $8.97 analysts expected, and the outlook leaves out tariff refunds.
- Almost all of the growth came from the Americas, while organic sales in the International segment slipped and its margin shrank.
- The next test is the fourth-quarter report early next year, and whether International sales start growing again.
Allegion (ALLE) stock is up 11% today in a down market. Its third-quarter results beat Wall Street’s estimates, and management raised its full-year outlook.
President and CEO John H. Stone credited “steady momentum in our demand generation engine” for the higher outlook.
Beat and raise
Here’s what Allegion reported before the open:
- Adjusted EPS of $2.60, up 13% and ahead of the $2.50 analysts expected
- Revenue of $1.17 billion, up 9.6% (7.2% organically), against $1.14 billion expected
- An adjusted operating margin of 24.7%, up from 24.1%
- A 2026 adjusted EPS outlook of $9.05 to $9.10, up from $8.85 to $9.00
One region does the heavy lifting
The Americas made up about 80% of third-quarter sales and grew 9.1% organically. Non-residential sales grew at a low-double-digit organic rate and residential at a mid-single-digit rate. The region’s adjusted operating margin rose to 30.1%.
International went the other way. Organic sales slipped 0.2% on lower volumes, and the segment’s adjusted margin fell 40 basis points to 13.9%. The Americas earned about 90% of the two segments’ adjusted operating income.
The Americas also drove the higher revenue outlook, which calls for 9.5% to 10.5% reported growth this year. That works out to roughly $4.5 billion, above the $4.41 billion analysts had expected…
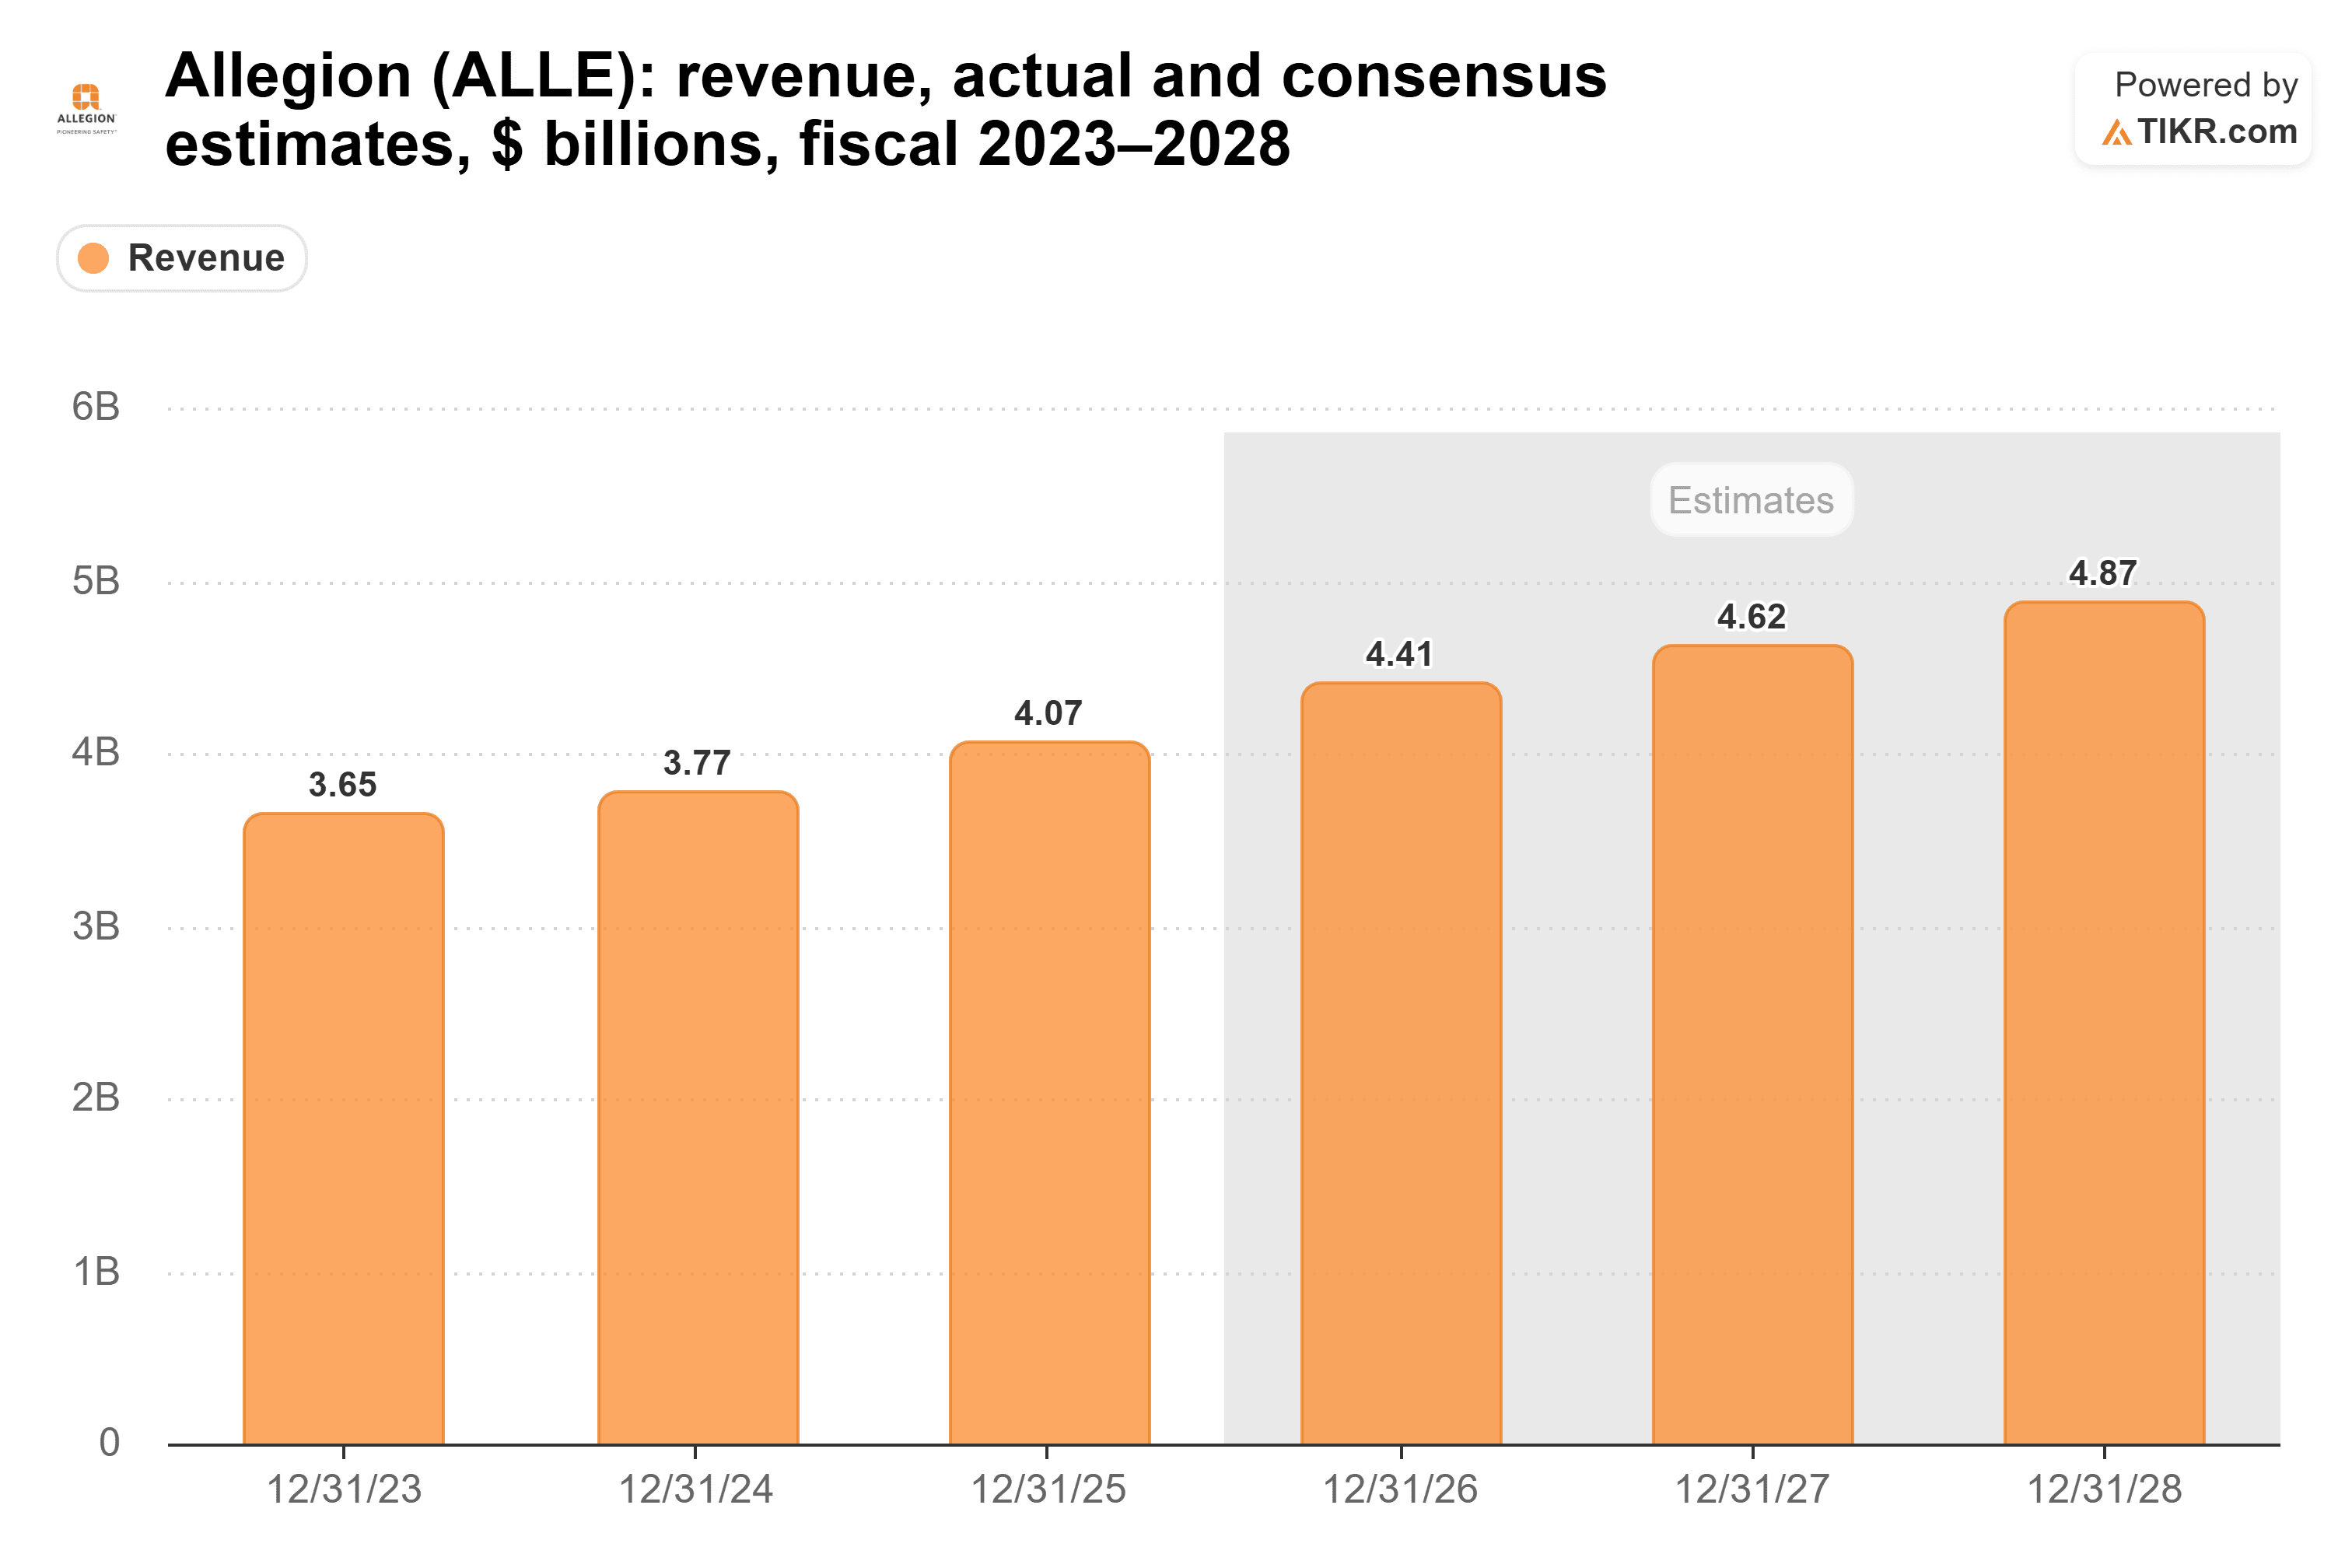
(Leaving out acquisitions and currency, the outlook is 5% to 6% organic growth.)
TIKR tracks 11 analysts on Allegion. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Allegion, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Allegion’s Analyst Ratings
The outlook tops the Street
The new EPS range is above the $8.97 analysts expected for 2026. It would also be a double-digit increase from $8.14 in 2025…
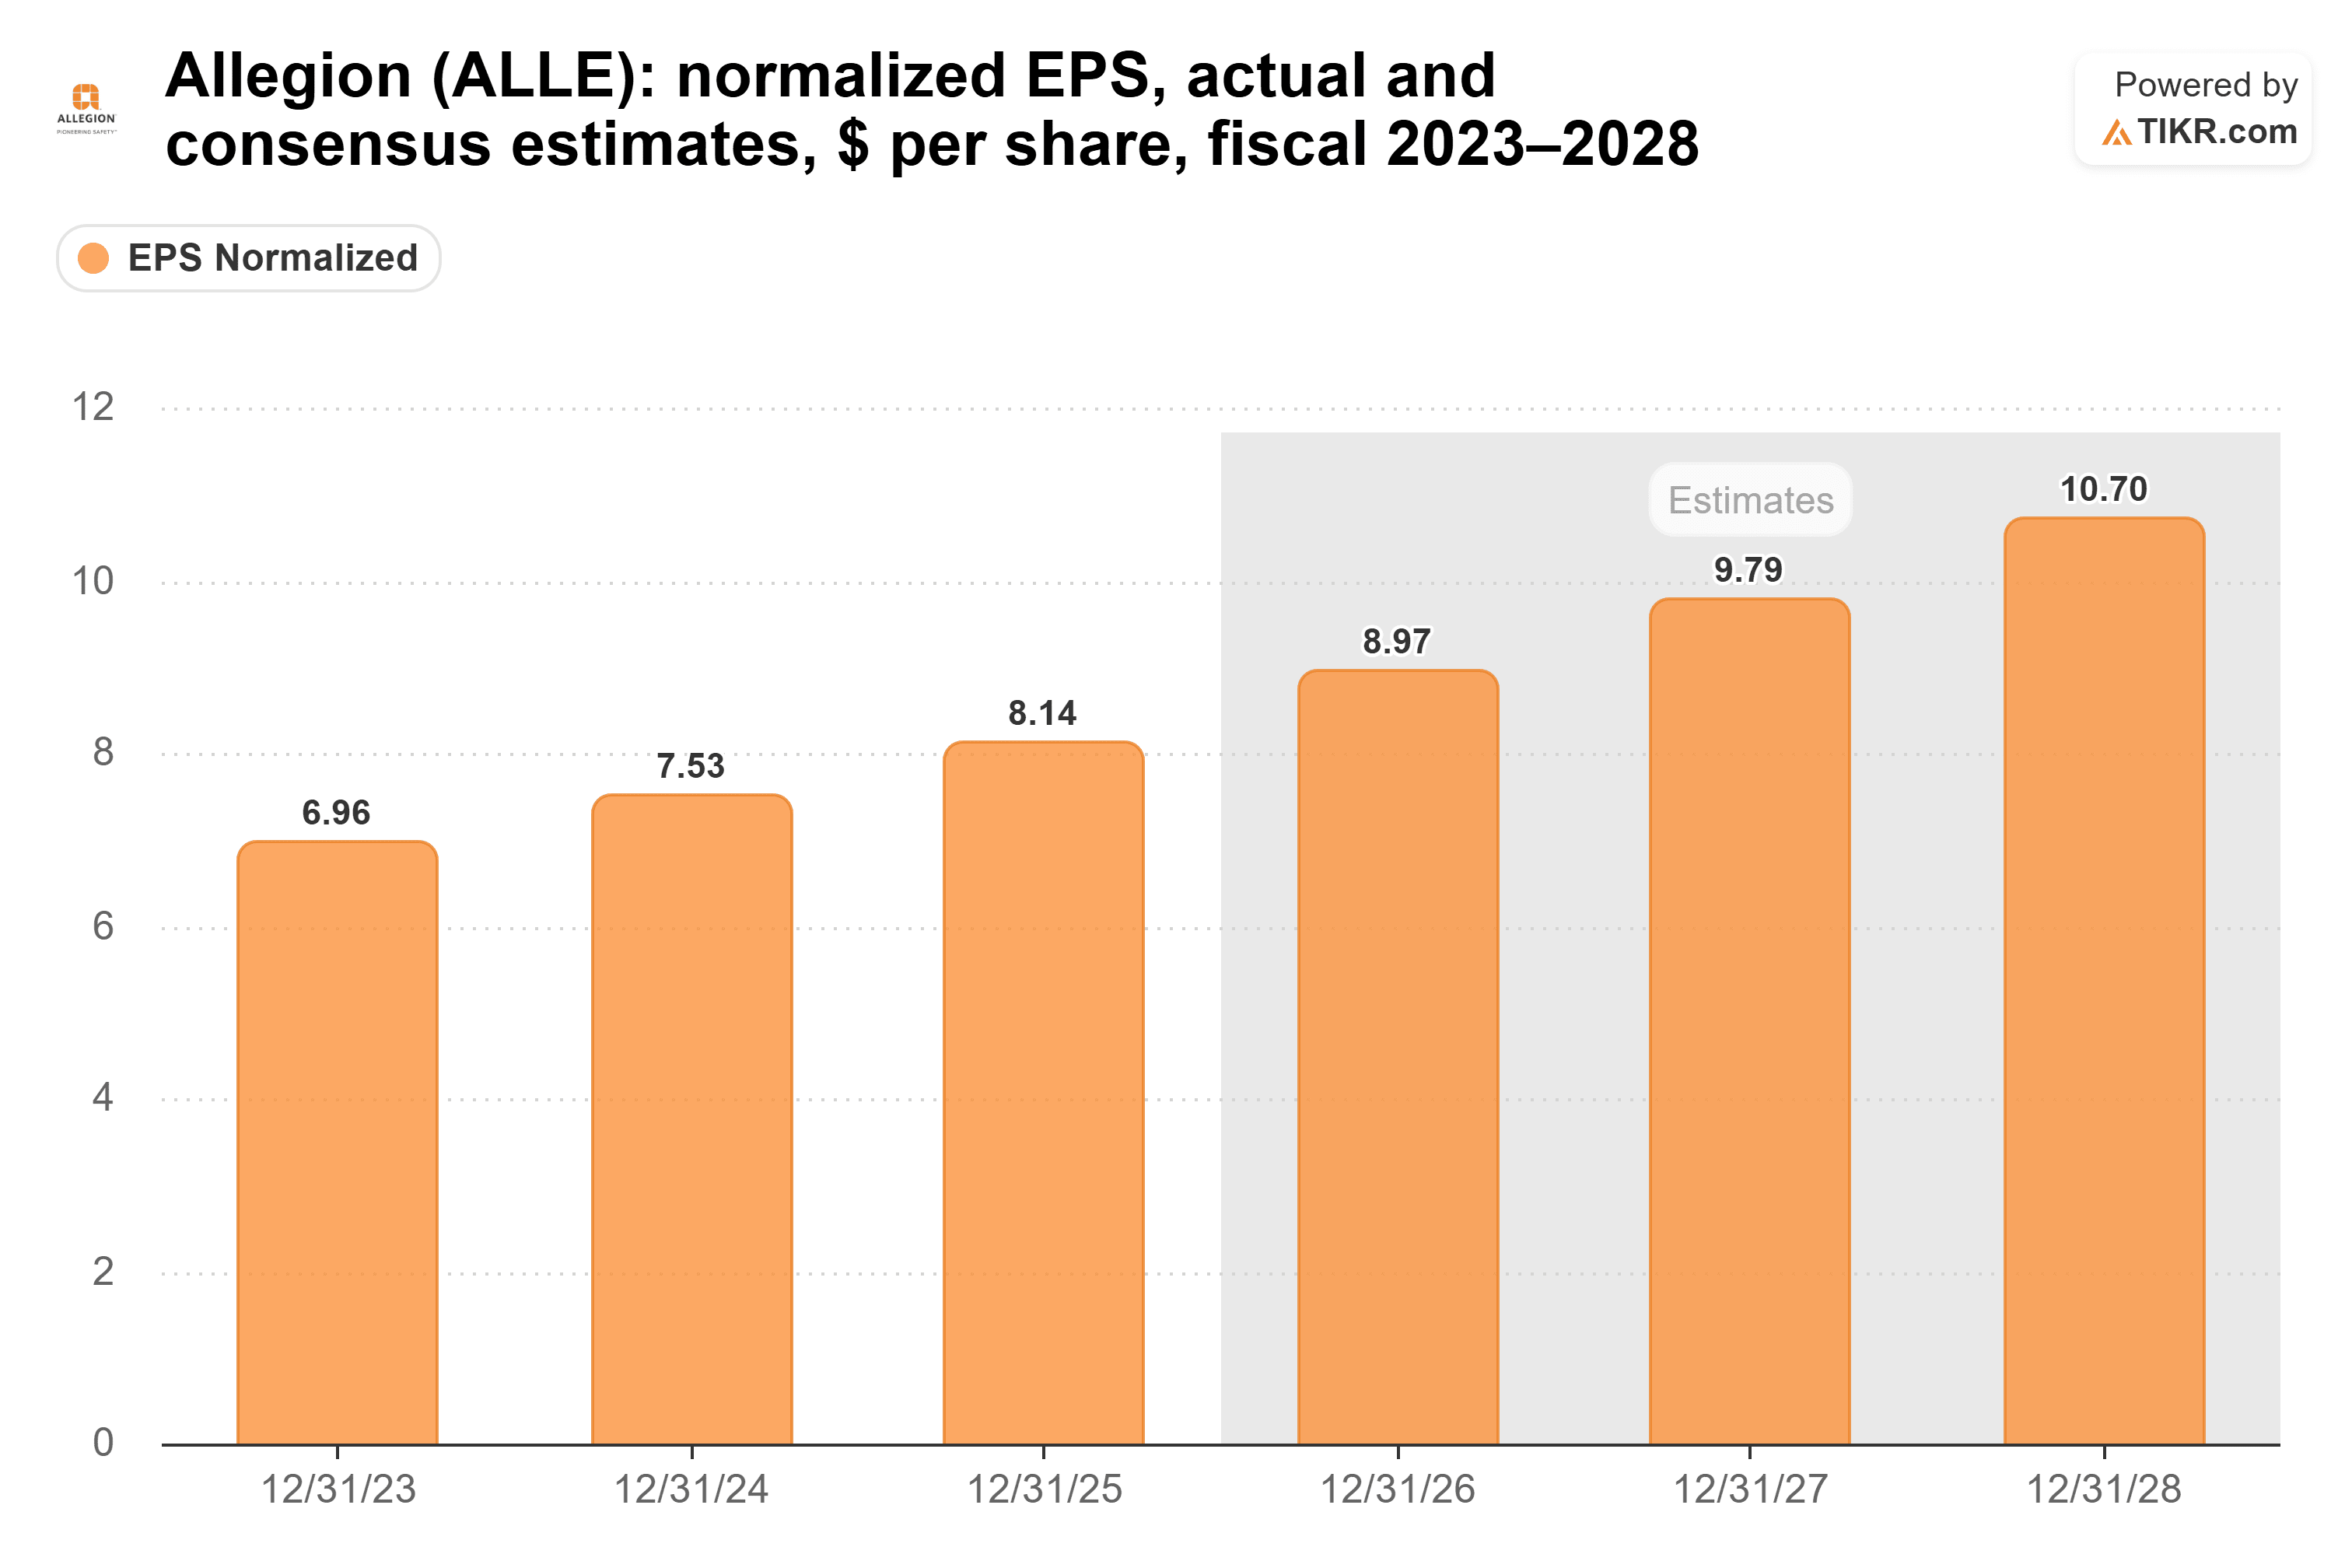
Those estimates came before today’s report, so expect the 2026 figure to rise toward the new range.
The raise also comes from the business itself. Tariff refunds added $19.9 million to reported operating income, but Allegion leaves them out of adjusted EPS.
Back to its average
At yesterday’s close, Allegion traded at 17x forward earnings. That’s below its five-year average of 18x and up from a five-year low of 14x in May…
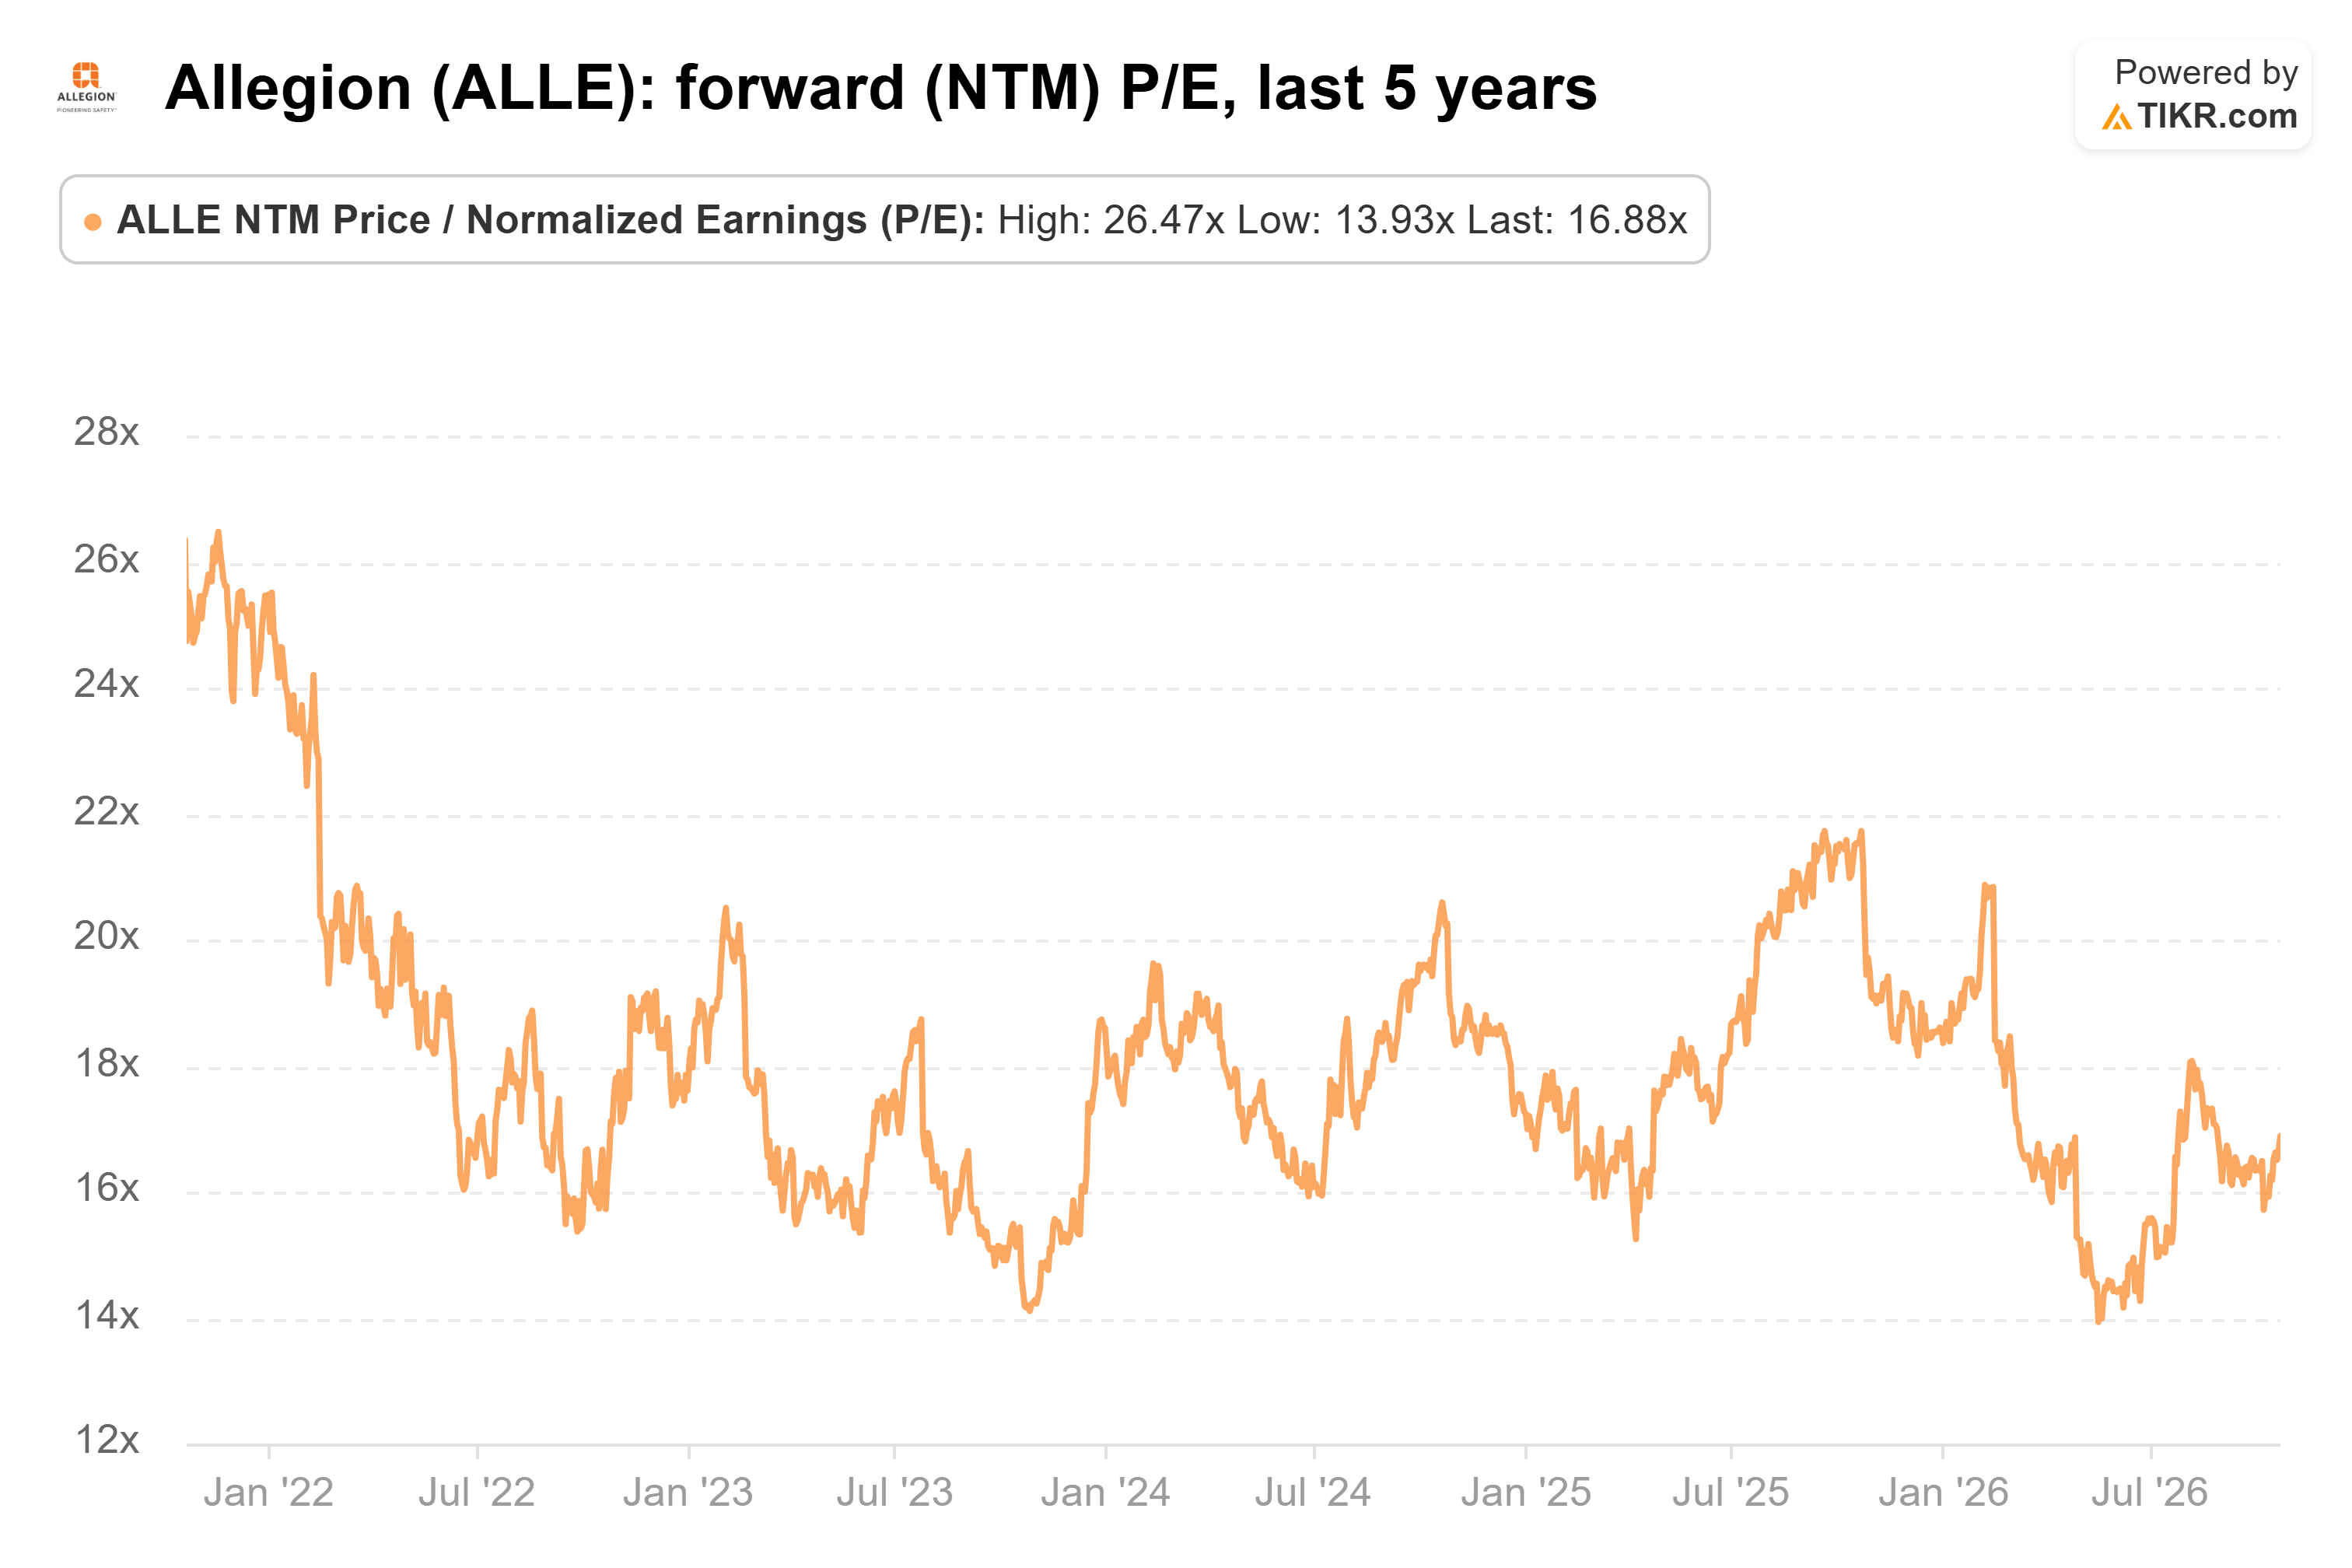
At this morning’s price, it’s closer to 18x.
My take: Allegion runs a high-margin business with one strong engine. At its average multiple, I think a raised outlook makes it worth owning from here. If International keeps shrinking, though, the whole company depends on the Americas, and a (probably likely?) slowdown in commercial building there would hit fast.
The next check is the fourth-quarter report early next year, and whether International volumes recover.
So what is Allegion stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Allegion could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


