Key Takeaways
- Verizon stock fell 4% today after its third-quarter revenue of $34.3 billion missed the $34.85 billion consensus, with equipment revenue down 9%.
- The miss came from selling fewer phones below cost, which is Verizon’s plan working, and its adjusted EBITDA margin hit a record 40.2%.
- Free cash flow rose 12% to $7.8 billion, and Verizon raised its full-year guidance for the third quarter in a row.
- Worries about SpaceX as a new wireless rival also hit the stock, and they’re the bigger risk to watch.
Verizon (VZ) beat on earnings this morning, added 406,000 postpaid phones and raised its full-year guidance for the third quarter in a row. The stock still fell 4% today on a revenue miss, with worries about SpaceX (SPCX) as a new wireless rival adding to the pressure.
CEO Dan Schulman says that one year into the company’s transformation, Verizon is “fundamentally stronger — operationally, financially, and competitively.”
The numbers mostly back him up.
What exactly happened
- Adjusted EPS of $1.31, up 8% and ahead of the $1.27 consensus
- 406,000 postpaid phone net additions, its best third quarter in five years, plus 137,000 new postpaid accounts, its best quarter in over a decade
- Postpaid phone churn of 0.94%, down from 0.98% a year earlier
- Revenue of $34.3 billion, up 1.5% but short of the $34.85 billion consensus
Verizon also raised its 2026 adjusted EPS guidance to $5.04 to $5.06, from $4.99 to $5.04. It now expects free cash flow growth to approach 12%, up from 9% to 10%.
TIKR tracks 25 analysts on Verizon. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Verizon, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Verizon’s Analyst Ratings
The miss is the plan
The shortfall came from equipment revenue, which fell 9% to $5.1 billion. Verizon says that was mainly because of fewer upgrades, as customers keep their phones longer, and its own choice to spend less on device subsidies.
That’s Schulman’s strategy: win customers with plans like Simplicity and loyalty perks, and spend less subsidizing phones. Verizon sells phones below cost, so selling fewer of them helps. The loss on its phone sales shrank to $707 million from $864 million a year earlier, and promotional spending to win new customers fell 41%.
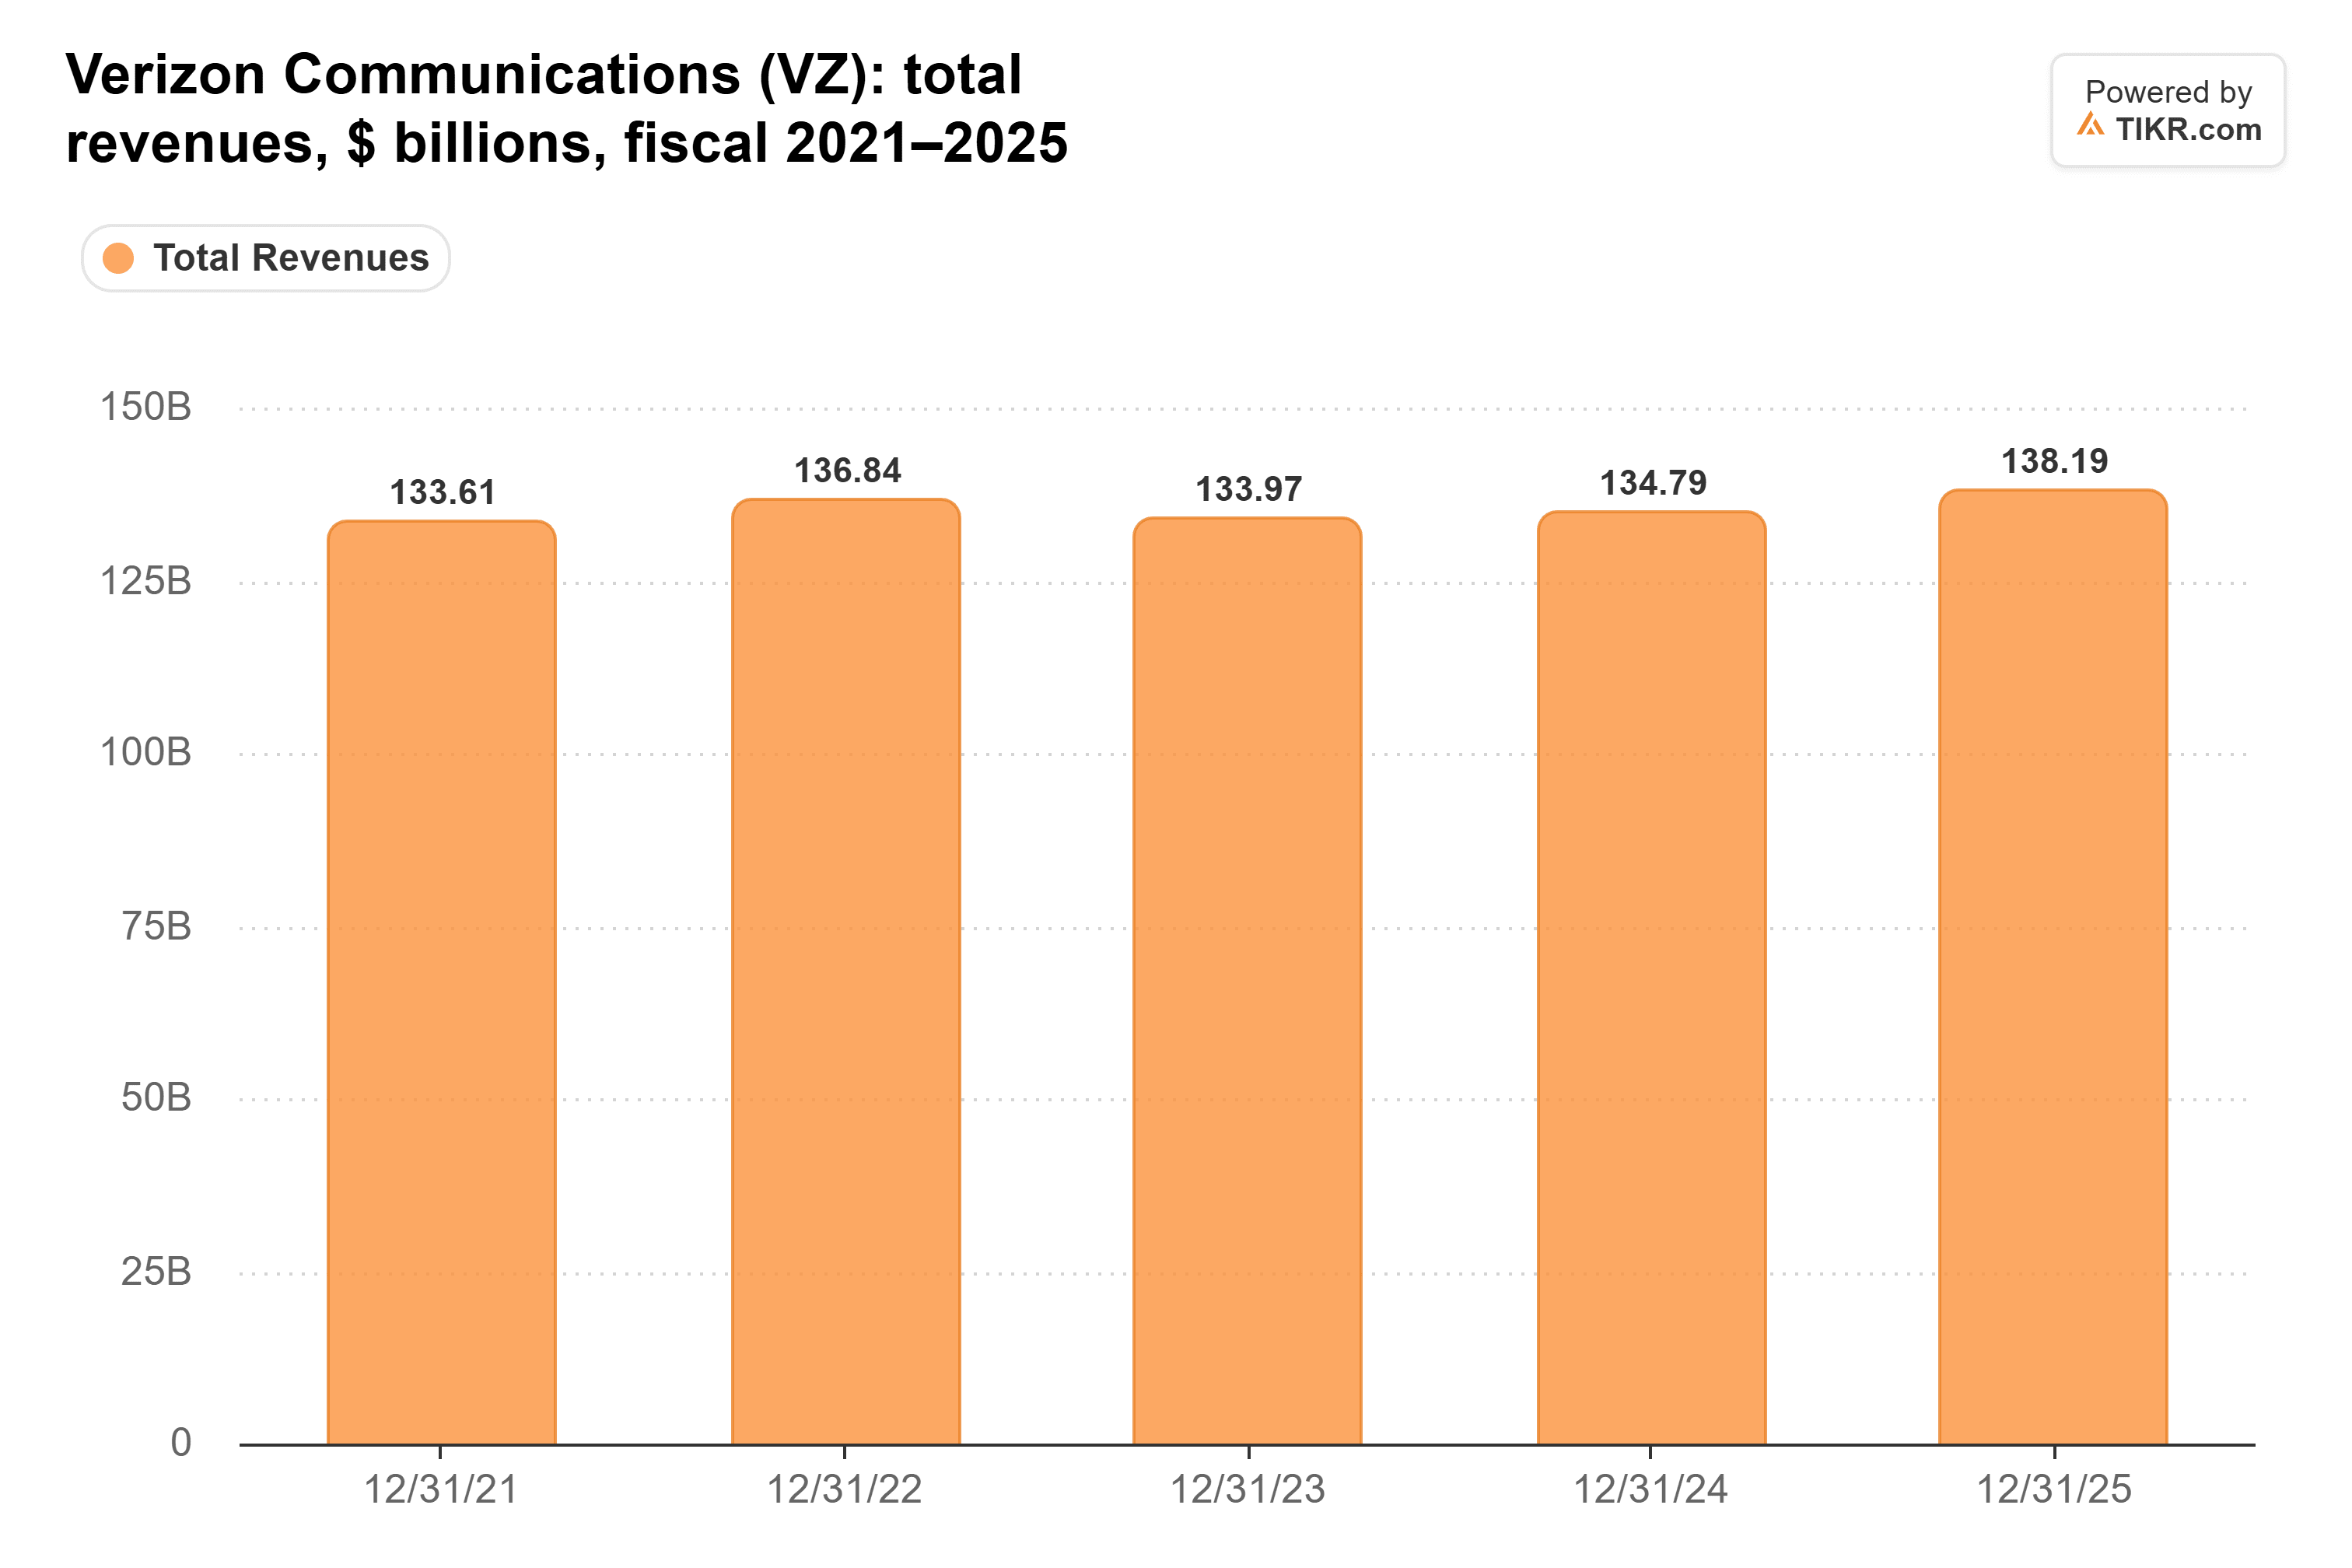
Besides, Verizon’s revenue has barely moved in five years, so the top line was never the growth story.
Margins and cash tell the real story
Adjusted EBITDA rose 8% to $13.8 billion, a record 40.2% margin against 37.8% a year earlier. And that’s turning into cash.
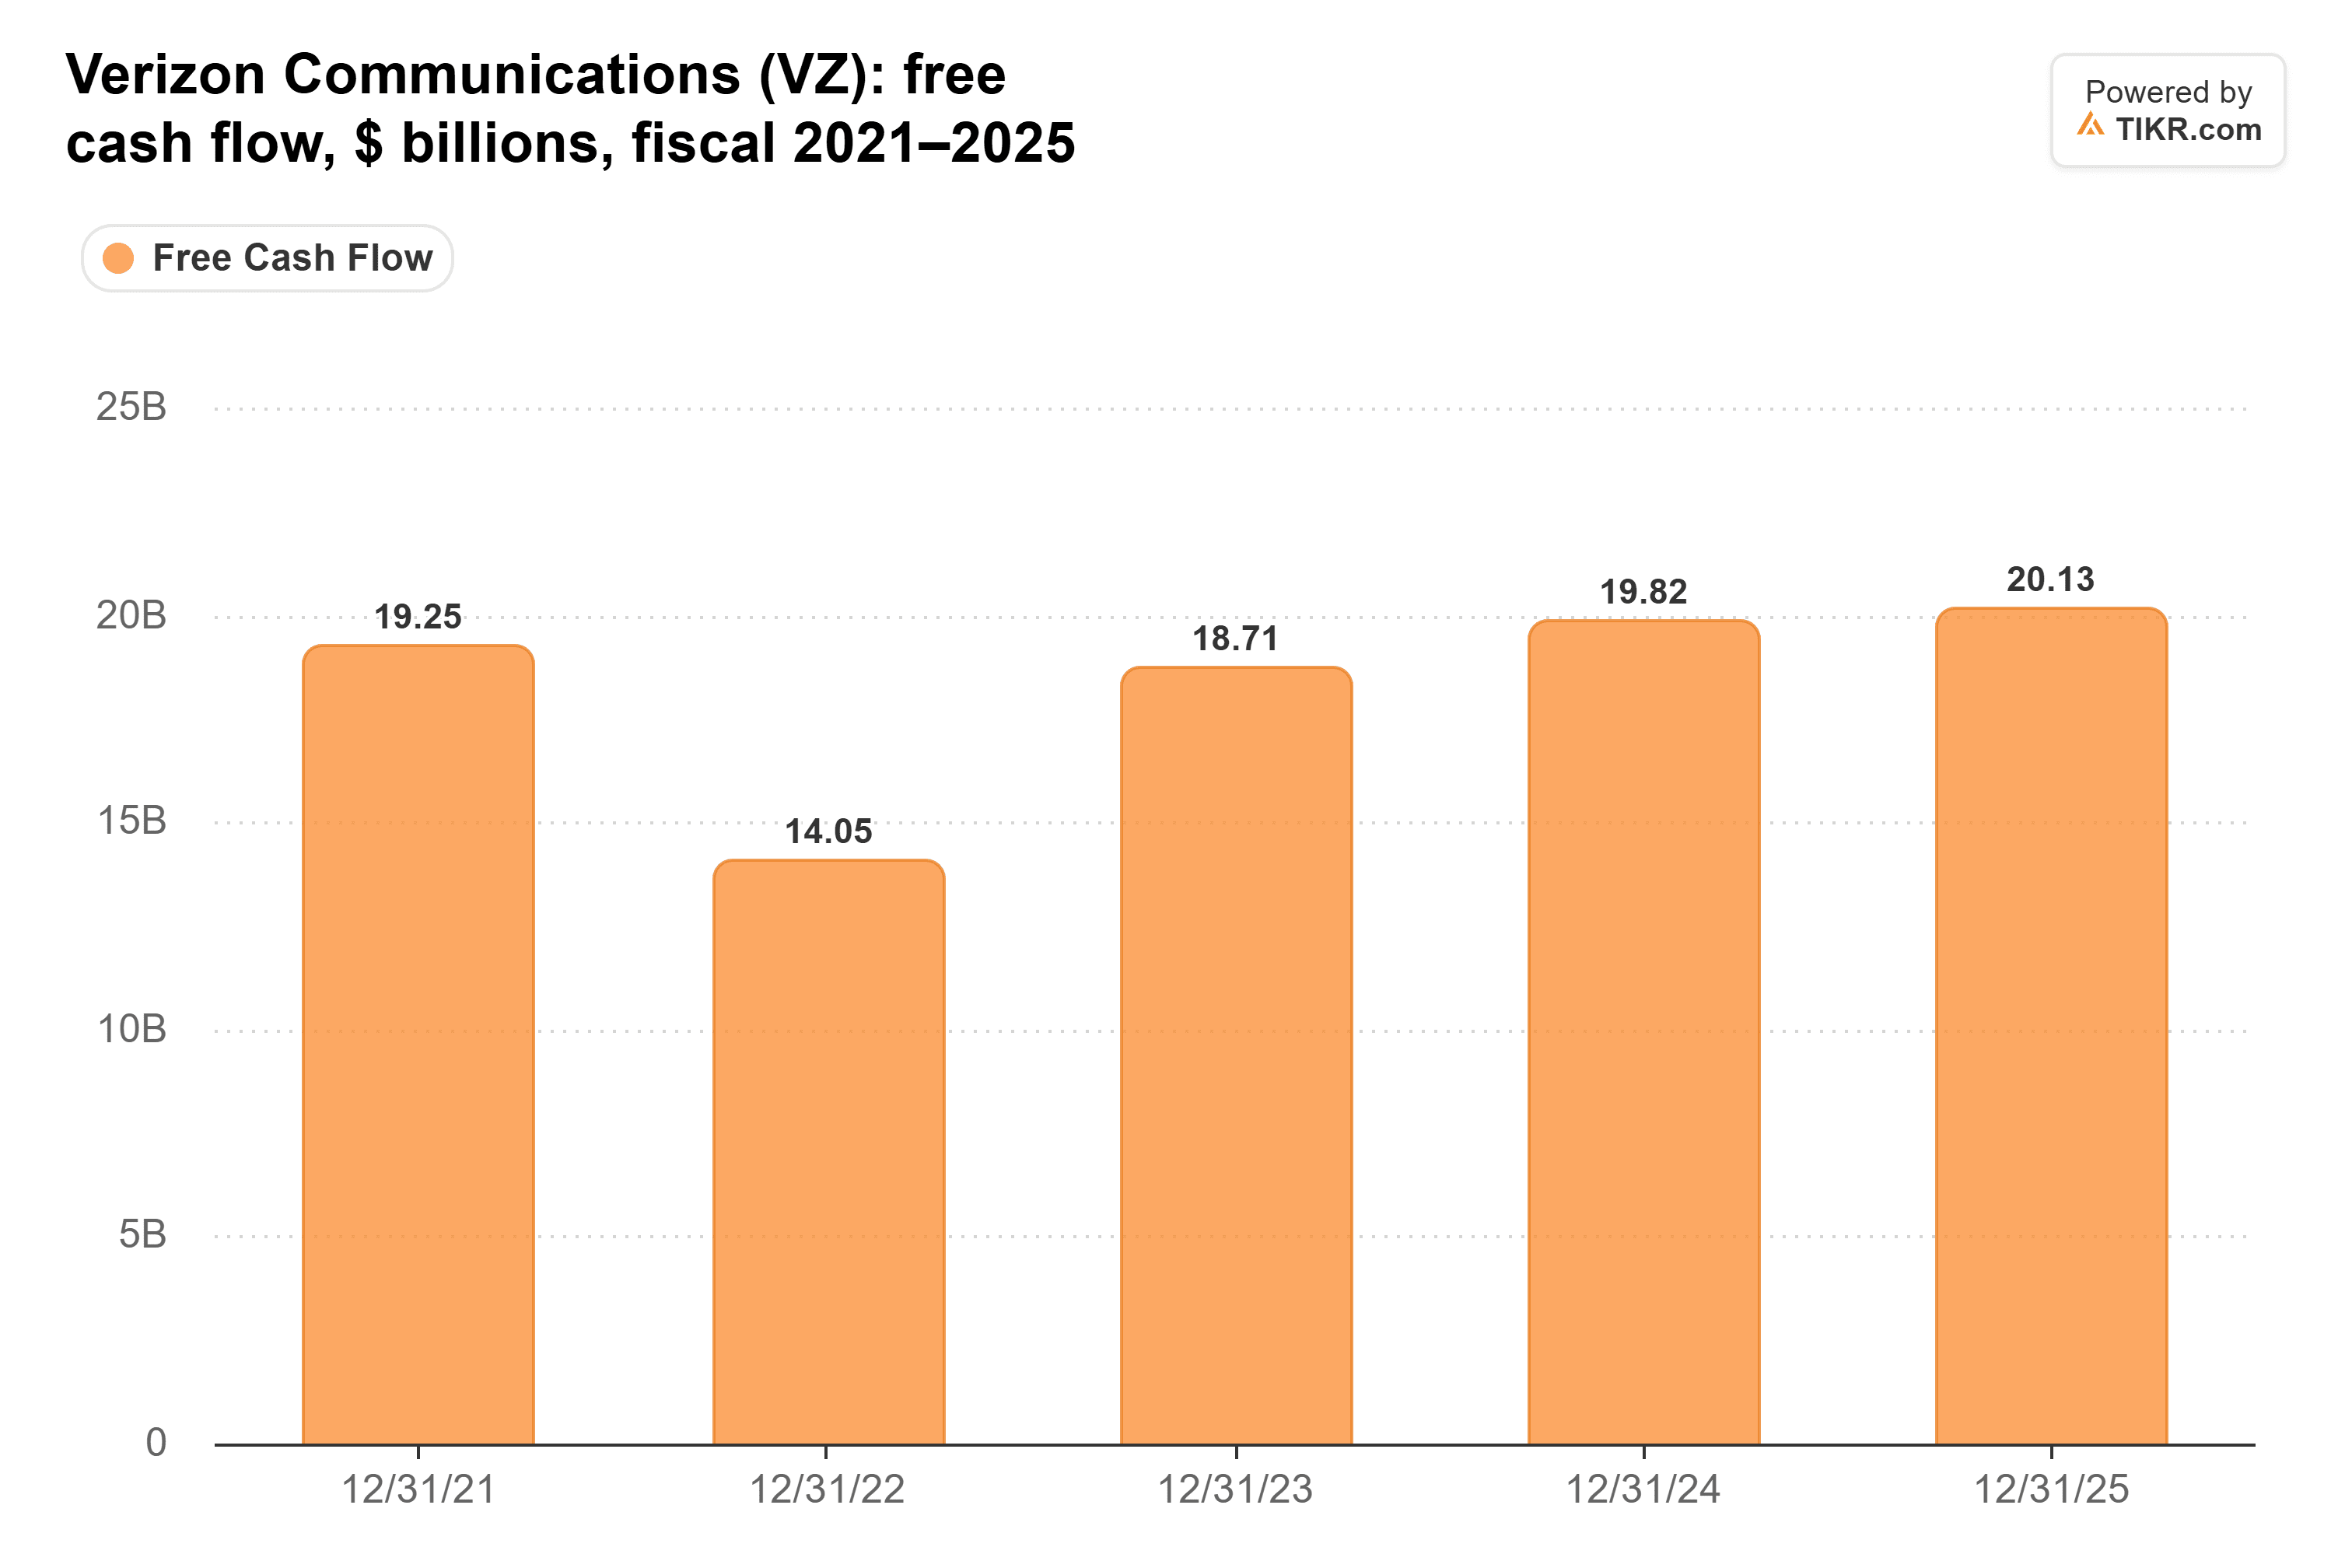
Third-quarter free cash flow rose 12% to $7.8 billion. Verizon’s new guidance puts 2026 at about $22.5 billion, more than any year on that chart.
Some of the gain comes from customers upgrading less, not just from spending discipline. The upgrade rate fell to 2.6% from 3.3%, and revenue per postpaid account still slipped 1.9% to $168.08.
Stronger, with one big unknown
My take: a revenue miss built on selling fewer money-losing phones is a good trade. With record margins and a third guidance raise, Schulman’s “fundamentally stronger” holds up.
Of course, SpaceX is the wild card. Its $8 billion spectrum deal still needs FCC approval. A ruling, or signed tower leases, would say far more about Verizon’s next few years than one quarter’s phone sales.
So what is Verizon stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Verizon could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!