Key Takeaways
- Chipotle fell 2.2% to a 52-week low on Friday, Oct. 23, and reports third-quarter results after the close on Wednesday, Oct. 28.
- RBC Capital Markets expects third- and fourth-quarter comparable sales to beat forecasts. How much of that reaches earnings depends on how much rising costs absorb.
- Chipotle announced a salmonella-related jalapeño removal after management gave its third-quarter guidance, so Wednesday is the first read on whether it hurt traffic.
- At about 23x forward earnings, a little over half its five-year average of 41x, the stock looks cheap if estimates hold.
Chipotle Mexican Grill (CMG) fell 2.2% on Friday, closing at $27.52 after touching a 52-week low of $27.31.
Then on Monday, RBC Capital Markets named Chipotle one of its preferred earnings ideas. The bank expects third- and fourth-quarter comparable sales growth to beat Street forecasts, and it thinks consensus estimates are too cautious.
RBC may be right about sales. But how much of that reaches earnings depends on how much rising costs absorb, and this quarter carries a risk the guidance may not cover.
A Rough Month for Chipotle Stock
The slide started with a takeover story that didn’t last. On Oct. 8, the Financial Times reported that Starbucks (SBUX) had worked with advisers on a possible bid for Chipotle, and Chipotle shares jumped about 6%. Four days later, a Starbucks spokesperson told CNBC the company is “not buying Chipotle.”
Then analysts turned more cautious. TD Cowen downgraded Chipotle to Hold on Oct. 21, saying October sales weren’t shaping up for the fourth-quarter pickup it expected. On Friday, Mizuho cut its price target to $37 from $43 but kept its Outperform rating.
TIKR Tracks 35 Analysts on Chipotle Mexican Grill. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Chipotle Mexican Grill, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Chipotle Mexican Grill’s Analyst Ratings
Margins Have to Steady
Excluding one-off items, Chipotle’s operating margin rose every year from 10.9% in 2021 to 17.3% in 2024, then slipped to 16.9% in 2025:
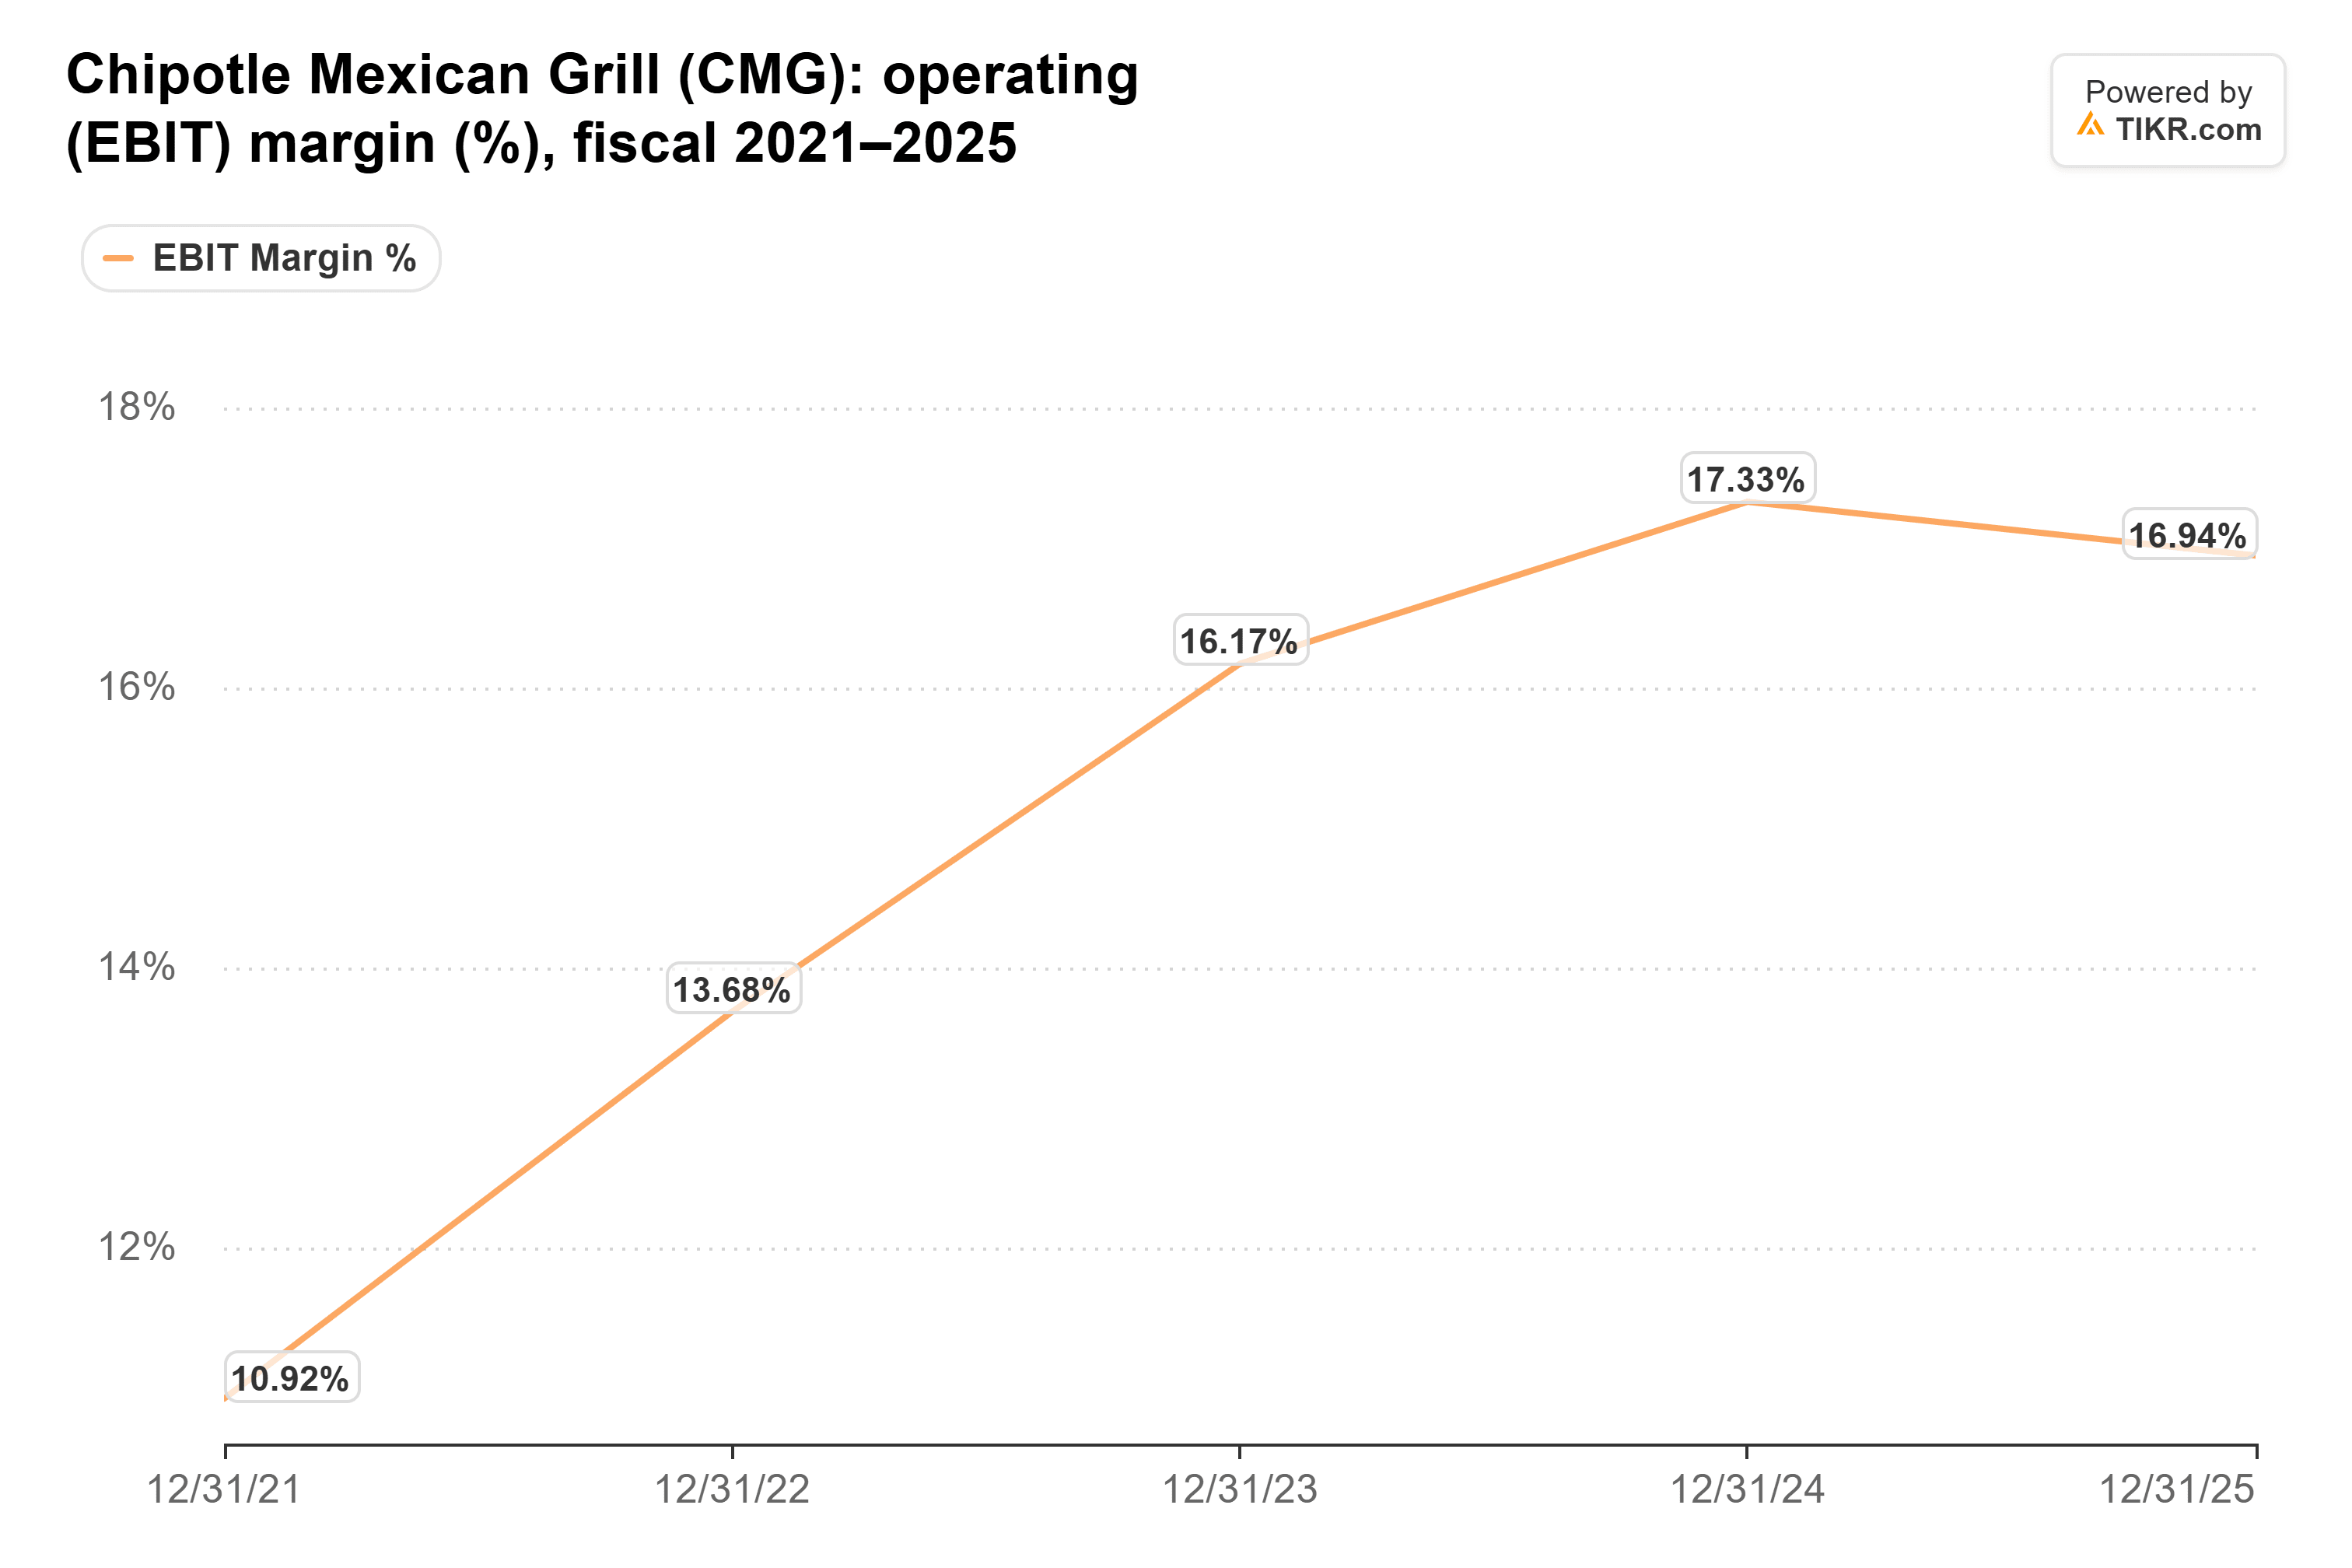
It’s still falling. Chipotle’s reported operating margin was 15.7% in the second quarter, down from 18.2% a year earlier.
Much of that is by choice. Management has kept menu price increases below cost inflation, and U.S. marketing spending rose 21% in the first half. For the third quarter, it guided labor to the mid-25% range of revenue and other operating costs to the mid-15% range, both above last year’s 25.2% and 15.0%. Management expects pricing to catch up with inflation from the fourth quarter.
The Estimates Have Stopped Falling, for Now
A year ago, analysts expected Chipotle to earn $1.42 a share in 2026. Today the consensus is $1.15, a bit below the $1.17 it earned in 2025:
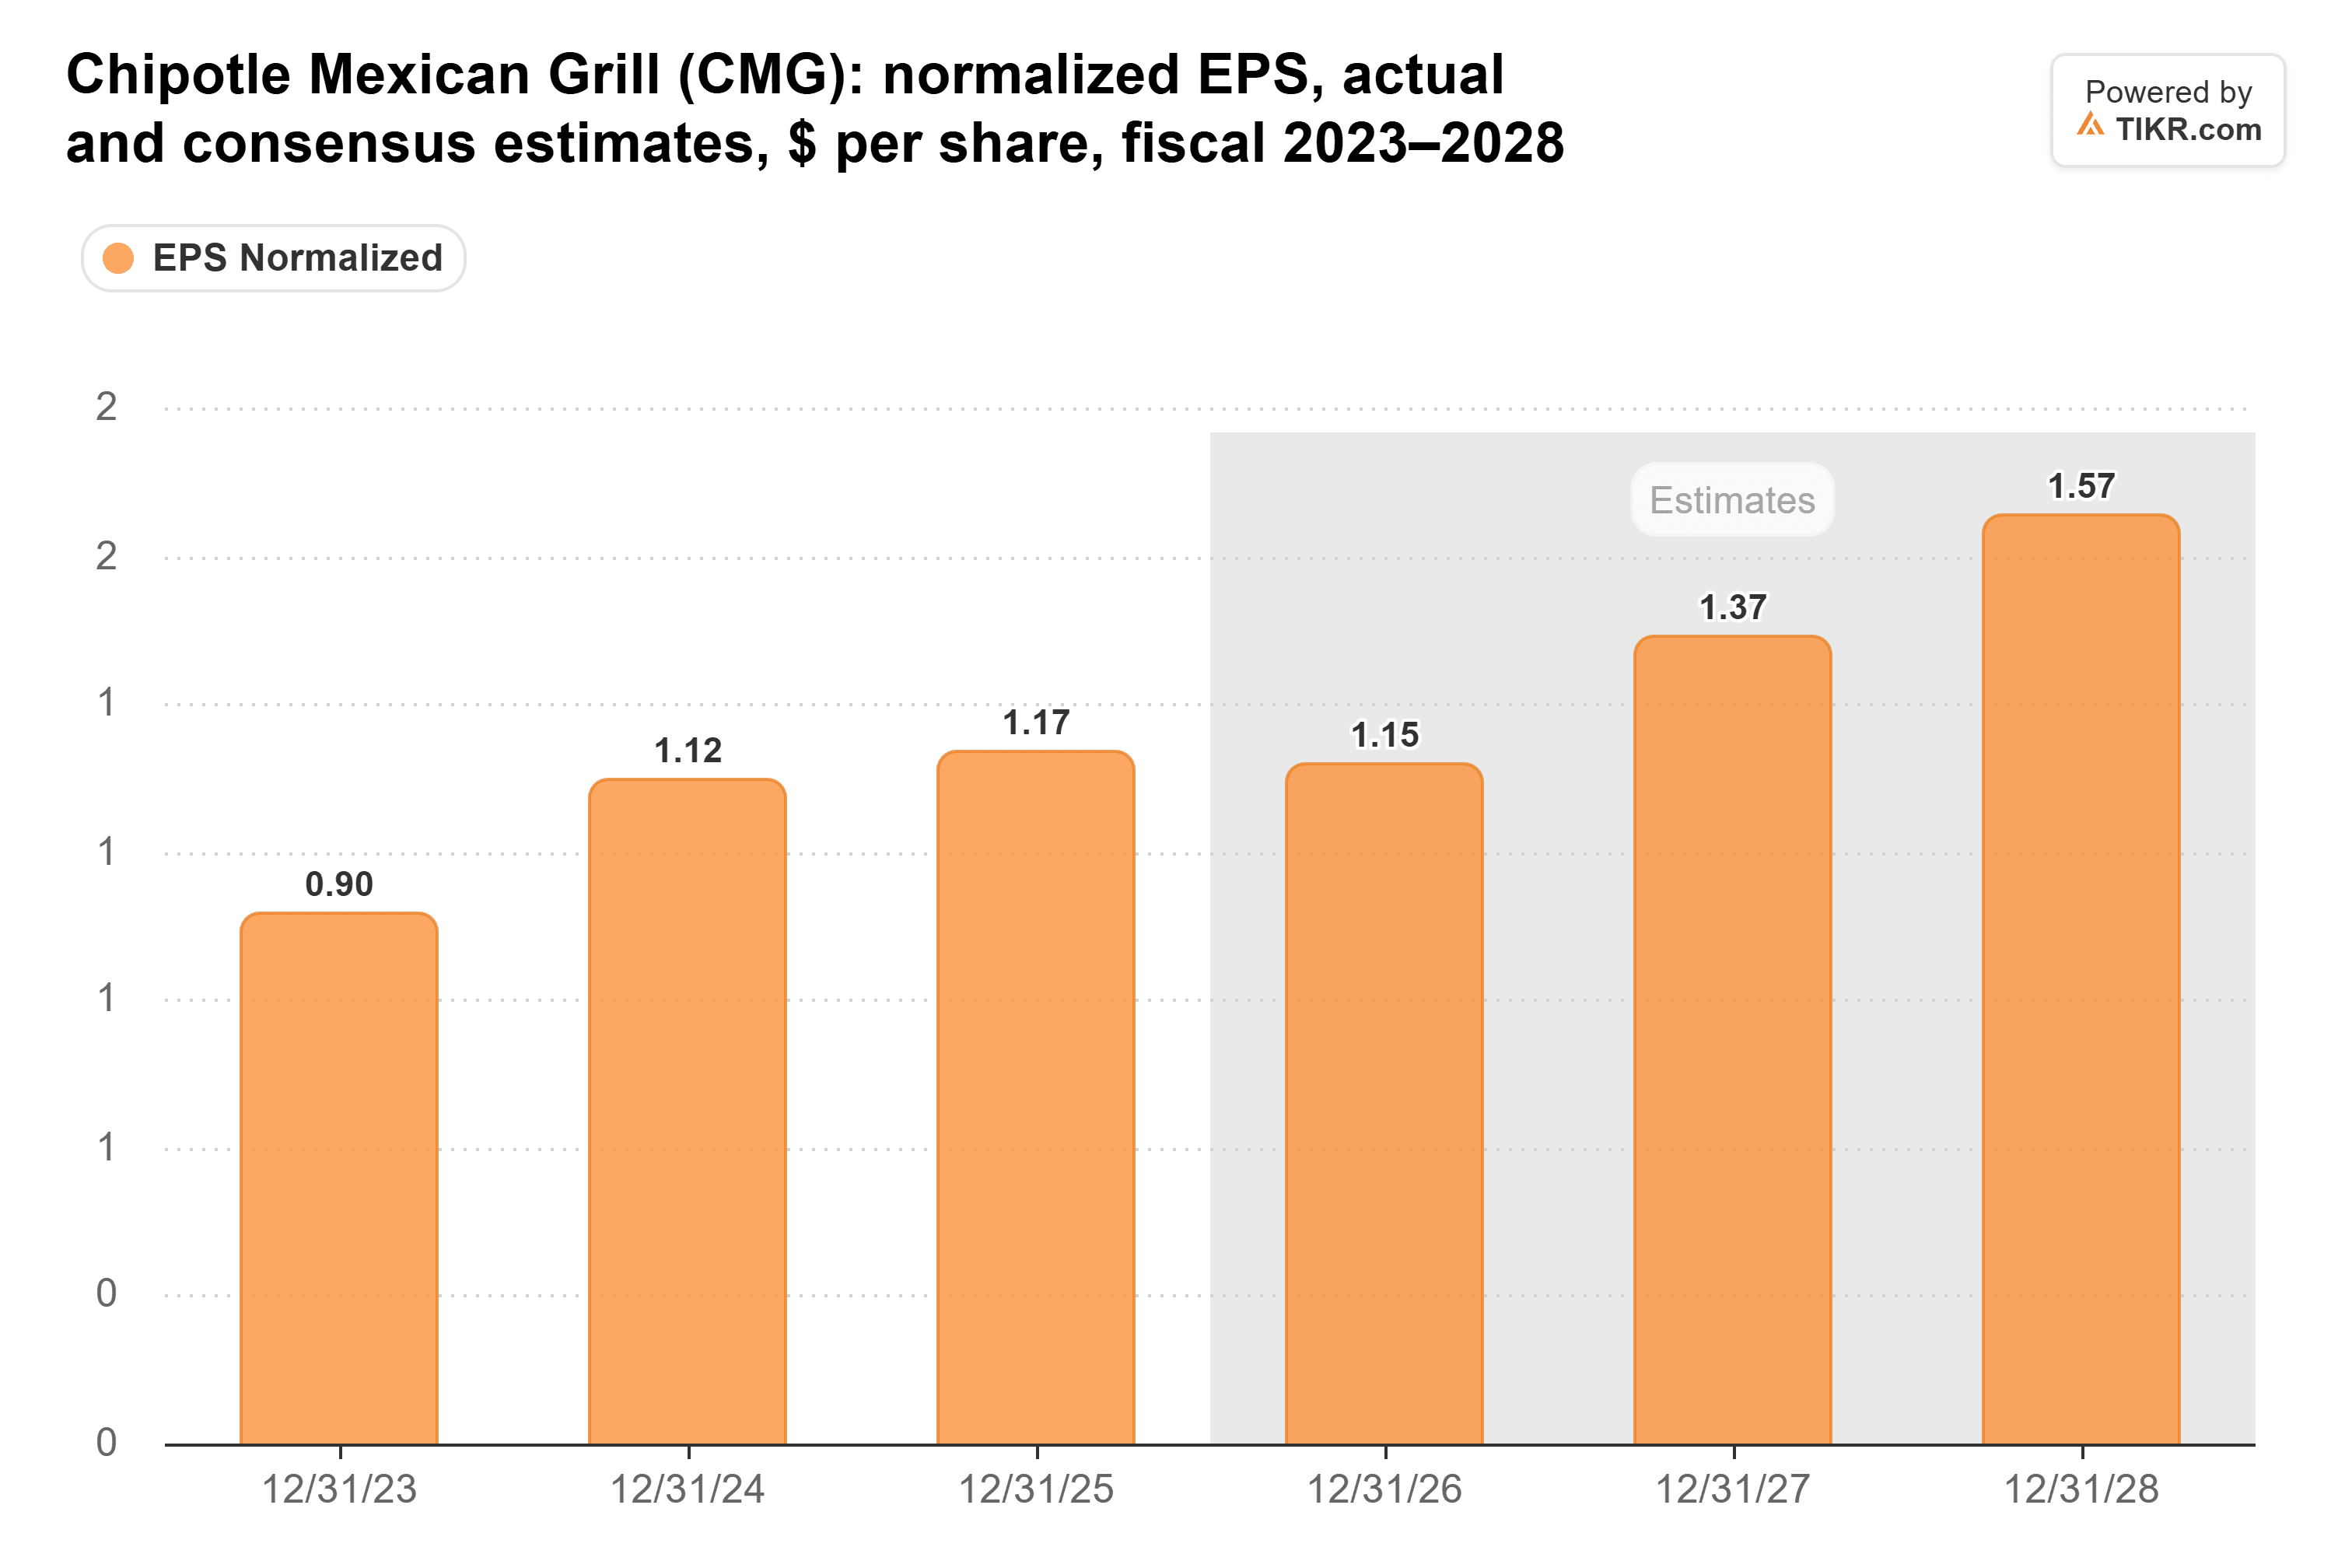
That $1.15 has held for three months and even edged up from $1.13. Analysts still expect a 19% jump to $1.37 in 2027.
The Food-Safety Risk in Chipotle’s Guidance
Management guided third-quarter comparable sales to about 1%. That includes a hit of roughly 2 points from a cyclospora outbreak that weighed on restaurant traffic across the industry in late July (Chipotle said the products involved aren’t on its menu).
Chipotle’s own problem surfaced after that guide. On Aug. 4, it pulled jalapeños from a single grower after health officials linked them to a salmonella outbreak, though the illnesses traced back to visits in June and July. The outbreak reached at least 345 illnesses in 27 states, CBS News reported. Wednesday is the first report to show whether the news cost Chipotle traffic.
What Wednesday Has to Show
- Comparable sales at or above the guided 1%, with transactions still growing after a 1.0% rise in the second quarter
- Any sign the salmonella outbreak hit traffic
- Management repeating that pricing catches up with inflation from the fourth quarter
- A fourth-quarter-to-date update strong enough to answer TD Cowen’s October concern
What 23x Says About Chipotle Stock
On Oct. 23, the day of the 52-week low, the stock traded at 22x forward earnings, its lowest in five years. Today it’s about 23x, a little over half its five-year average of 41x:
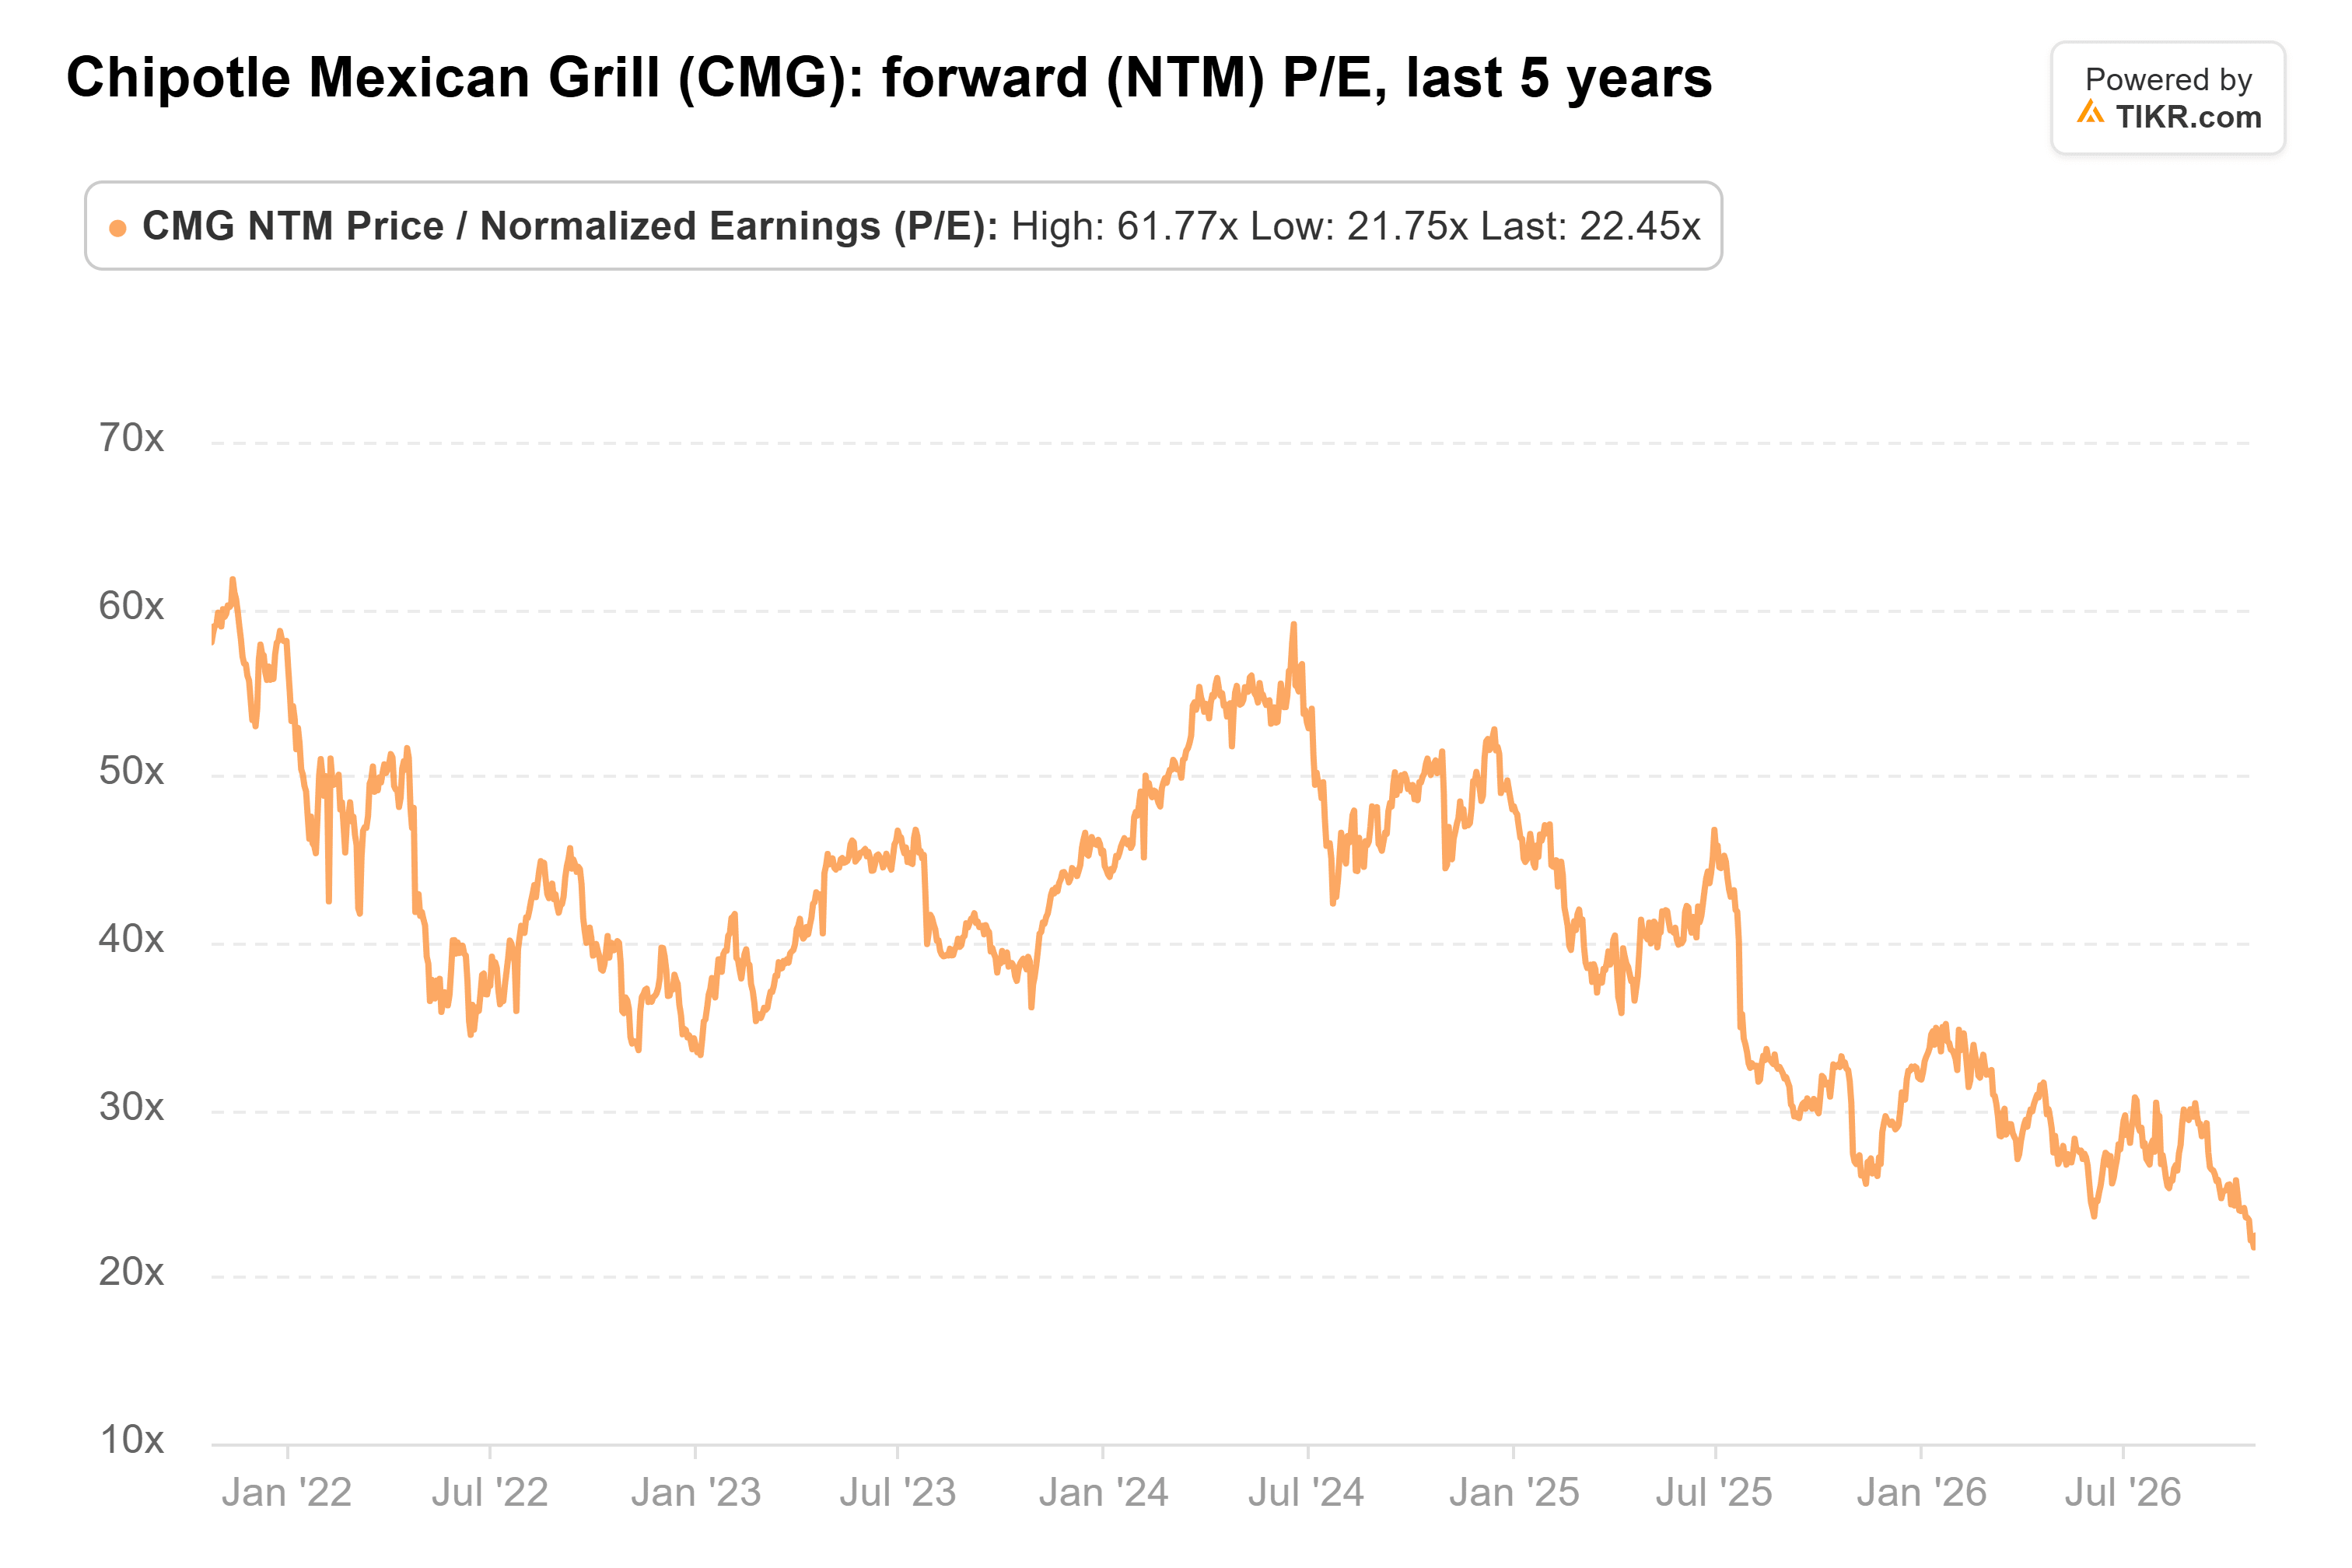
That multiple already absorbs a lot: a takeover that isn’t happening, a downgrade and two food-safety headlines. If comparable sales land near 1% and management says the salmonella outbreak did little damage, the $1.15 estimate should hold, and 23x looks cheap for it. I’d wait for that answer before calling a bottom. Chipotle’s 2015 outbreaks showed how long food-safety damage to traffic can linger.
So what is Chipotle stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Chipotle could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!