Boeing (BA) stock is down about 1.6% this morning (trading at about $185) after the planemaker reported a wider third-quarter loss than Wall Street expected on Tuesday, October 27. Shares had edged up about 1% in premarket trading before turning lower after the open. Boeing posted a core loss of $0.34 per share, against the $0.21 loss analysts expected according to LSEG data cited by CNBC. Revenue rose 4% to $24.2 billion.
The problem sits where it has sat for two years: the jetliner business. Commercial Airplanes lost $697 million in the quarter, a negative 6.5% operating margin. Boeing’s third-quarter release tied that loss to a weaker delivery mix, higher costs linked to future production rate changes, and pricier supply chain inputs. Net debt ended September at $25.2 billion, down from $25.9 billion in June.
The 737 Line Still Isn’t at 47
Boeing delivered 124 737s in the quarter, or about 41 a month. The company has been trying to stabilize the line at 47 a month since the summer. The release still describes that rate as a target in progress rather than a milestone reached. Total commercial deliveries came in at 161, one more than a year ago but 10 fewer than in the second quarter.
The margin went the wrong way too. Commercial Airplanes lost $885 million across the first half on $21.0 billion of revenue, a negative 4.2% margin. The third quarter was worse than that average, not better.
Defense Did Less Lifting Than It Looks
On the surface, Boeing’s other two businesses carried the quarter. Defense revenue jumped 15% to $7.9 billion, extending a climb from $6.3 billion in early 2025.
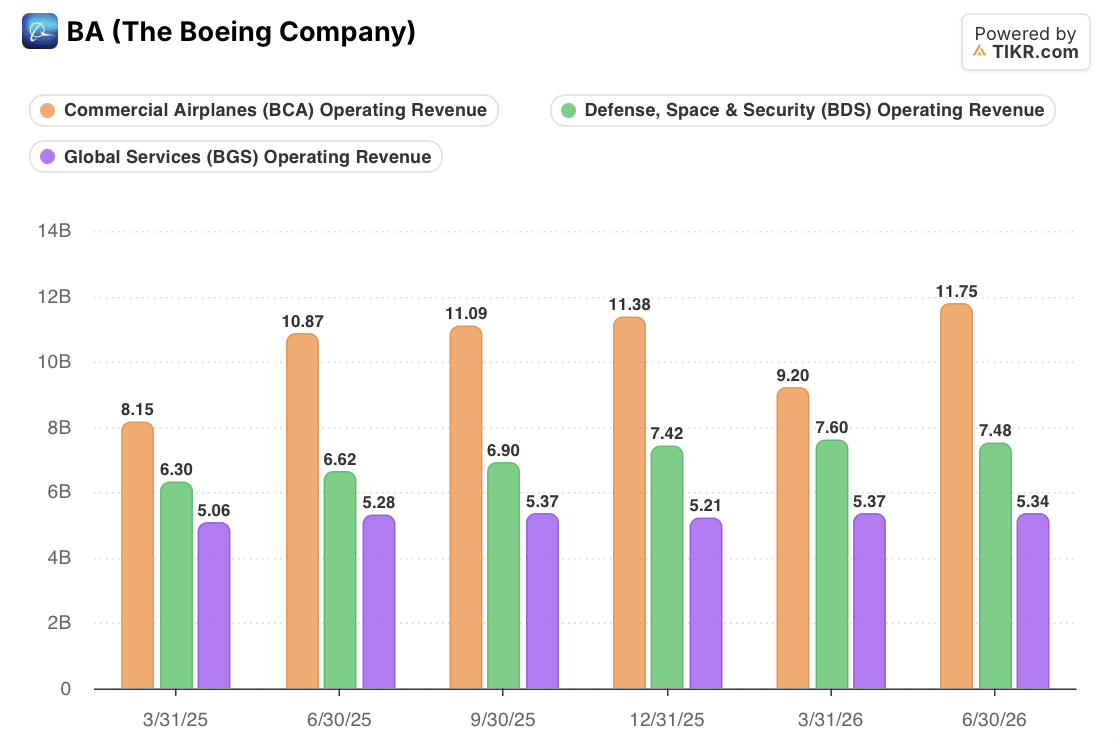
But Defense’s 6.2% margin includes a $252 million gain from selling HRL Laboratories. Strip that out and the unit earned about $240 million, a 3.0% margin. Do the same to the whole company and Boeing’s $204 million core operating profit becomes a loss of roughly $48 million.
Global Services is the real offset. It earned $1.02 billion at an 18.3% margin, enough to cover the jetliner loss with $322 million to spare. Its revenue has barely moved in six quarters, though, so it can absorb losses rather than outgrow them.
TIKR Tracks 29 Analysts on Boeing. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Boeing, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Boeing’s Analyst Ratings
The Cash Bar Gets Higher in Q4
Free cash flow came in at $464 million, after roughly $700 million of Justice Department settlement payments. That’s three positive quarters out of the last four.
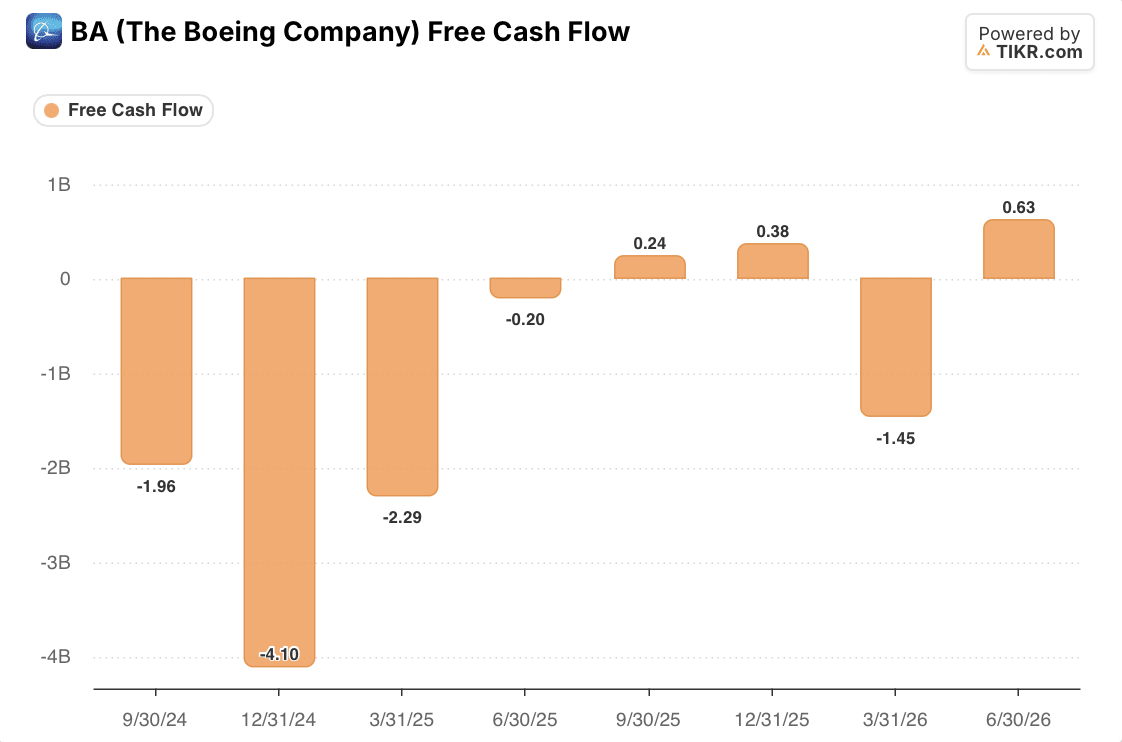
The fourth quarter now carries the year. Nine-month free cash flow sits at negative $359 million. Hitting Boeing’s $1 billion to $3 billion target for 2026 means generating about $1.4 billion to $3.4 billion in the final three months. The low end alone is more than double Boeing’s best recent quarter, the $0.63 billion it produced in the second quarter.
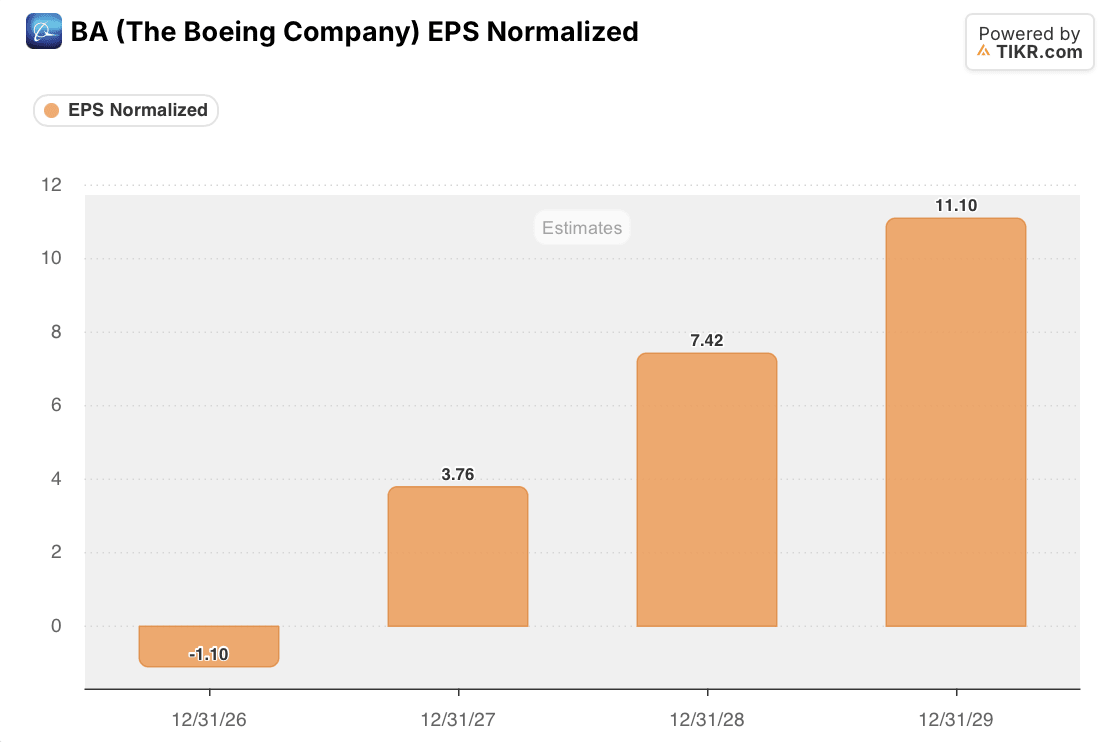
The Street expects an even bigger jump. Normalized EPS estimates swing from a $1.10 loss in 2026 to $3.76 in 2027. Holding today’s 793 million diluted shares constant, that’s about $3.0 billion of earnings, a $3.9 billion improvement on the 2026 loss.
Commercial Airplanes is the biggest lever in that recovery: it lost $1.58 billion over the first nine months of 2026, while Services already earns about $1 billion a quarter. That also matters for GE Aerospace (GE). Its CFM joint venture supplies the LEAP-1B engines on every 737 MAX, so a slower 737 ramp caps how fast that engine demand can grow.
What Boeing Owes Investors on Today’s Call
Management speaks at 10:30 a.m. ET on Tuesday, and the number that matters is the $1 billion to $3 billion cash target. Holding it means betting on a fourth quarter twice as strong as anything Boeing has produced lately. Trimming it would weaken the 2026 cash outlook, and management’s explanation would matter: the 737 ramp, working capital timing, and factory spending all move the number.
Until the jetliner margin stops sliding, defense contracts and services revenue are buying Boeing time, not finishing the turnaround. A firm date for a stable 47-a-month 737 line would be worth more to the stock than any defense win.
So What Is Boeing Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what BA stock could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value The Boeing Company for free→
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!