Key Takeaways
- Marvell is up 82% in 2026, even after losing about half its value since its June high.
- NVIDIA’s $2 billion investment, Jensen Huang’s trillion-dollar call and 46% data center growth last quarter drove the run.
- Most of the fall came from the all-stock Lumentum deal, which adds about 49% to Marvell’s share count, and from an election-driven chip selloff.
- Analysts kept raising their earnings estimates right up to the deal, which makes Marvell a stock to add to slowly ahead of its Dec. 1 report.
Marvell Technology (MRVL) is up 82% in 2026 after a wild ride. The stock nearly quadrupled by its June 18 intraday record after NVIDIA (NVDA) CEO Jensen Huang called it “the next trillion dollar company,” then gave back about half after Marvell agreed to buy Lumentum (LITE) in a $115 billion all-stock deal.
So is it time to take profits? Not yet. What drove the run is still in place, and most of the fall came from the deal and from a selloff the whole chip group shared.
NVIDIA lit the fuse
NVIDIA bought $2 billion of Marvell convertible preferred stock on March 31, a vote of confidence from AI’s top chipmaker. Then, at Computex on June 2, Huang made his trillion-dollar call, and Marvell jumped 32.5% that day, its biggest one-day gain on record. Even now, at about $139 billion in market value on Nov. 9, Marvell would need to grow roughly sevenfold to reach Huang’s mark.
The business earned the run
Marvell’s own numbers kept climbing all year. In the fiscal second quarter, which ended Aug. 1, revenue rose 37% to a record $2.739 billion. Data center revenue jumped 46% to $2.17 billion, or 79% of sales. Management has raised its fiscal 2028 revenue outlook three times since March, from about $15 billion to about $20 billion at its Oct. 6 Investor Day. And on Nov. 2, Marvell said preliminary third-quarter revenue came in line with its guidance.
Consensus has normalized EPS reaching $12.60 in fiscal 2029, more than four times the $2.84 it posted in fiscal 2026 (the year ended January 2026):
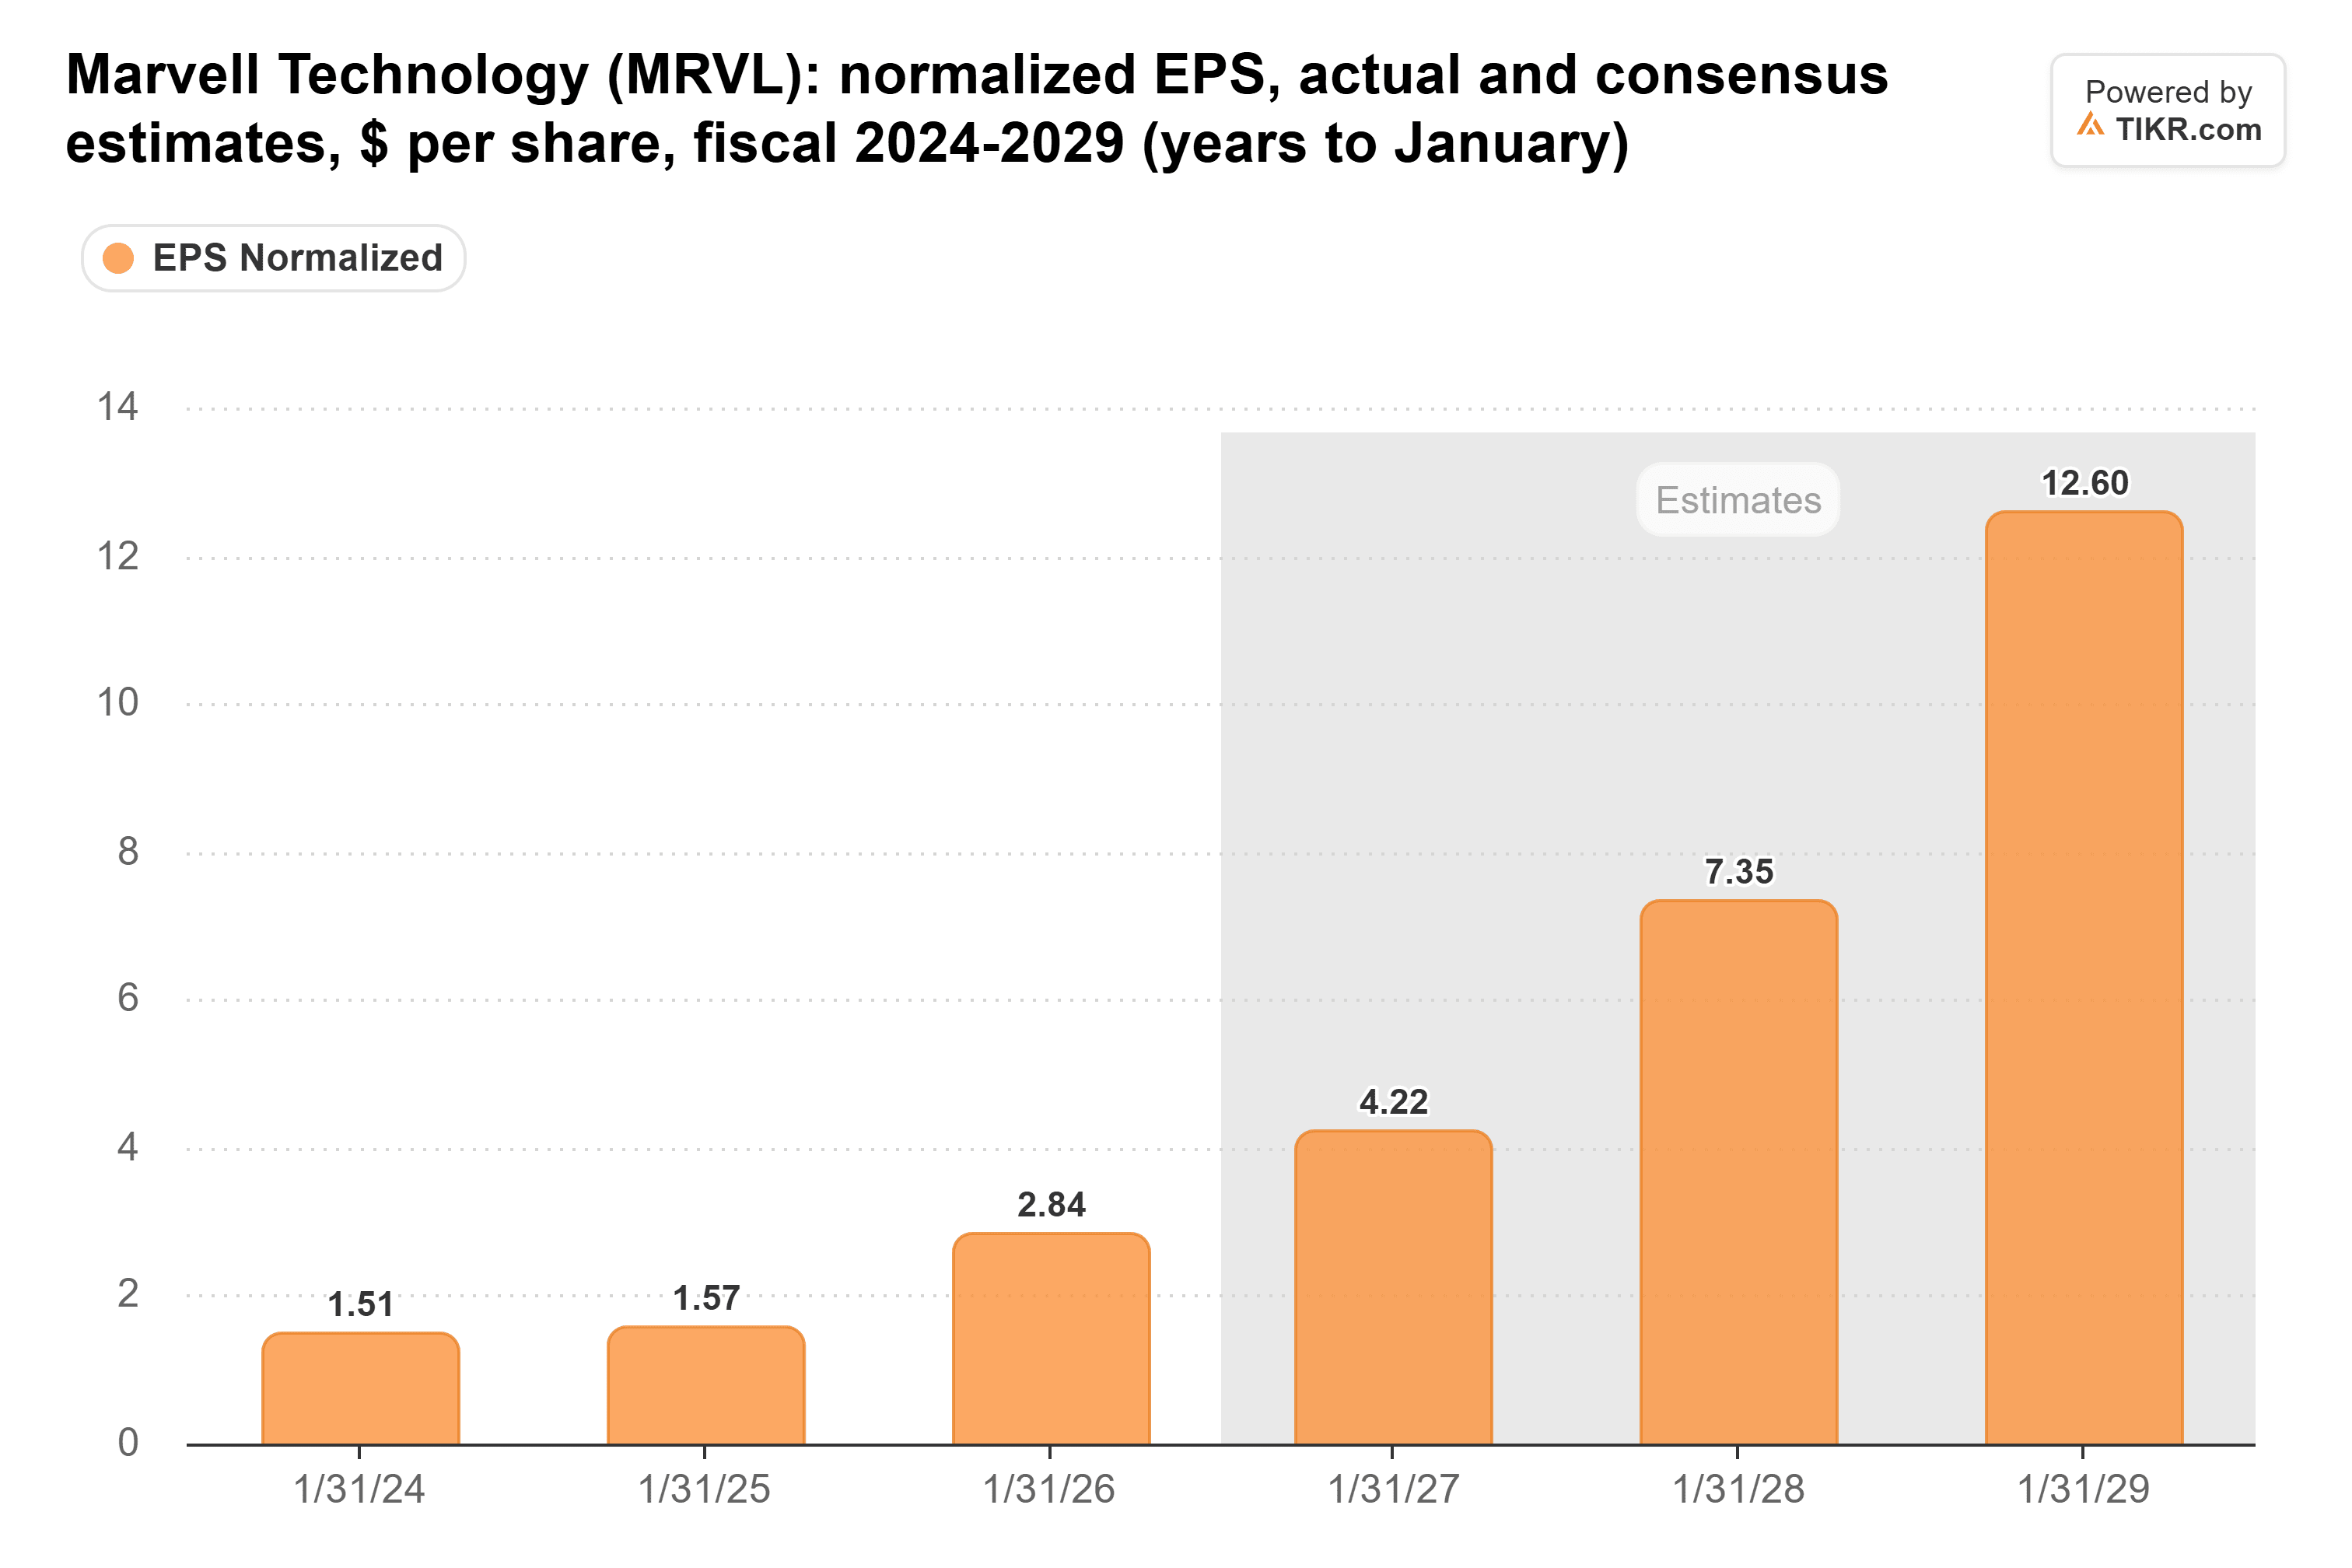
(Those estimates may not yet reflect the Lumentum deal.)
TIKR tracks 44 analysts on Marvell. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Marvell, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Marvell’s Analyst Ratings
The Lumentum deal gave half of it back
Under the deal, announced Nov. 2, Lumentum holders get 4.5 Marvell shares for each share, worth about $1,132 at Oct. 28 prices, a 23.9% premium. The deal adds about 49% to Marvell’s share count. CEO Matt Murphy called AI’s shift to optics “an opportunity that comes along once in a generation,” and Lumentum is growing fast: its fiscal first-quarter revenue rose 136.5% to $1.26 billion.
But investors balked at the price, and TD Cowen (to Hold, $175 target) and Bank of America (to Neutral, $225 target) both downgraded Marvell. The ratio is fixed, so the offer shrinks with Marvell’s stock: at the Nov. 9 close, it was worth about $696 per Lumentum share. Lumentum, still up 62% in 2026, closed about 14% below that, a discount for the long wait and the risk the deal never closes. Then the election-driven chip selloff on Nov. 4 and 5 hit the whole group.
Estimates rose right up to the deal
Analysts were raising their numbers until the very end: in the 90 days to Nov. 2, the consensus fiscal 2028 normalized EPS estimate climbed to $7.36 from $6.24. Meanwhile, the forward P/E fell from a June peak near 70x to 25x on Nov. 6, below its 33x five-year average:
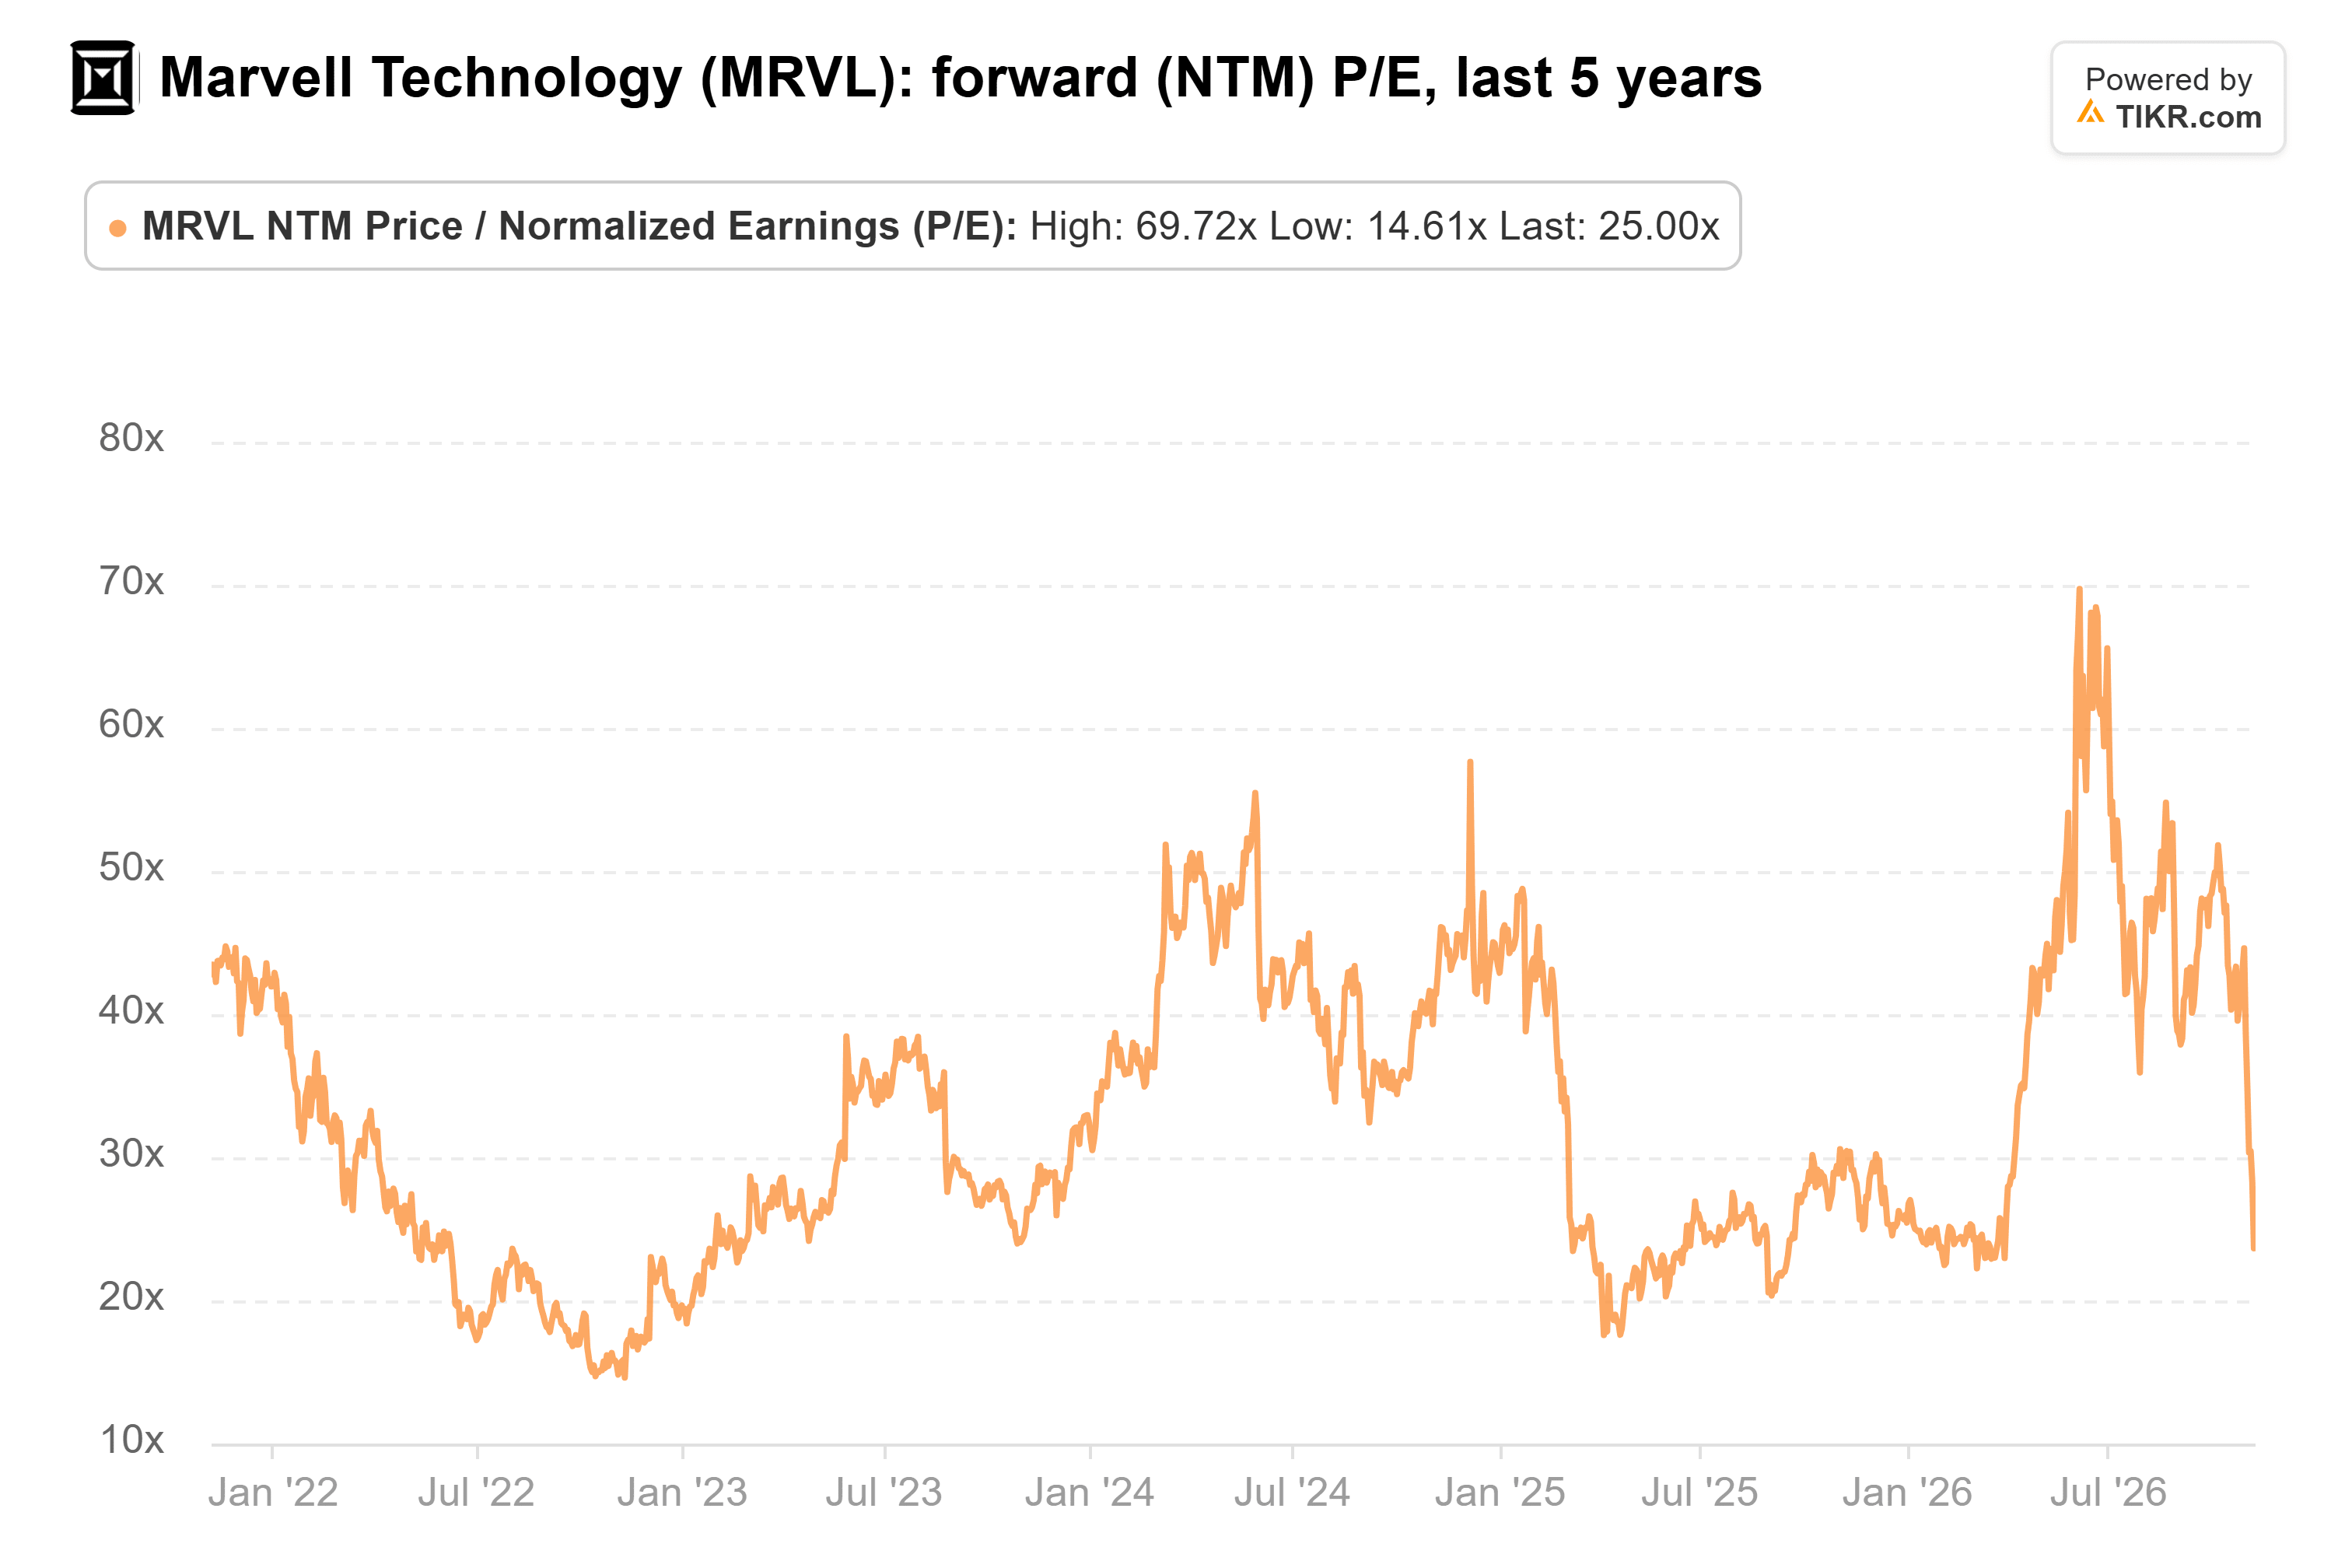
Wall Street’s average price target on TIKR, about $311, is still roughly double the Nov. 9 close.
Buy more, but slowly
The deal won’t close until the first half of 2028, and regulators, China’s included, have to sign off first. Still, Marvell’s core business is accelerating, and the stock costs less relative to earnings than its five-year average. That argues for adding slowly rather than taking profits.
The next test is the Dec. 1 report, where fourth-quarter guidance matters more than the third quarter itself. An outlook that keeps the roughly $20 billion fiscal 2028 target intact would show the core business is still on course. NVIDIA reports first, on Nov. 17, with a read on the same cloud budgets. And if election winners who promised to get tougher on data center construction follow through, the selloff could return.
So what is Marvell stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Marvell could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!