Key Takeaways
- Marvell shares have fallen about 44% since October 28, after it agreed to buy Lumentum in an all-stock deal valued at $115 billion.
- The fixed 4.5-share exchange ratio means Lumentum holders’ payout has shrunk to about $635 per share from $1,132 at signing.
- Data center revenue grew 46% last quarter, and CEO Matt Murphy said AI bookings “remain exceptionally robust.”
- The December 1 report, guided to $3.15 billion of revenue, will show whether the core business can outrun the dilution worries.
Marvell Technology (MRVL) made a $115 billion bet on optics. The market hated it.
Shares closed at $141 on Friday, down about 44% from their $252 close on October 28, the last trading day before reports of talks with Lumentum (LITE) surfaced. The all-stock deal, announced November 2, values Lumentum at an enterprise value of $115 billion, almost as much as Marvell’s own $124 billion market cap.
Then a broad chip selloff piled on. Semiconductor stocks plunged on November 5 as a Democratic sweep and a wave of earnings pushed investors to unwind the AI trade.
Friday’s 5.7% bounce barely dented the damage.
A $1,132 offer worth far less now
The exchange ratio is fixed, so Lumentum’s price falls with Marvell’s. At $141, 4.5 Marvell shares are worth about $635 per Lumentum share, against the $1,132 implied at signing, which was a 23.9% premium at the time.
- Marvell holders will own about 67% of the combined company, and Lumentum holders about 33%.
- Management targets more than $1 billion in annual run-rate cost synergies and expects the deal to add to non-GAAP EPS in its first year.
- Closing should take roughly 12 to 18 months, pending shareholder and regulatory approvals, and China’s review is a key hurdle.
Investors priced in the dilution fast…
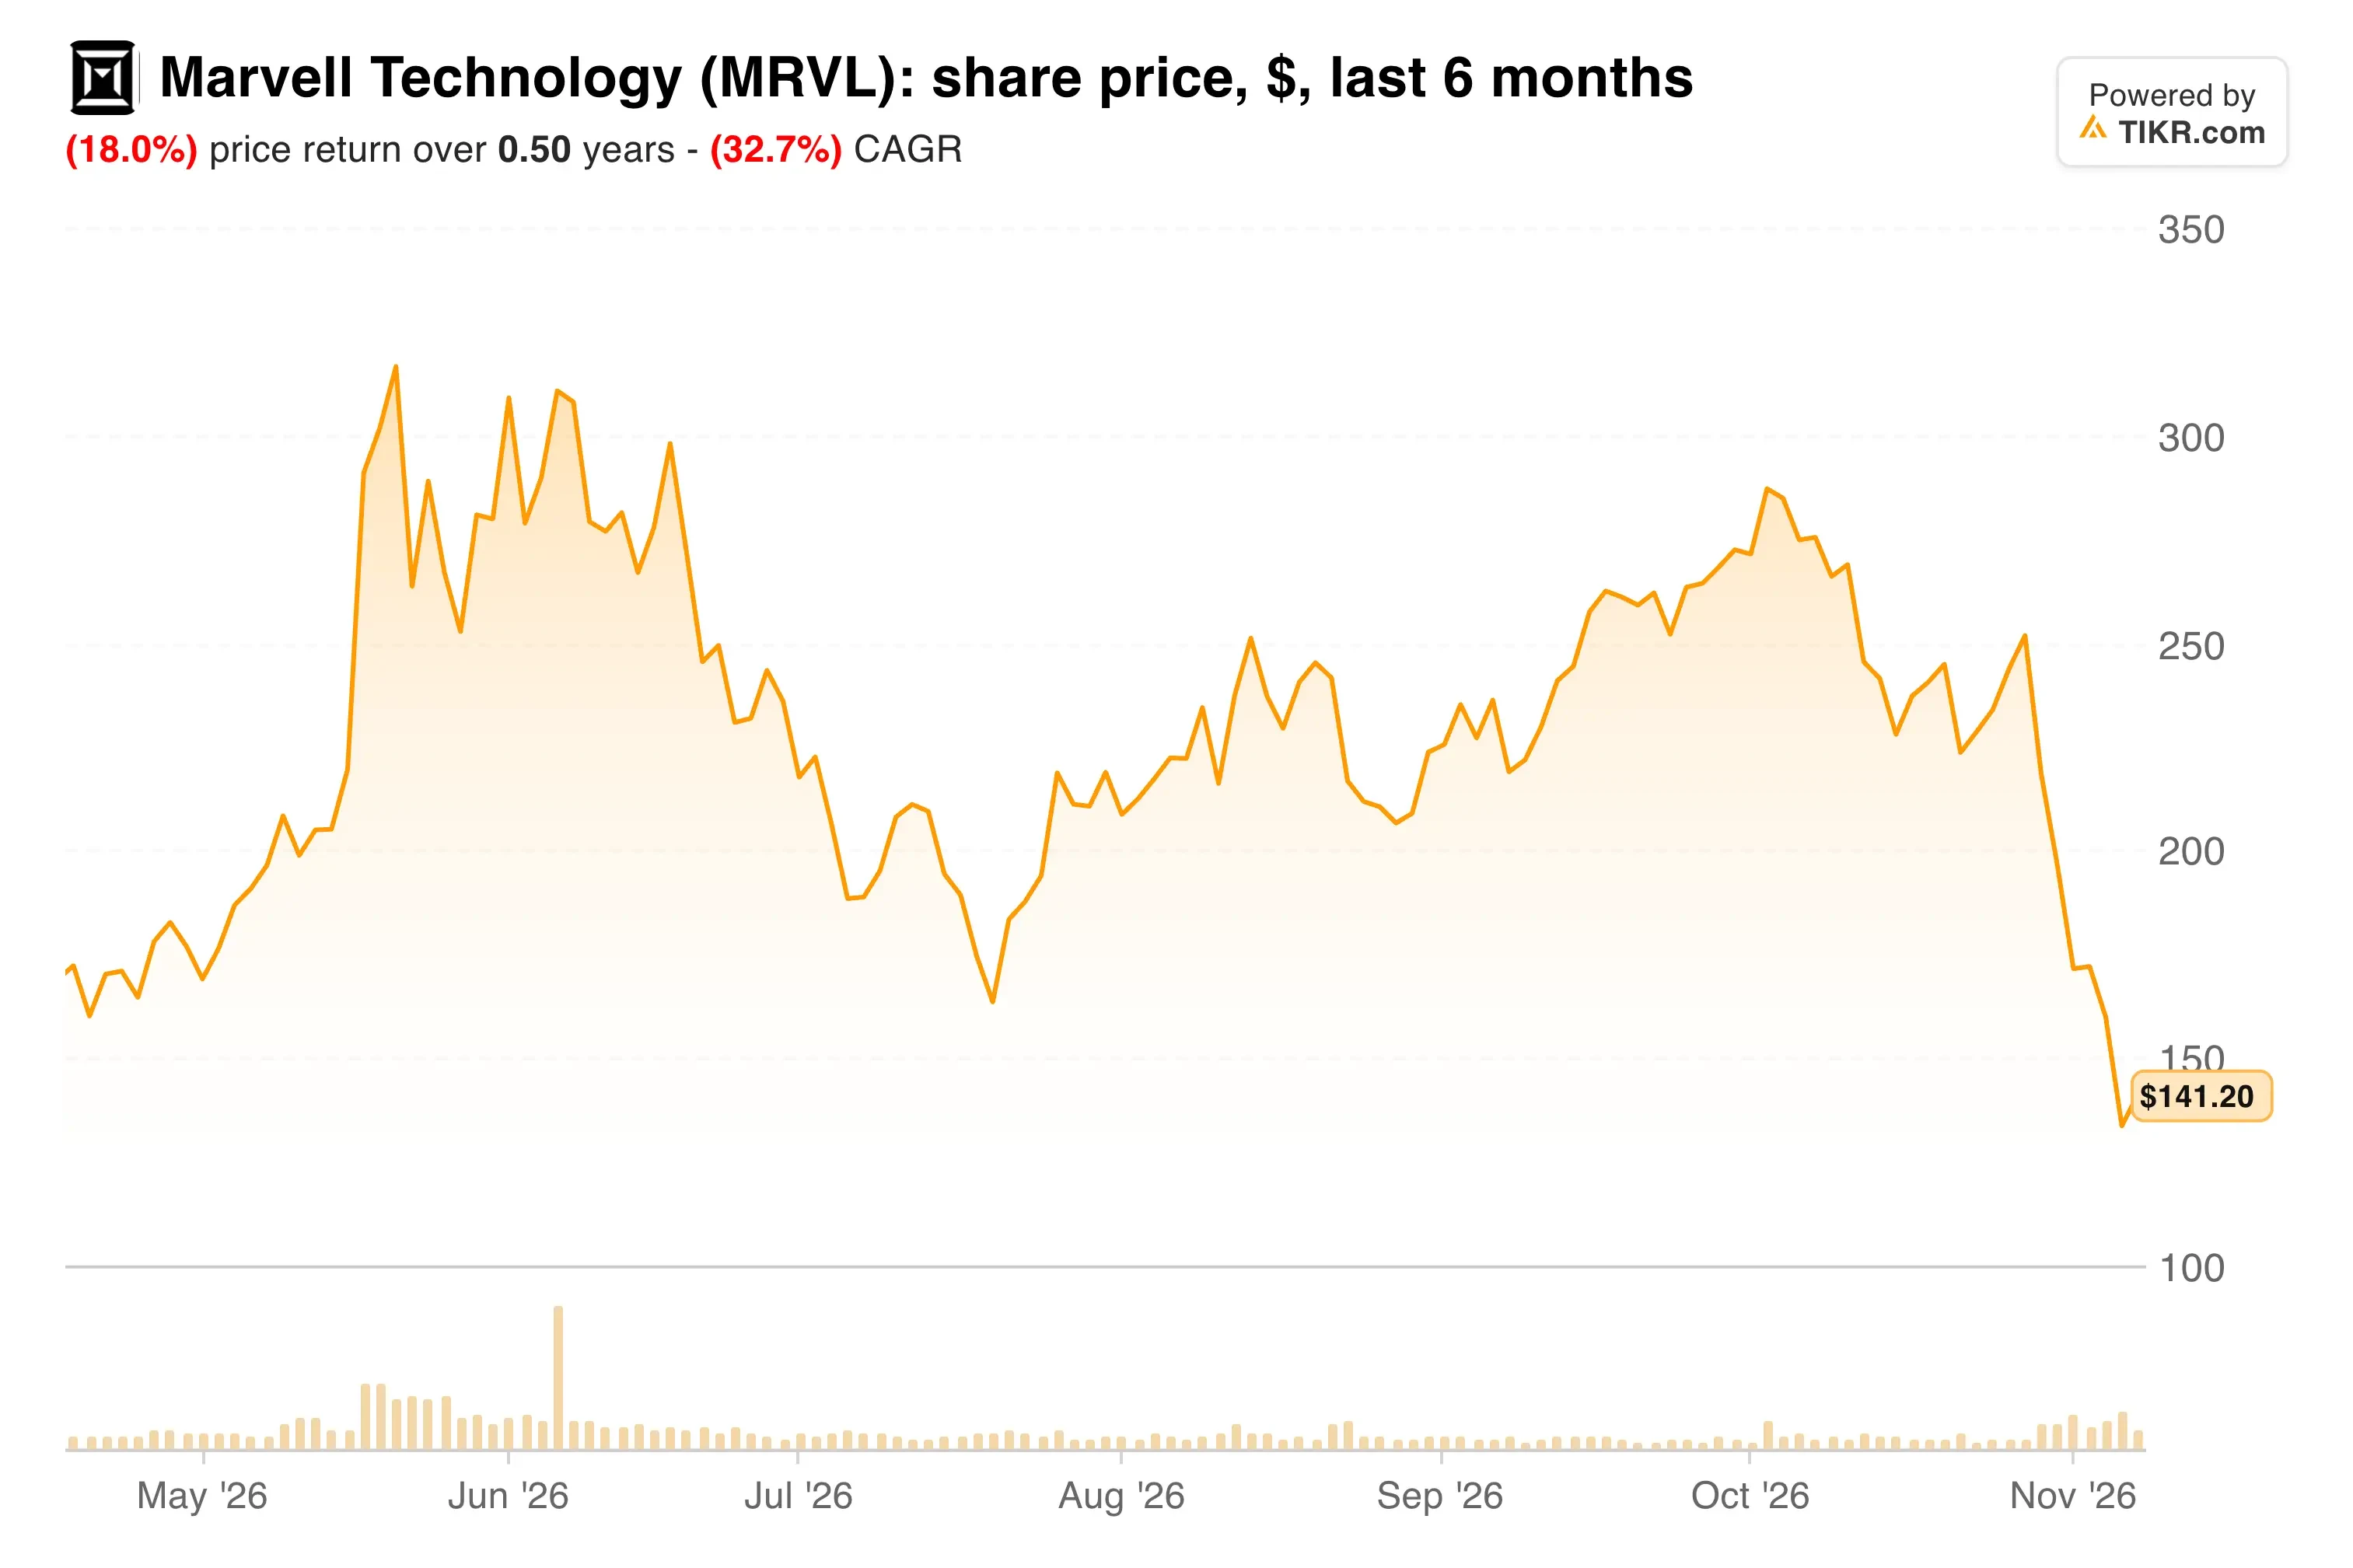
The stock now sits 57% below its $330 52-week high.
The core business keeps accelerating
Lost in the selloff: Marvell’s own numbers keep improving. Fiscal second-quarter revenue rose 37% to a record $2.739 billion, and data center revenue climbed 46% to $2.17 billion, or 79% of sales.
“AI-related bookings remain exceptionally robust,” Murphy said in August.
Guidance calls for $3.15 billion of third-quarter revenue and $1.10 of non-GAAP EPS, with data center sales up roughly 75% year over year. On November 2, Marvell said preliminary third-quarter revenue was in line with that guide.
Management also lifted its fiscal 2027 revenue outlook to about $12 billion and fiscal 2028 to about $18 billion. So where does consensus land?
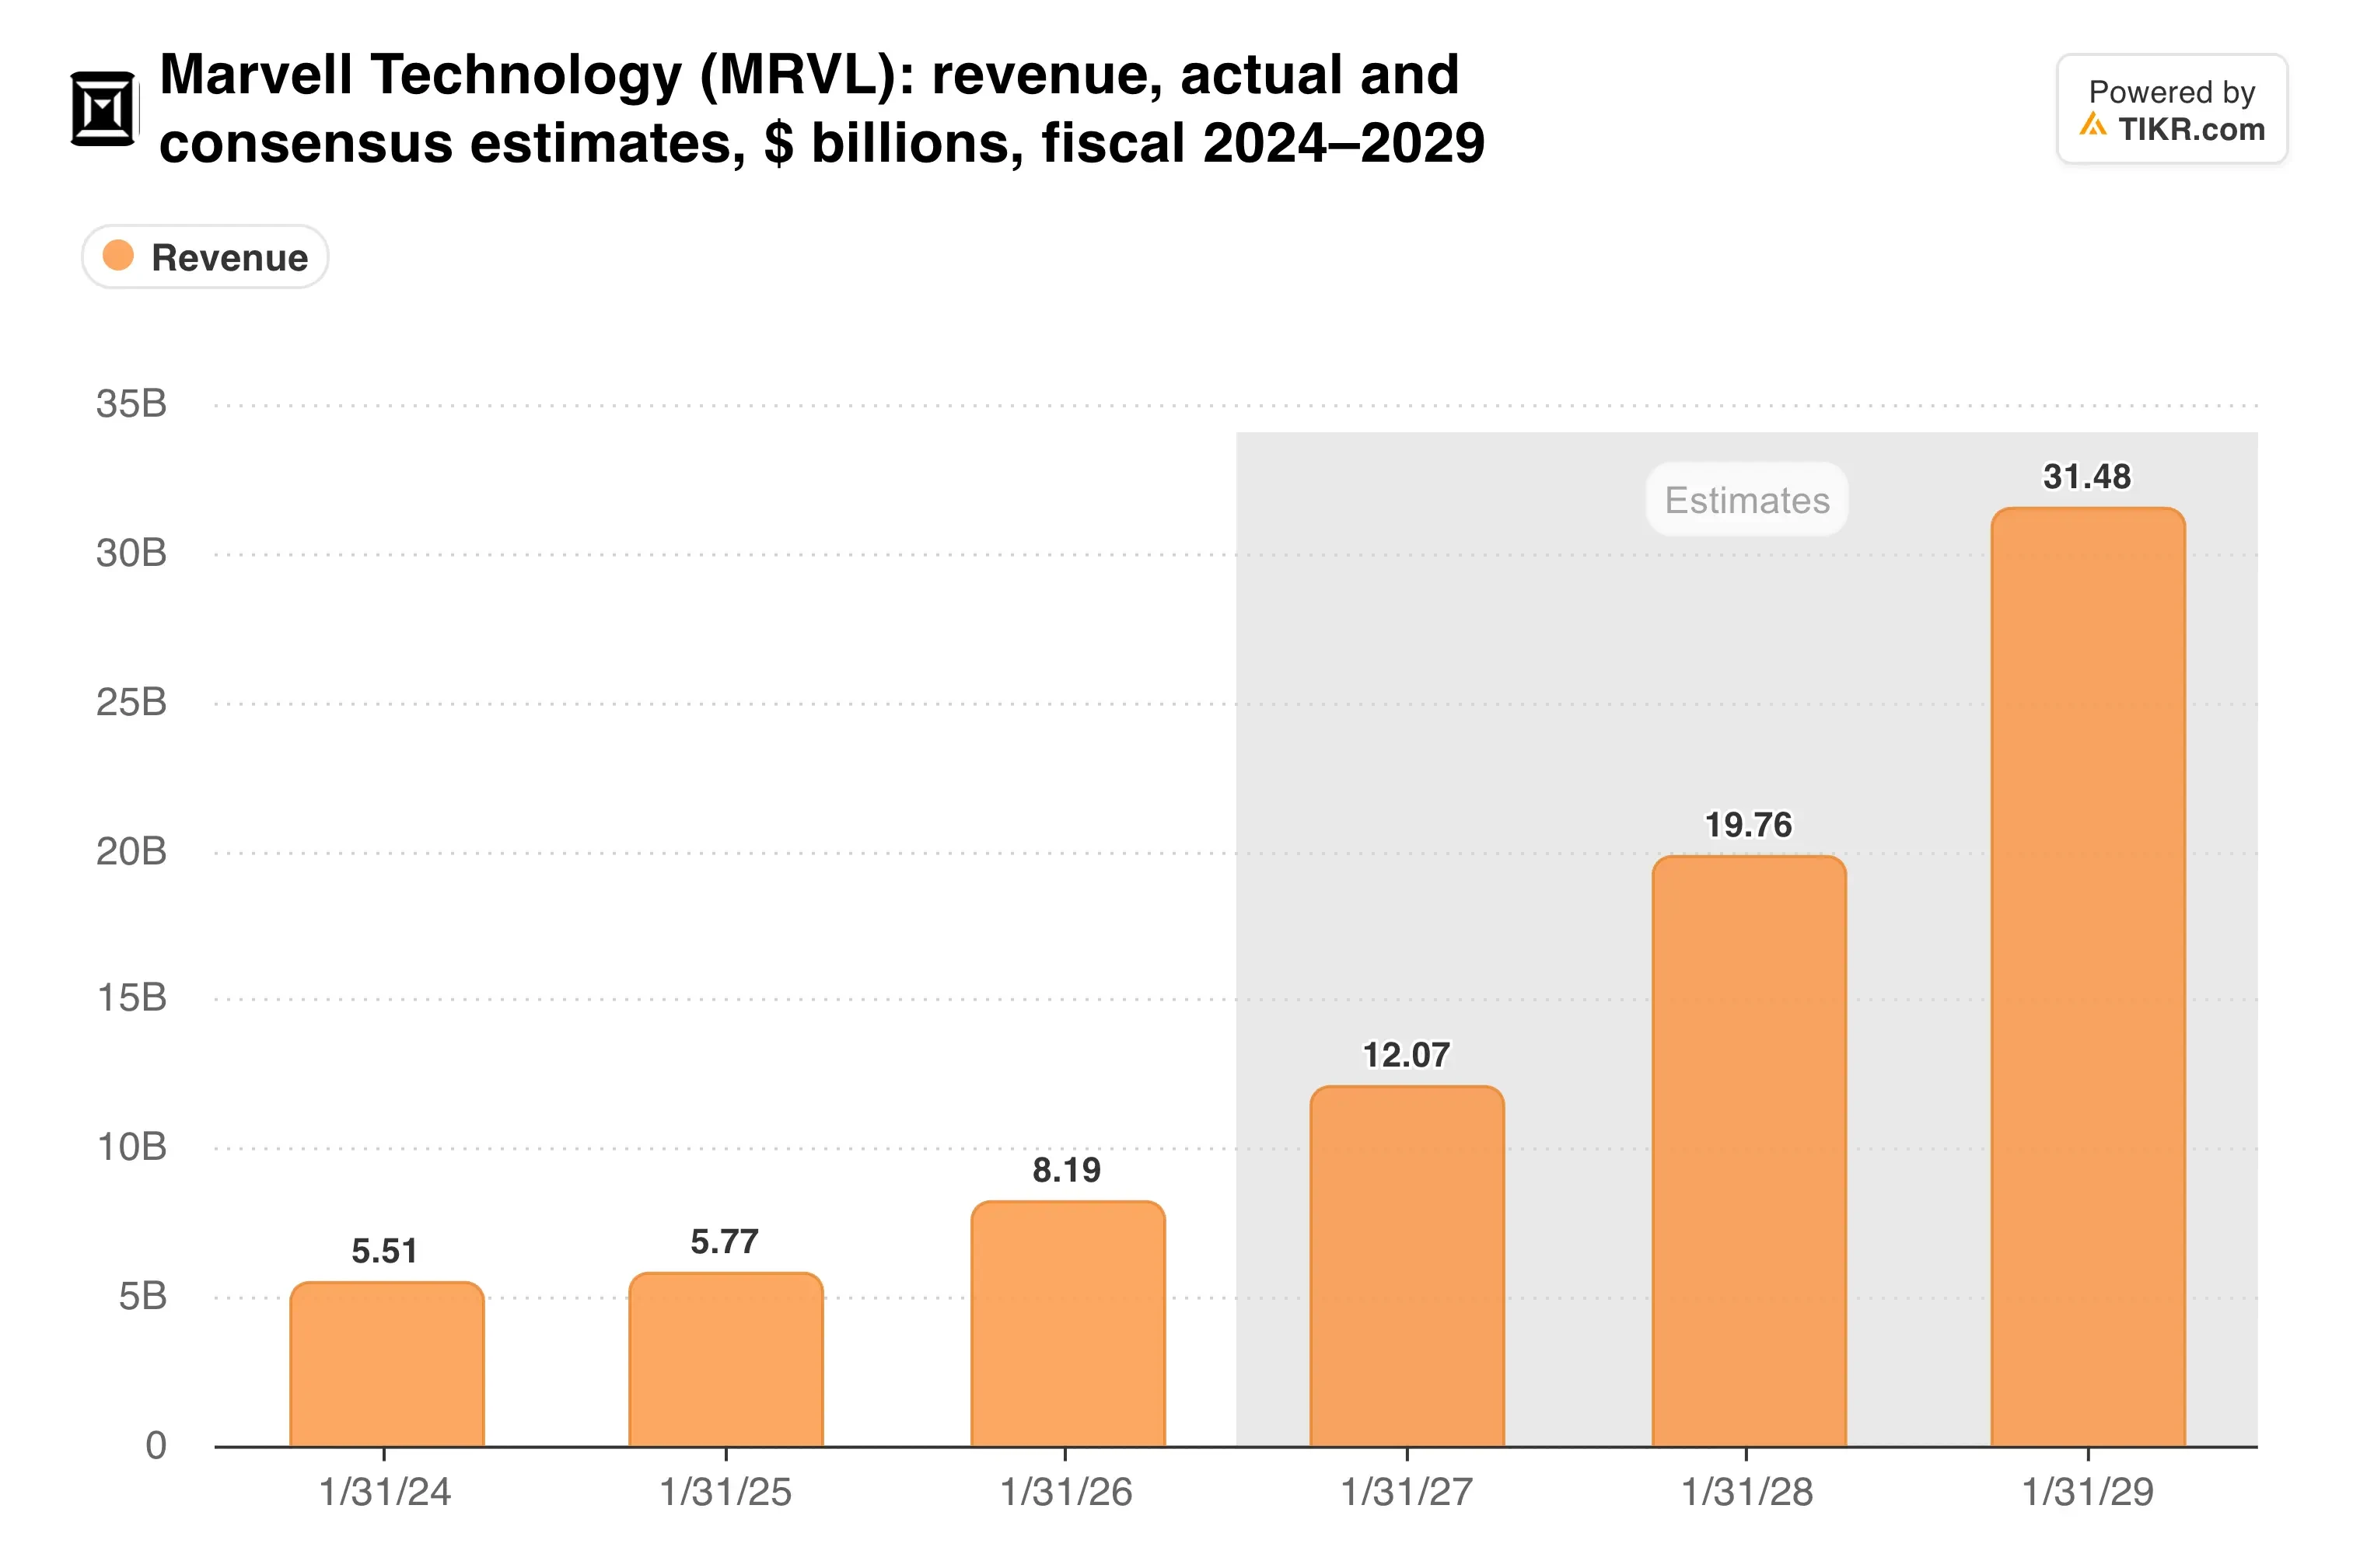
Those estimates cover Marvell alone. If the deal closes, Lumentum’s optics revenue would sit on top.
TIKR tracks 46 analysts on Marvell. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Marvell, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Marvell’s Analyst Ratings
Paying up for optics
The strategic logic is easy to follow. Murphy argues that optical connectivity is replacing copper inside AI clusters, and he says “The companies that move first and help define this transition will set the standard for decades to come.”
The price is harder to swallow. Lumentum holders get a third of a company whose stock just lost 44%, and the combined business has to deliver synergies through a long regulatory process.
Valuation has reset hard. Marvell trades at 25.0x forward earnings and 19.8x forward EV/EBITDA, while Wall Street’s average target of $310 implies about 120% upside, a gap that suggests many targets haven’t caught up yet.
Margins show what Marvell is buying.
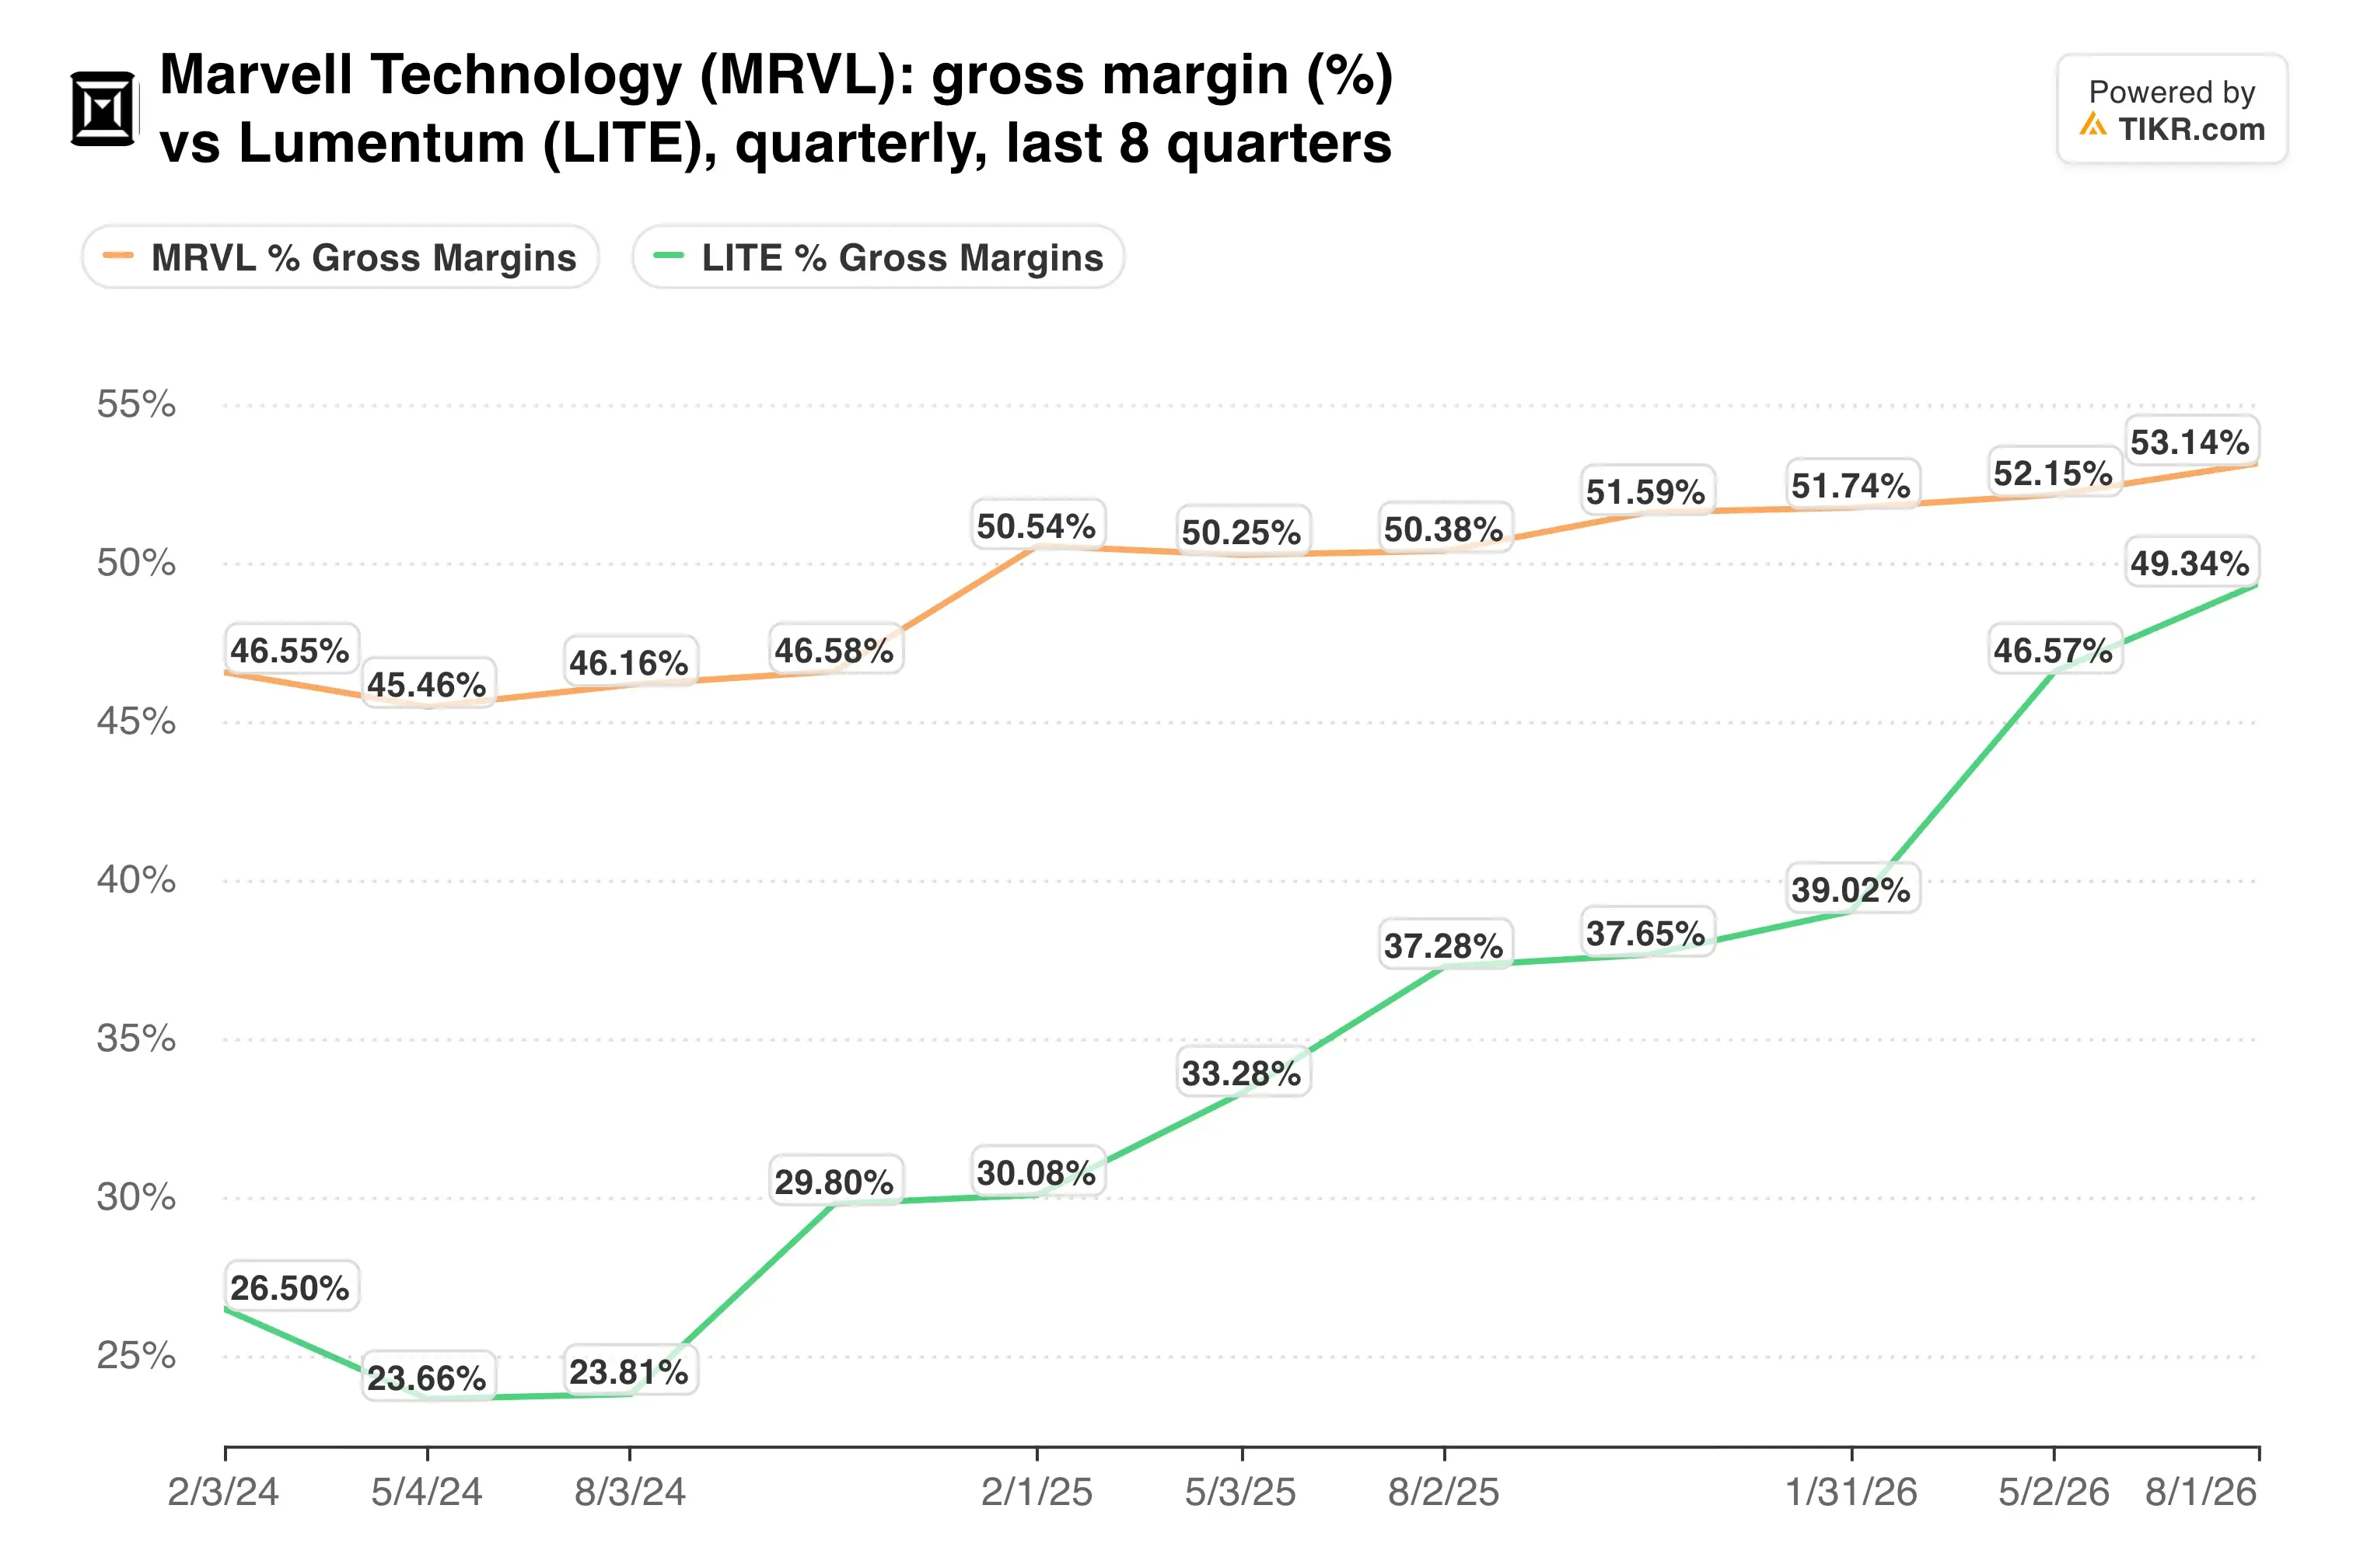
Management says the deal will lift the combined company’s non-GAAP gross margin over time. That’s the claim to track once Lumentum’s numbers fold in.
My take: The core business is growing faster than ever, and 25x forward earnings already prices in plenty of skepticism. But a fixed-ratio deal this large with a long China review will likely cap the shares until regulators move. I’d build a position slowly.
The December 1 report is the next hard read. It will show whether third-quarter revenue lands at $3.15 billion and whether fourth-quarter guidance keeps the data center acceleration intact.
So what is Marvell stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Marvell could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!