Key Takeaways
- Starbucks posted fiscal fourth-quarter adjusted EPS of $0.80, beating the $0.72 consensus, as global comparable sales rose 7.2%.
- CEO Brian Niccol said “Back to Starbucks is our growth plan,” but North America comps are guided to slow to about 4% in fiscal 2027.
- At about 33x forward earnings, the stock sits within 5% of the $111 Street target after a 28% gain in 2026.
- Chipotle’s October downgrade on sales worries shows how restaurant stocks get punished when growth cools, and Starbucks reports again January 27.
Starbucks (SBUX) just had the kind of quarter turnarounds are built on. The stock barely moved.
Shares closed at $105 on Friday, up 28% in 2026 on a total return basis and about $6 below their 52-week high. That run already did most of the celebrating.
The quarter itself was clean. Adjusted EPS of $0.80 beat the $0.72 consensus, global comps rose 7.2%, and operating margin expanded for a third straight quarter.
The tension is what comes next. Management guided North America comps to about 4% for fiscal 2027, roughly half the pace it just delivered.
That matters for a stock priced like a growth company. Chipotle Mexican Grill (CMG) slid in October after TD Cowen downgraded it on sales worries and cut its price target to a Street low, a reminder of how fast the market reprices restaurant chains when sales cool.
The turnaround shows up in traffic
Revenue fell 4% to $9.1 billion. That decline reflects the conversion of China retail operations into a licensed joint venture with Boyu Capital, so the underlying business still grew.
- North America comps rose 7.9%, with transactions up 2.7%.
- U.S. comps rose 7.7%.
- More than 80% of North America company-operated coffeehouses posted positive comps, up from less than 50% a year ago.
Niccol put it plainly on the earnings call: “Back to Starbucks started as a turnaround plan and now Back to Starbucks is our growth plan.”
Earnings have followed the traffic…
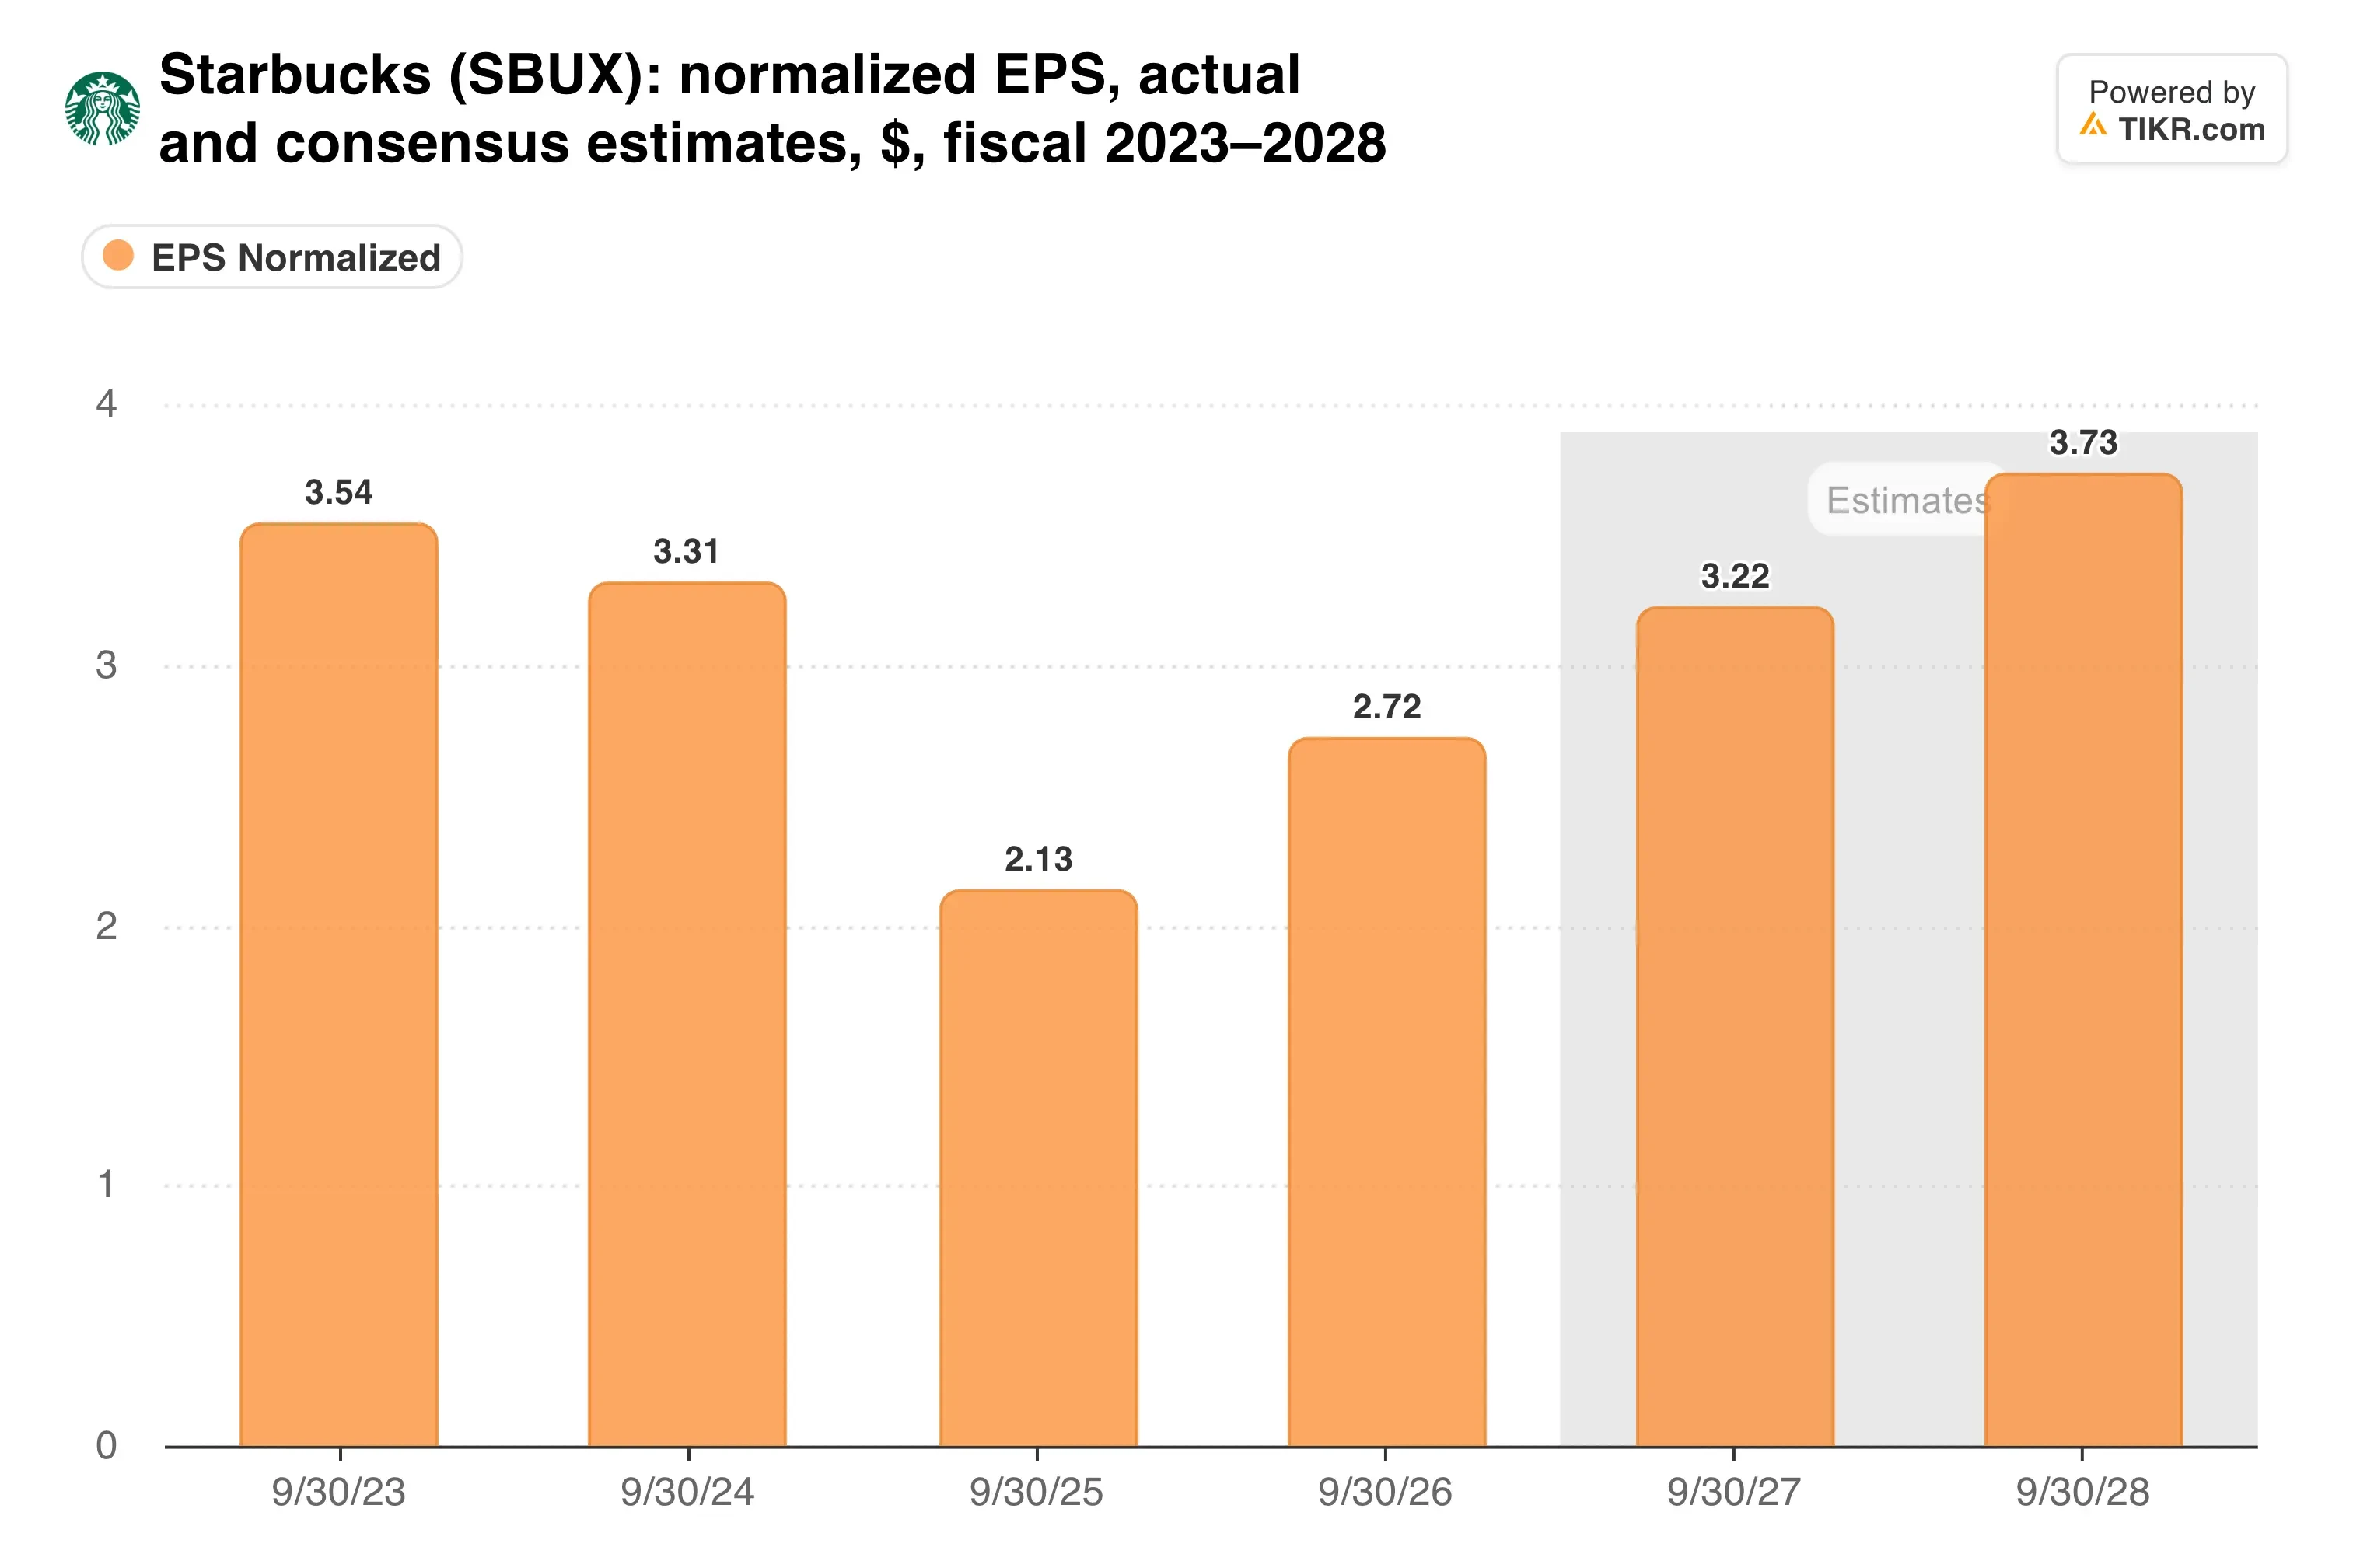
Fiscal 2026 EPS grew about 27% to $2.72. The new guide of $3.15 to $3.25 implies roughly 18% growth at the midpoint.
International is the soft spot
North America is carrying the story. International comps rose just 0.9% as transactions fell 2.8%, and a higher average ticket covered the gap.
Yet the segment’s operating margin jumped to 19.7% from 10.8%, mostly because China moved to a licensed model. Licensing gives up reported revenue in exchange for steadier margins, and management credits that model for much of its unit growth abroad.
How much more margin can the whole company squeeze out?
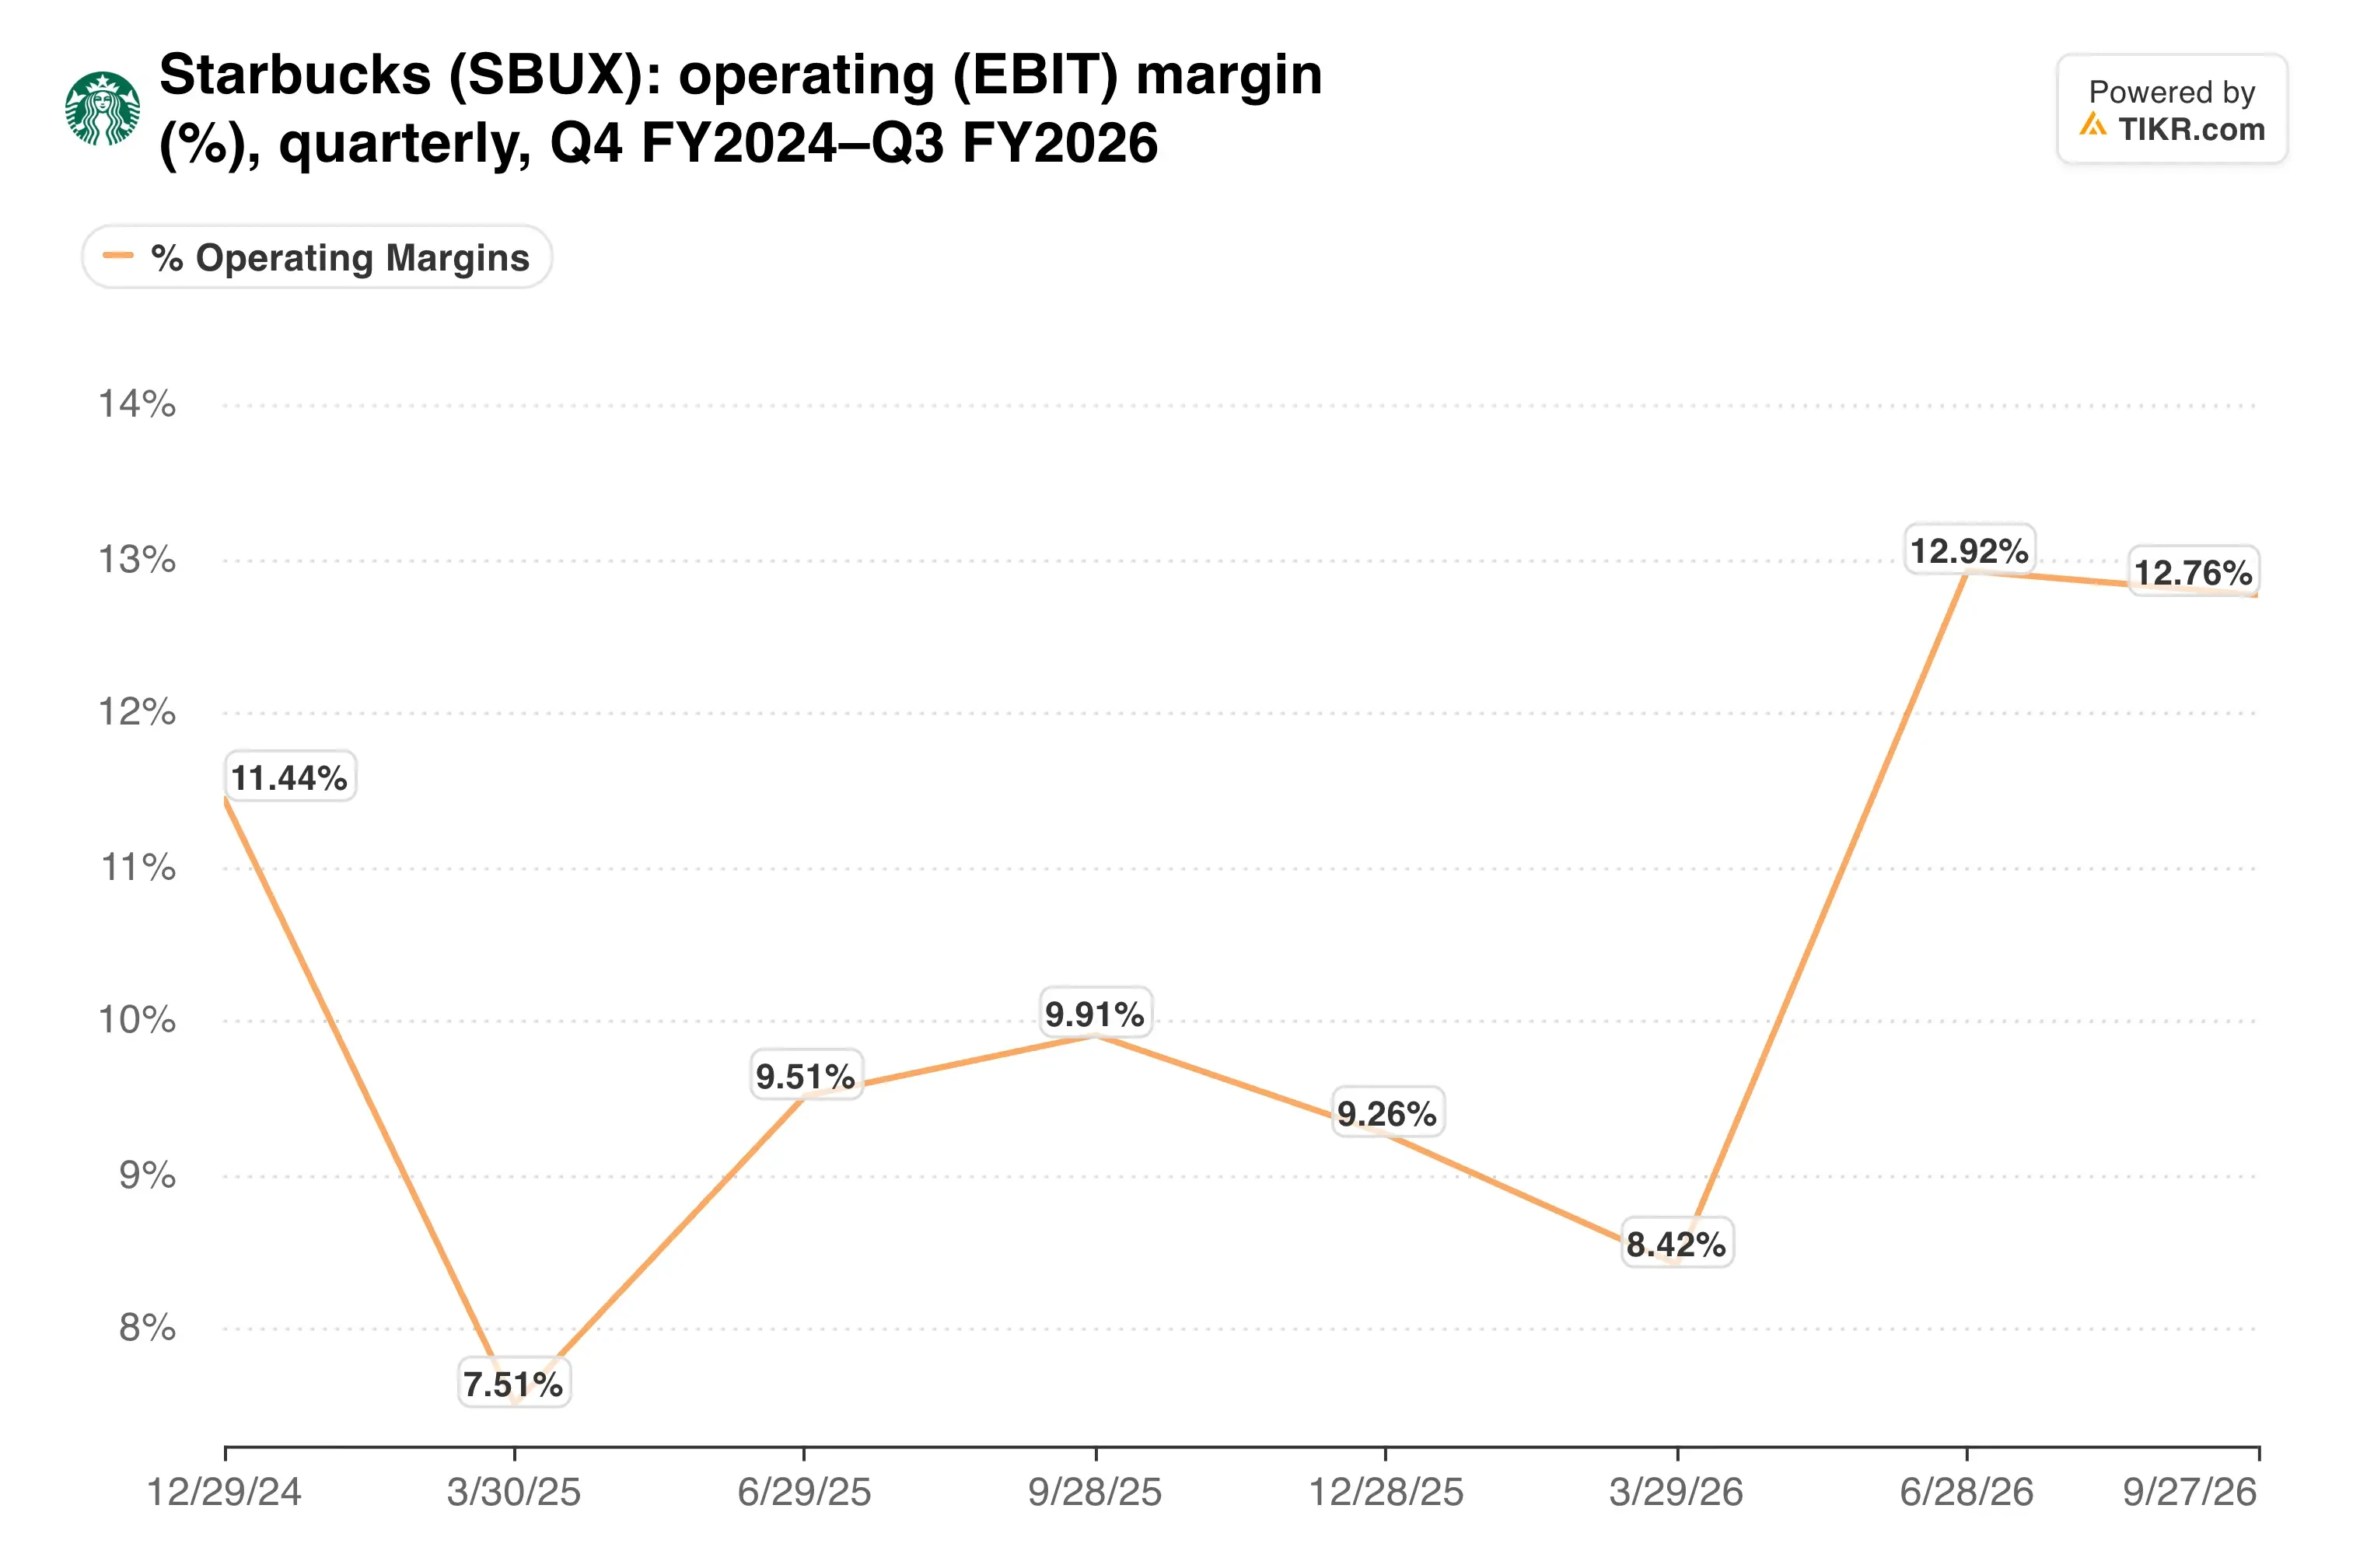
Fiscal 2027 guidance calls for a 13.5% to 14% operating margin, and the fourth quarter already hit 14%. So next year’s earnings growth depends mostly on sales and returning buybacks.
TIKR tracks 35 analysts on Starbucks. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Starbucks, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Starbucks’ Analyst Ratings
A premium that needs 4% to hold
Starbucks trades at 32.8x forward earnings and 20.9x forward EV/EBITDA. Wall Street’s average target of $111 sits only about 5% above the share price.
The balance sheet adds some pressure. The quarterly dividend rose to $0.63, the payout ratio is above 100% of trailing earnings, and net debt sits at 2.1x EBITDA just as repurchases restart in fiscal 2027.
Set that multiple next to Chipotle’s over three years, and the gap tells you what investors expect.
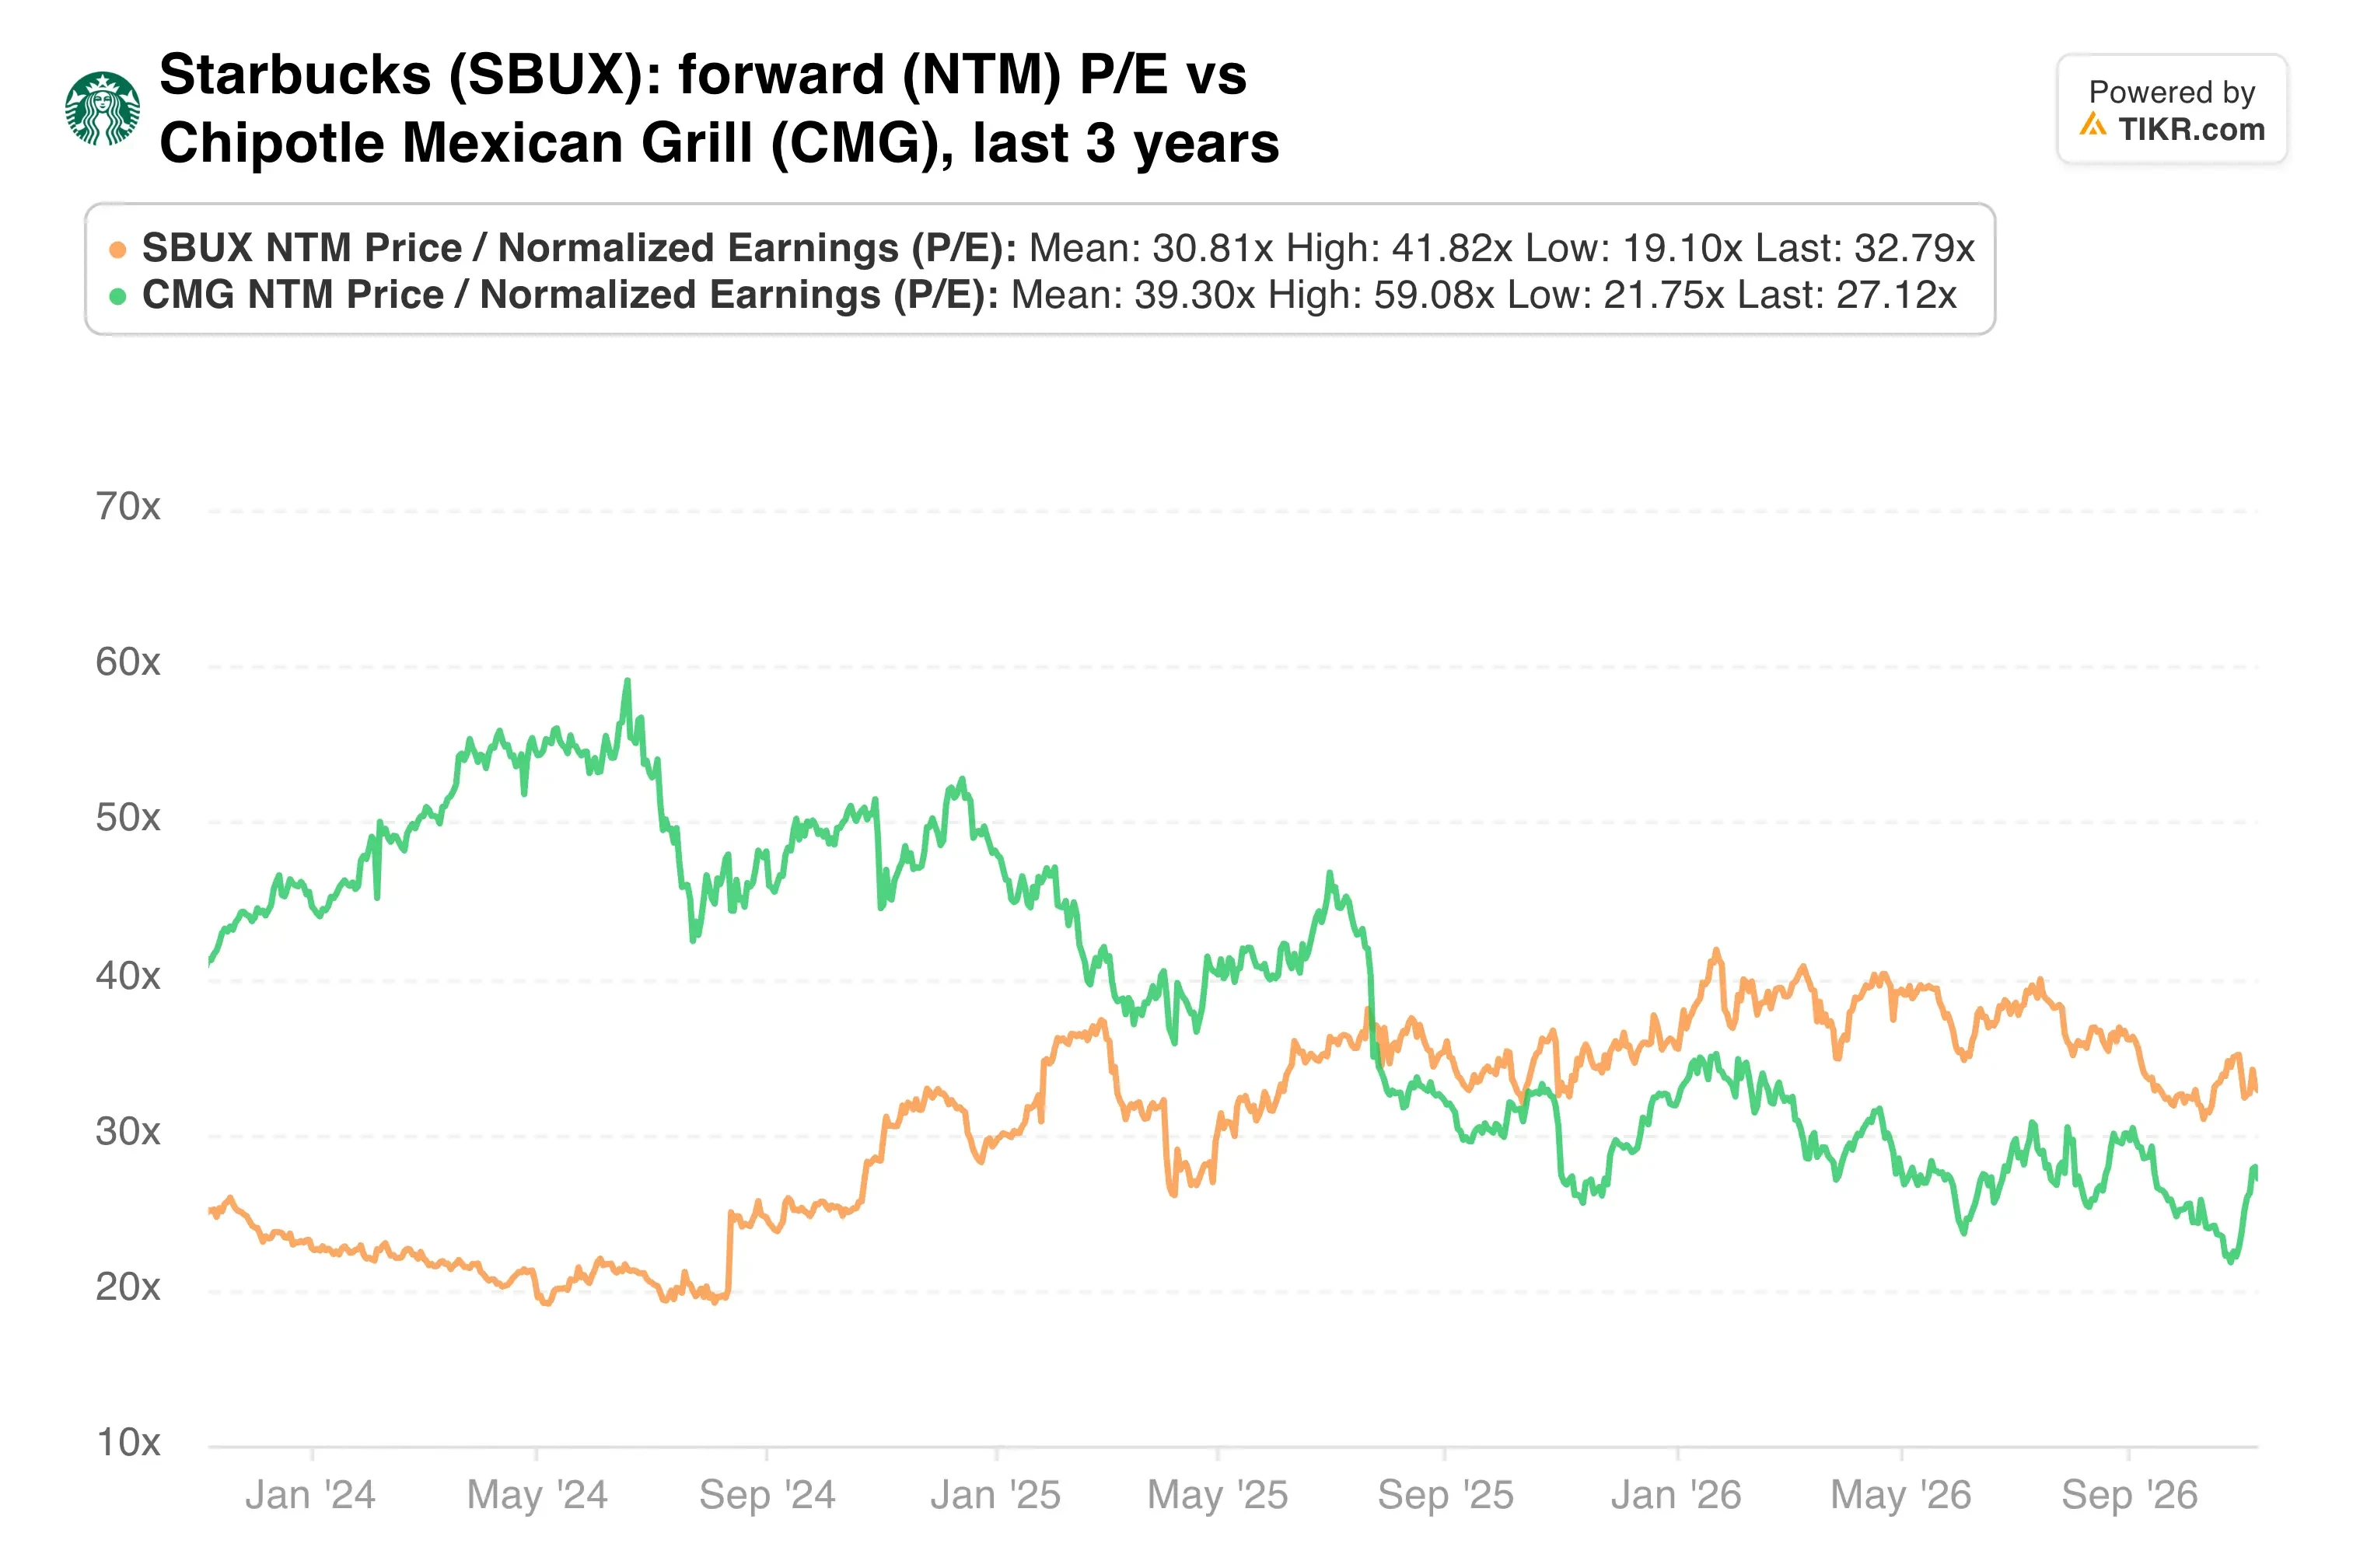
The multiple has come down from about 40x in April as earnings caught up with the price. Even so, it still assumes the comp momentum lasts.
My take: Starbucks fixed its stores faster than I expected, and 7.9% North America comps show customers came back. But 33x earnings on 4% comp guidance leaves little room for a stumble. I’d wait for a better entry.
The January 27 report covers the first quarter of fiscal 2027. It will show whether comps can hold near that 4% guide as the comparisons get harder.
So what is Starbucks stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Starbucks could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!