Key Takeaways
- Marvell Technology (MRVL) shares declined approximately 36% between October 28 and November 4, closing near $160 as investors questioned its proposed acquisition of Lumentum.
- Lumentum (LITE) fell approximately 31% over the same period, closing near $627 as Marvell’s declining share price reduced the value of its all-stock takeover offer.
- The $115 billion transaction would give Lumentum shareholders approximately 33% of the combined company, increasing Marvell’s existing share count by roughly 49%.
- Marvell traded near 30x forward earnings on November 2, below its five-year average of approximately 33x, suggesting potential value despite substantial acquisition risks.
What Happened?
Marvell Technology (MRVL) shares plunged approximately 36% from October 28 through November 4, closing near $160, while Lumentum (LITE) declined approximately 31% to $627 as investors reacted to their proposed acquisition agreement.
The selloff began after reports of acquisition discussions following the October 28 close. On November 2, Marvell and Lumentum announced an all-stock transaction, assigning Lumentum an implied enterprise value of approximately $115 billion.
Under the agreement, Lumentum shareholders would receive 4.5 Marvell shares for each share owned, initially worth approximately $1,132 per share and representing a 23.9% premium to Lumentum’s October 28 closing price.
Marvell CEO Matt Murphy described the opportunity in AI optical connectivity as “an opportunity that comes along once in a generation.”
The proposed acquisition would combine Marvell’s custom silicon and networking technologies with Lumentum’s optical components, strengthening the combined company’s position in AI data-center infrastructure.
However, the transaction introduces substantial dilution. Lumentum shareholders would own approximately 33% of the combined business, increasing Marvell’s existing share count by roughly 49%.
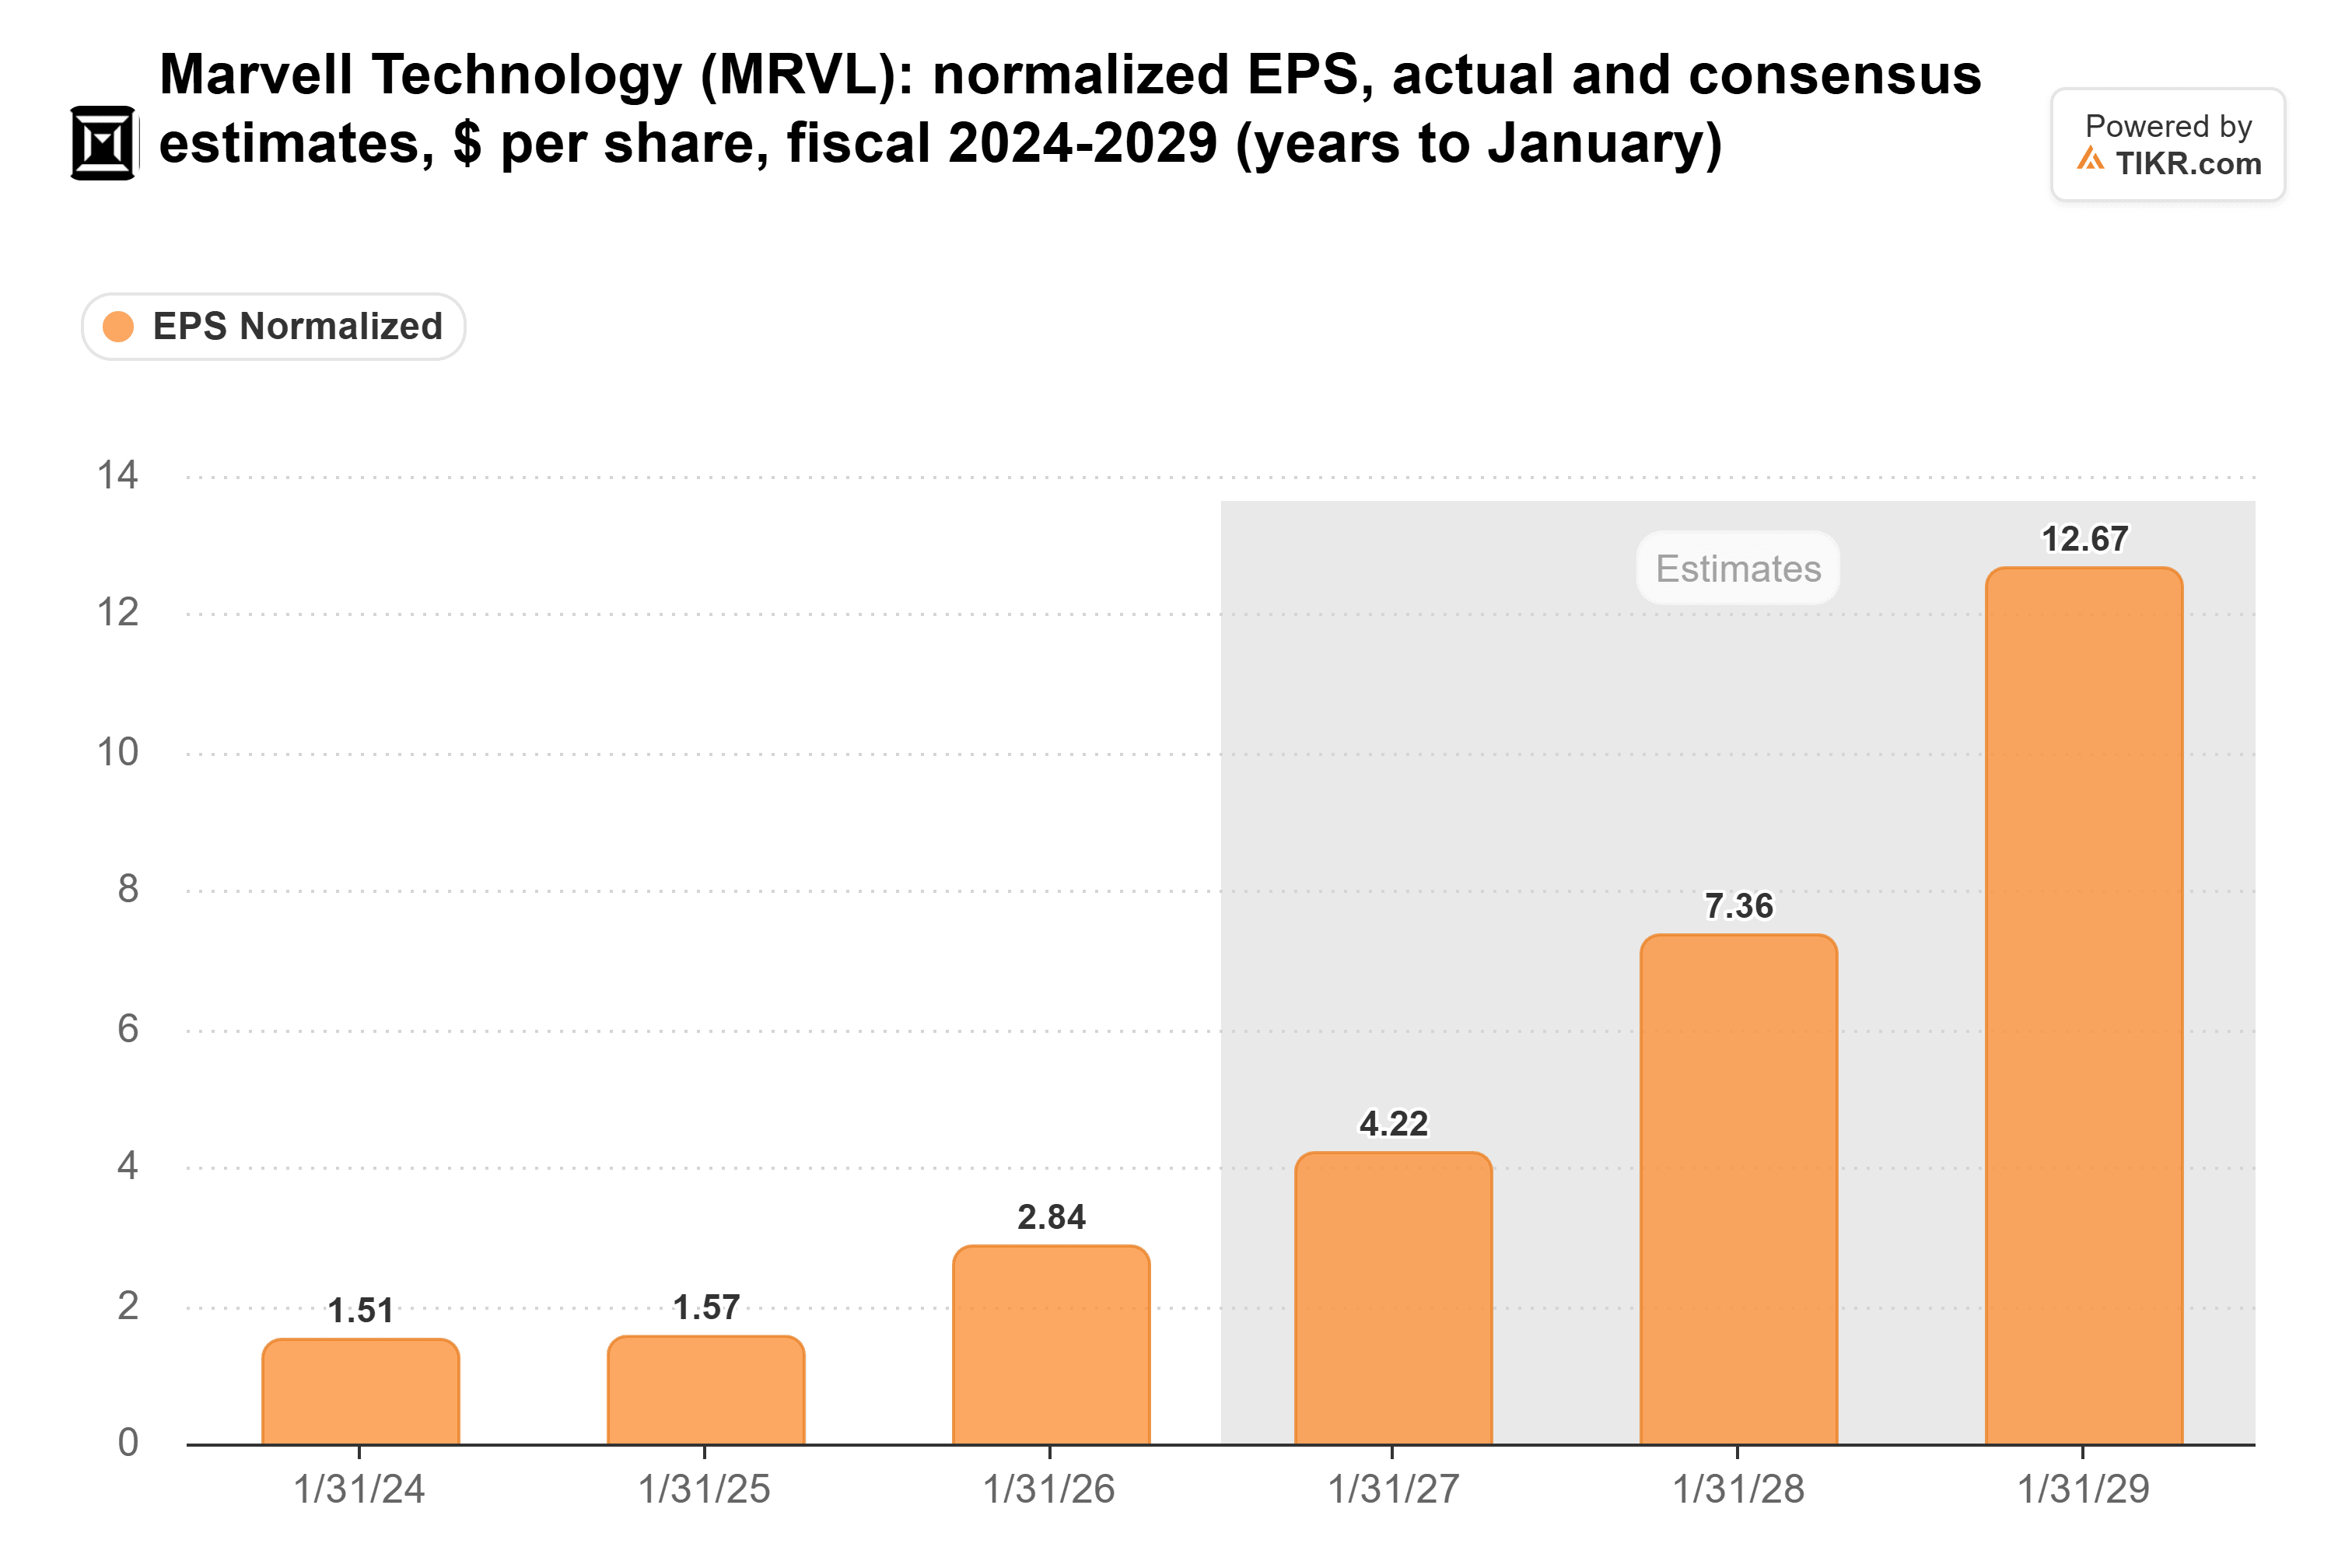
TIKR estimates showed Marvell’s normalized EPS reaching $7.36 for the year ending January 2028 and $12.67 for the following year, highlighting expectations for substantial earnings growth.
However, those estimates may not fully reflect the acquisition’s additional shares, integration expenses, or anticipated financial benefits.
Meanwhile, Lumentum reported fiscal first-quarter revenue of $1.26 billion, up 136.5% year over year, supported by expanding demand for optical networking products.
The fixed exchange ratio explains why Lumentum also declined. At Marvell’s November 4 closing price of approximately $160, the offer was worth about $719 per Lumentum share, below its roughly $914 pre-announcement price.
Lumentum closed near $627 that day, approximately 13% below the implied consideration. This discount highlights the uncertainty investors were assigning to the transaction’s completion and future value.
Is Marvell Stock Undervalued After the Selloff?
Marvell appears potentially undervalued relative to its historical earnings multiple, although the acquisition creates meaningful uncertainty.
At the November 2 close, Marvell traded near 30x forward earnings, below its five-year average of approximately 33x and significantly beneath its June peak near 70x.
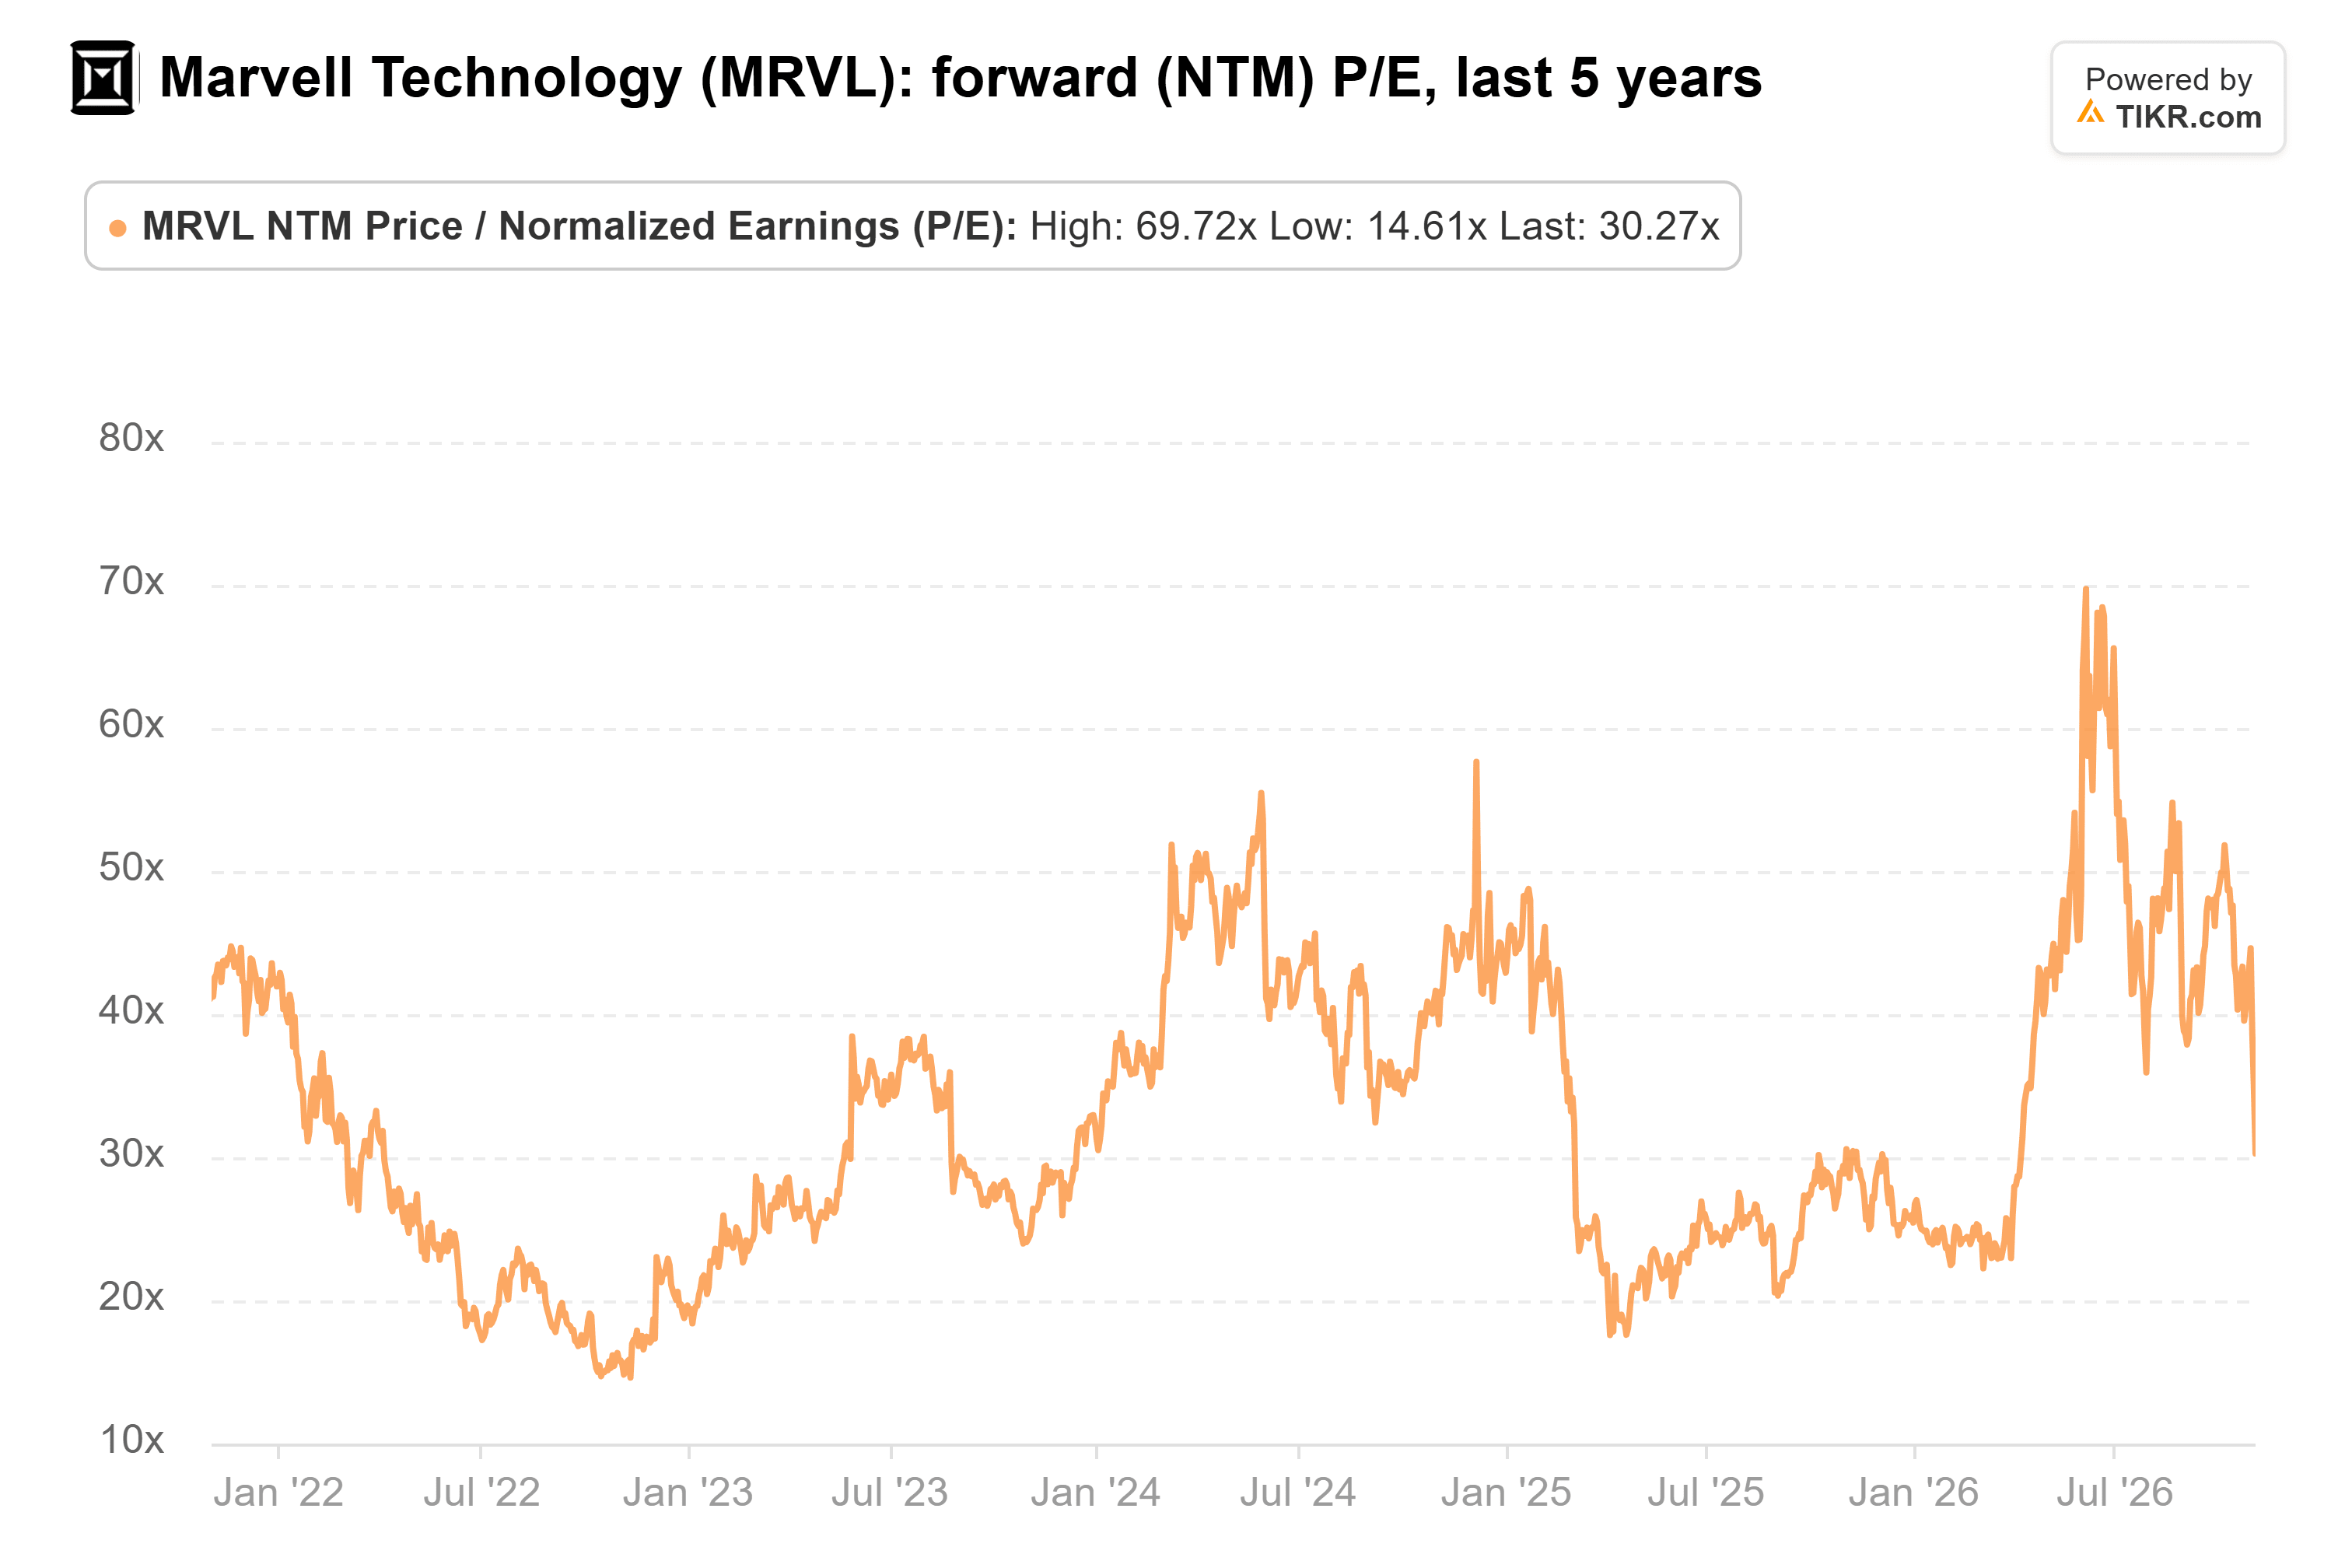
Using the November 4 closing price and the earlier forward earnings estimate, Marvell’s multiple had declined to approximately 28x. However, a lower valuation does not automatically make the stock attractive if future earnings growth weakens.
Over the next 12 months, its outlook will depend on sustained AI infrastructure spending, demand for high-speed networking technologies, and confidence that the acquisition can generate enough earnings to offset dilution.
According to the companies’ acquisition announcement, management anticipates more than $1 billion in annual run-rate cost synergies and expects the transaction to increase non-GAAP earnings per share in its first year after closing.
However, the acquisition is not expected to close until the first half of 2028, exposing investors to regulatory uncertainty, integration challenges, and potentially weaker AI infrastructure spending.
Marvell looks potentially undervalued following the selloff, but the acquisition makes the investment case more complicated. Its lower earnings multiple and expected AI-driven growth provide possible upside, while substantial dilution and execution risks could limit returns. The next quarterly earnings report should help clarify whether underlying demand is strong enough to support its valuation.
What Could Marvell Stock Be Worth After the Acquisition?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Marvell could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!