Key Takeaways
- Seagate shares jumped 10% today as AI hardware stocks, including Coherent, bounced back from last week’s selloff.
- Morgan Stanley kept Seagate as a top pick with a $1,148 price target, citing its strong fundamentals and weak sentiment.
- Analysts expect Seagate’s normalized EPS to more than quadruple from fiscal 2026 to fiscal 2028, which makes the stock look too cheap at a fraction of its usual forward multiple.
- The main risk is calendar-2028 pricing, which Seagate still has to set with customers.
Seagate Technology (STX) jumped 10% today as investors bought back into AI hardware after last week’s selloff. Morgan Stanley spent Friday arguing it never deserved to fall this far.
Coherent (COHR) rose 18% with no news of its own. The rebound reached the data center’s power gear too, with Vertiv (VRT) up 9%. Lumentum (LITE) and Astera Labs (ALAB) both gained 13%, and neither had news of its own. Astera was bouncing off a 26% drop over the past week, and Lumentum moved with Marvell, which is buying it in an all-stock deal.
Woodring sees a “disconnect”
Morgan Stanley’s Erik Woodring said Friday that the firm’s meetings with management show a disconnect between Seagate’s “strong fundamentals and weak sentiment.” He said revenue and pricing are accelerating, the supply/demand gap is widening, and buybacks could reach 30% of Seagate’s market cap in 2.5 years. He kept a $1,148 target, more than double where the stock trades, and took the case to CNBC’s Closing Bell after Friday’s close.
Analysts expect normalized EPS to climb from a record $15.58 in fiscal 2026 to $65.34 in fiscal 2028:
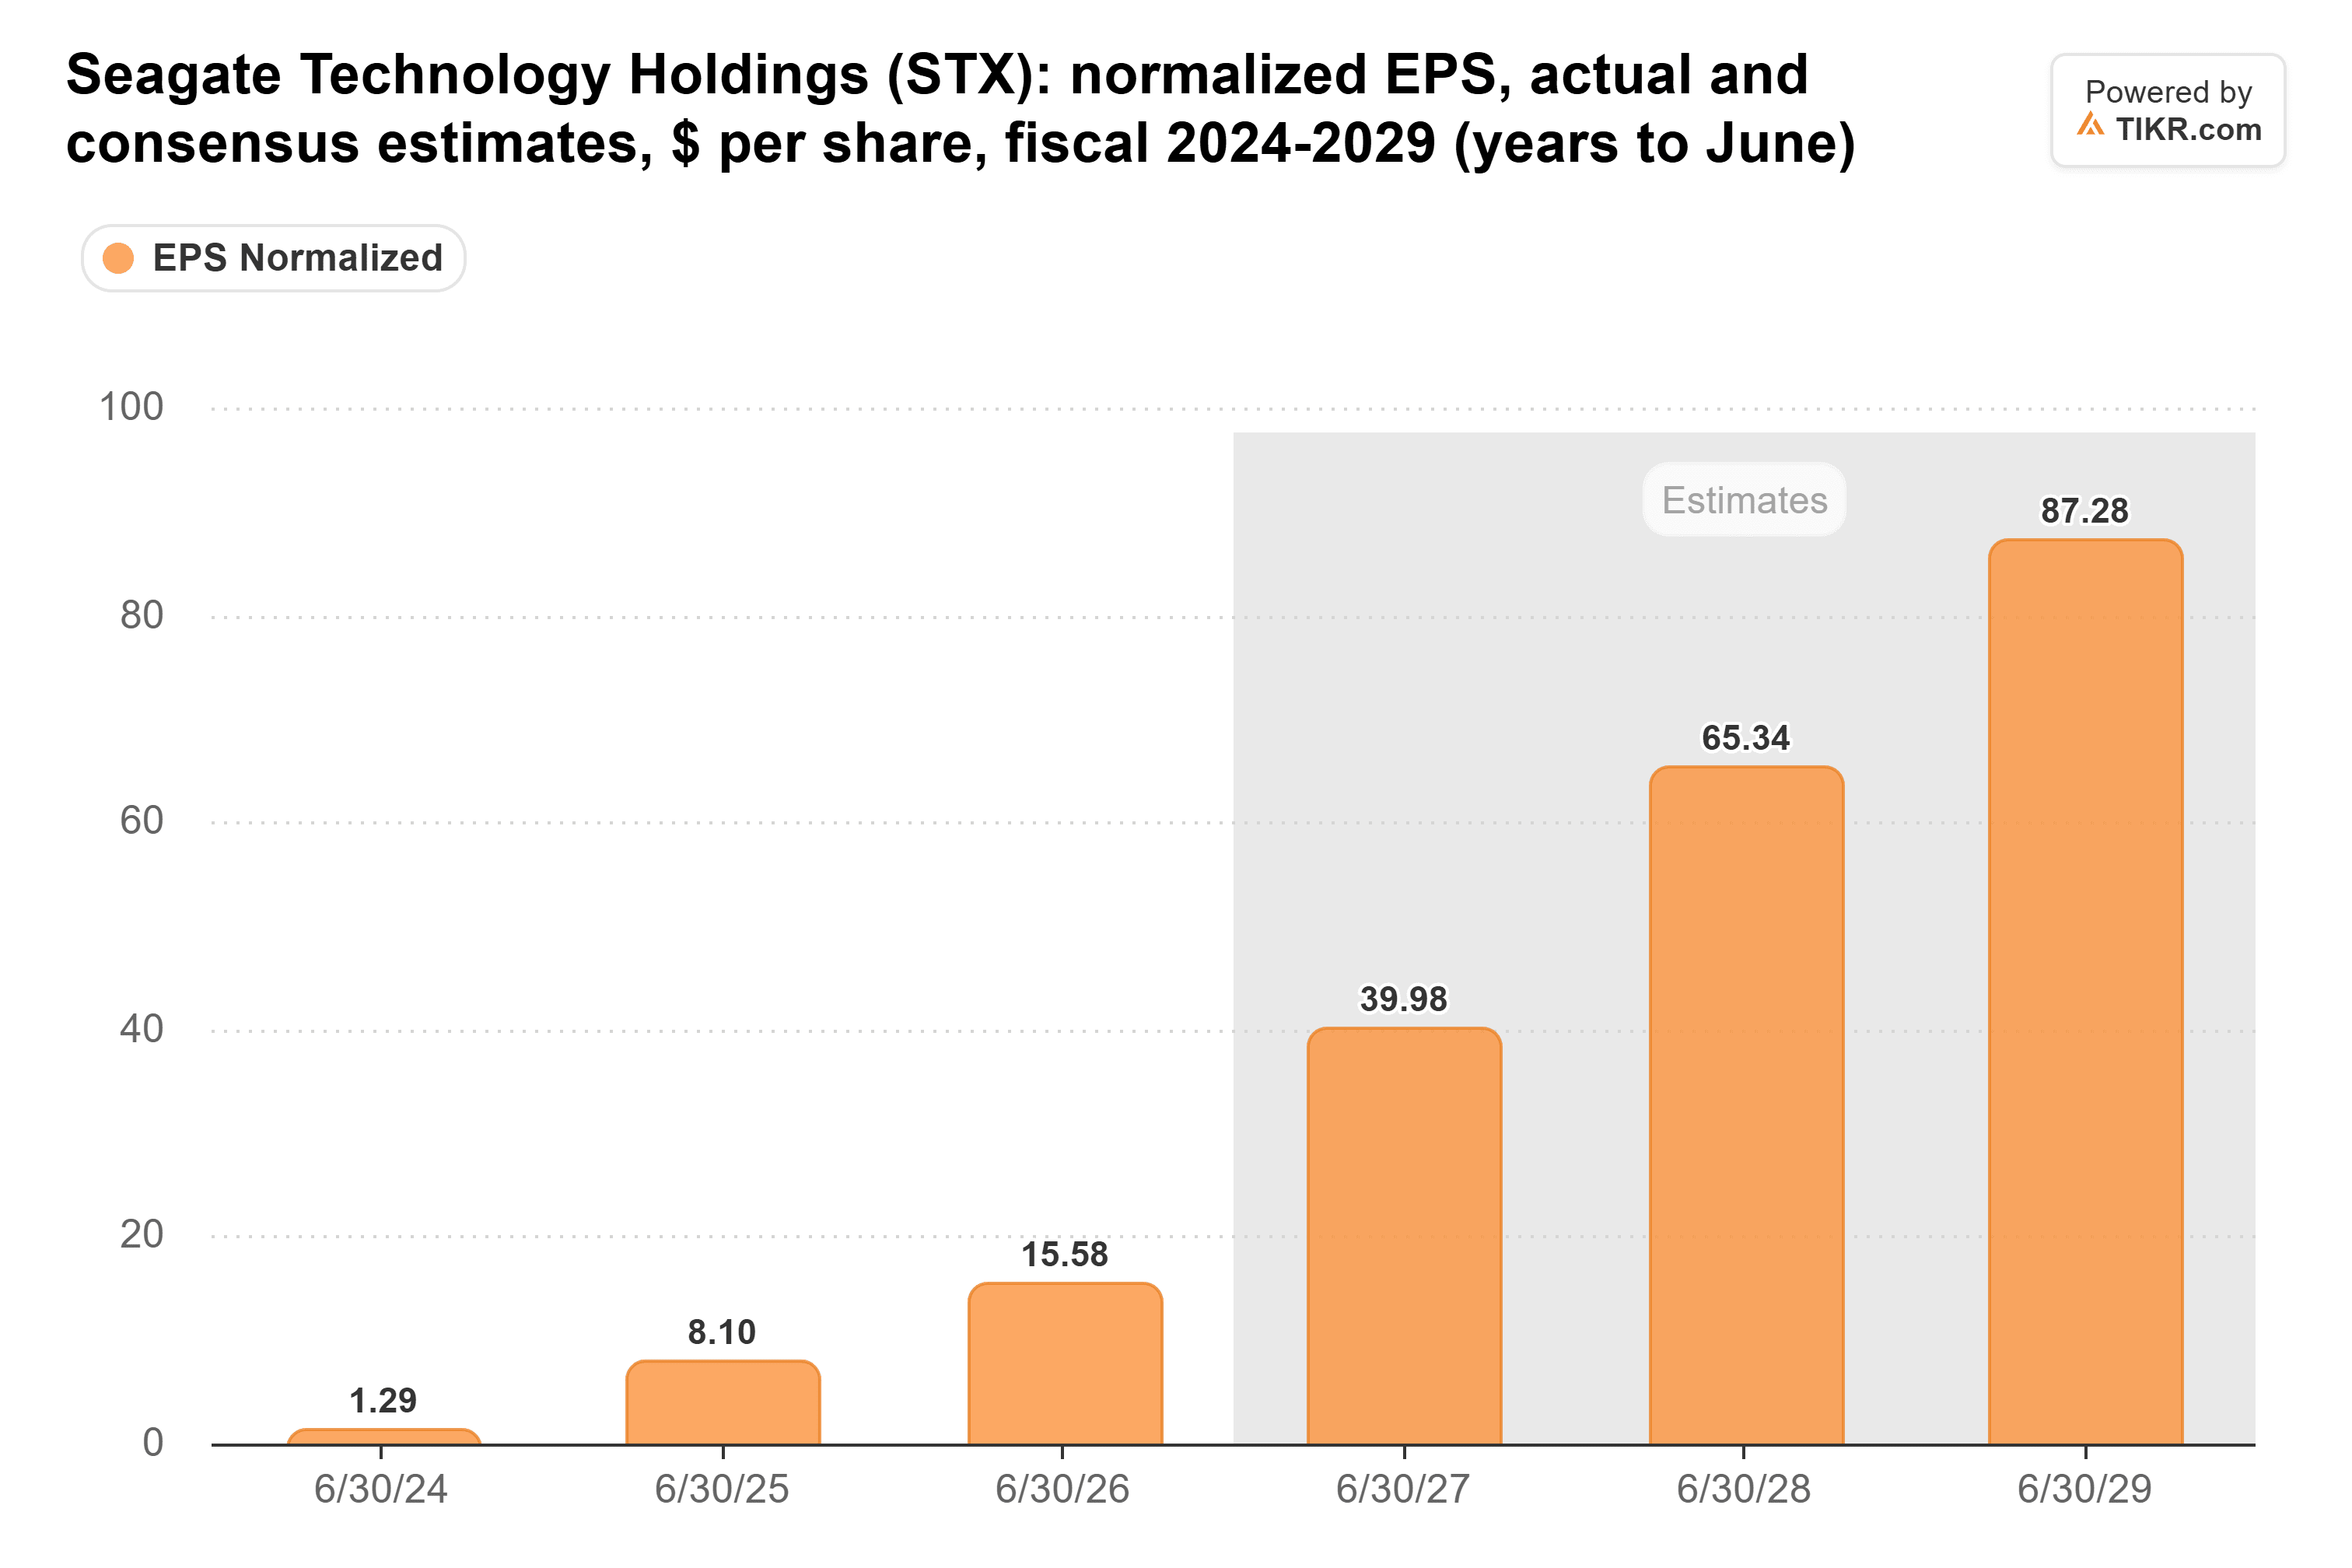
Last week’s selloff was about politics, and I see nothing in Seagate’s results that should push those estimates down.
Yet at Friday’s close, Seagate traded at just 9.8x forward earnings, against a five-year average of 26.2x:
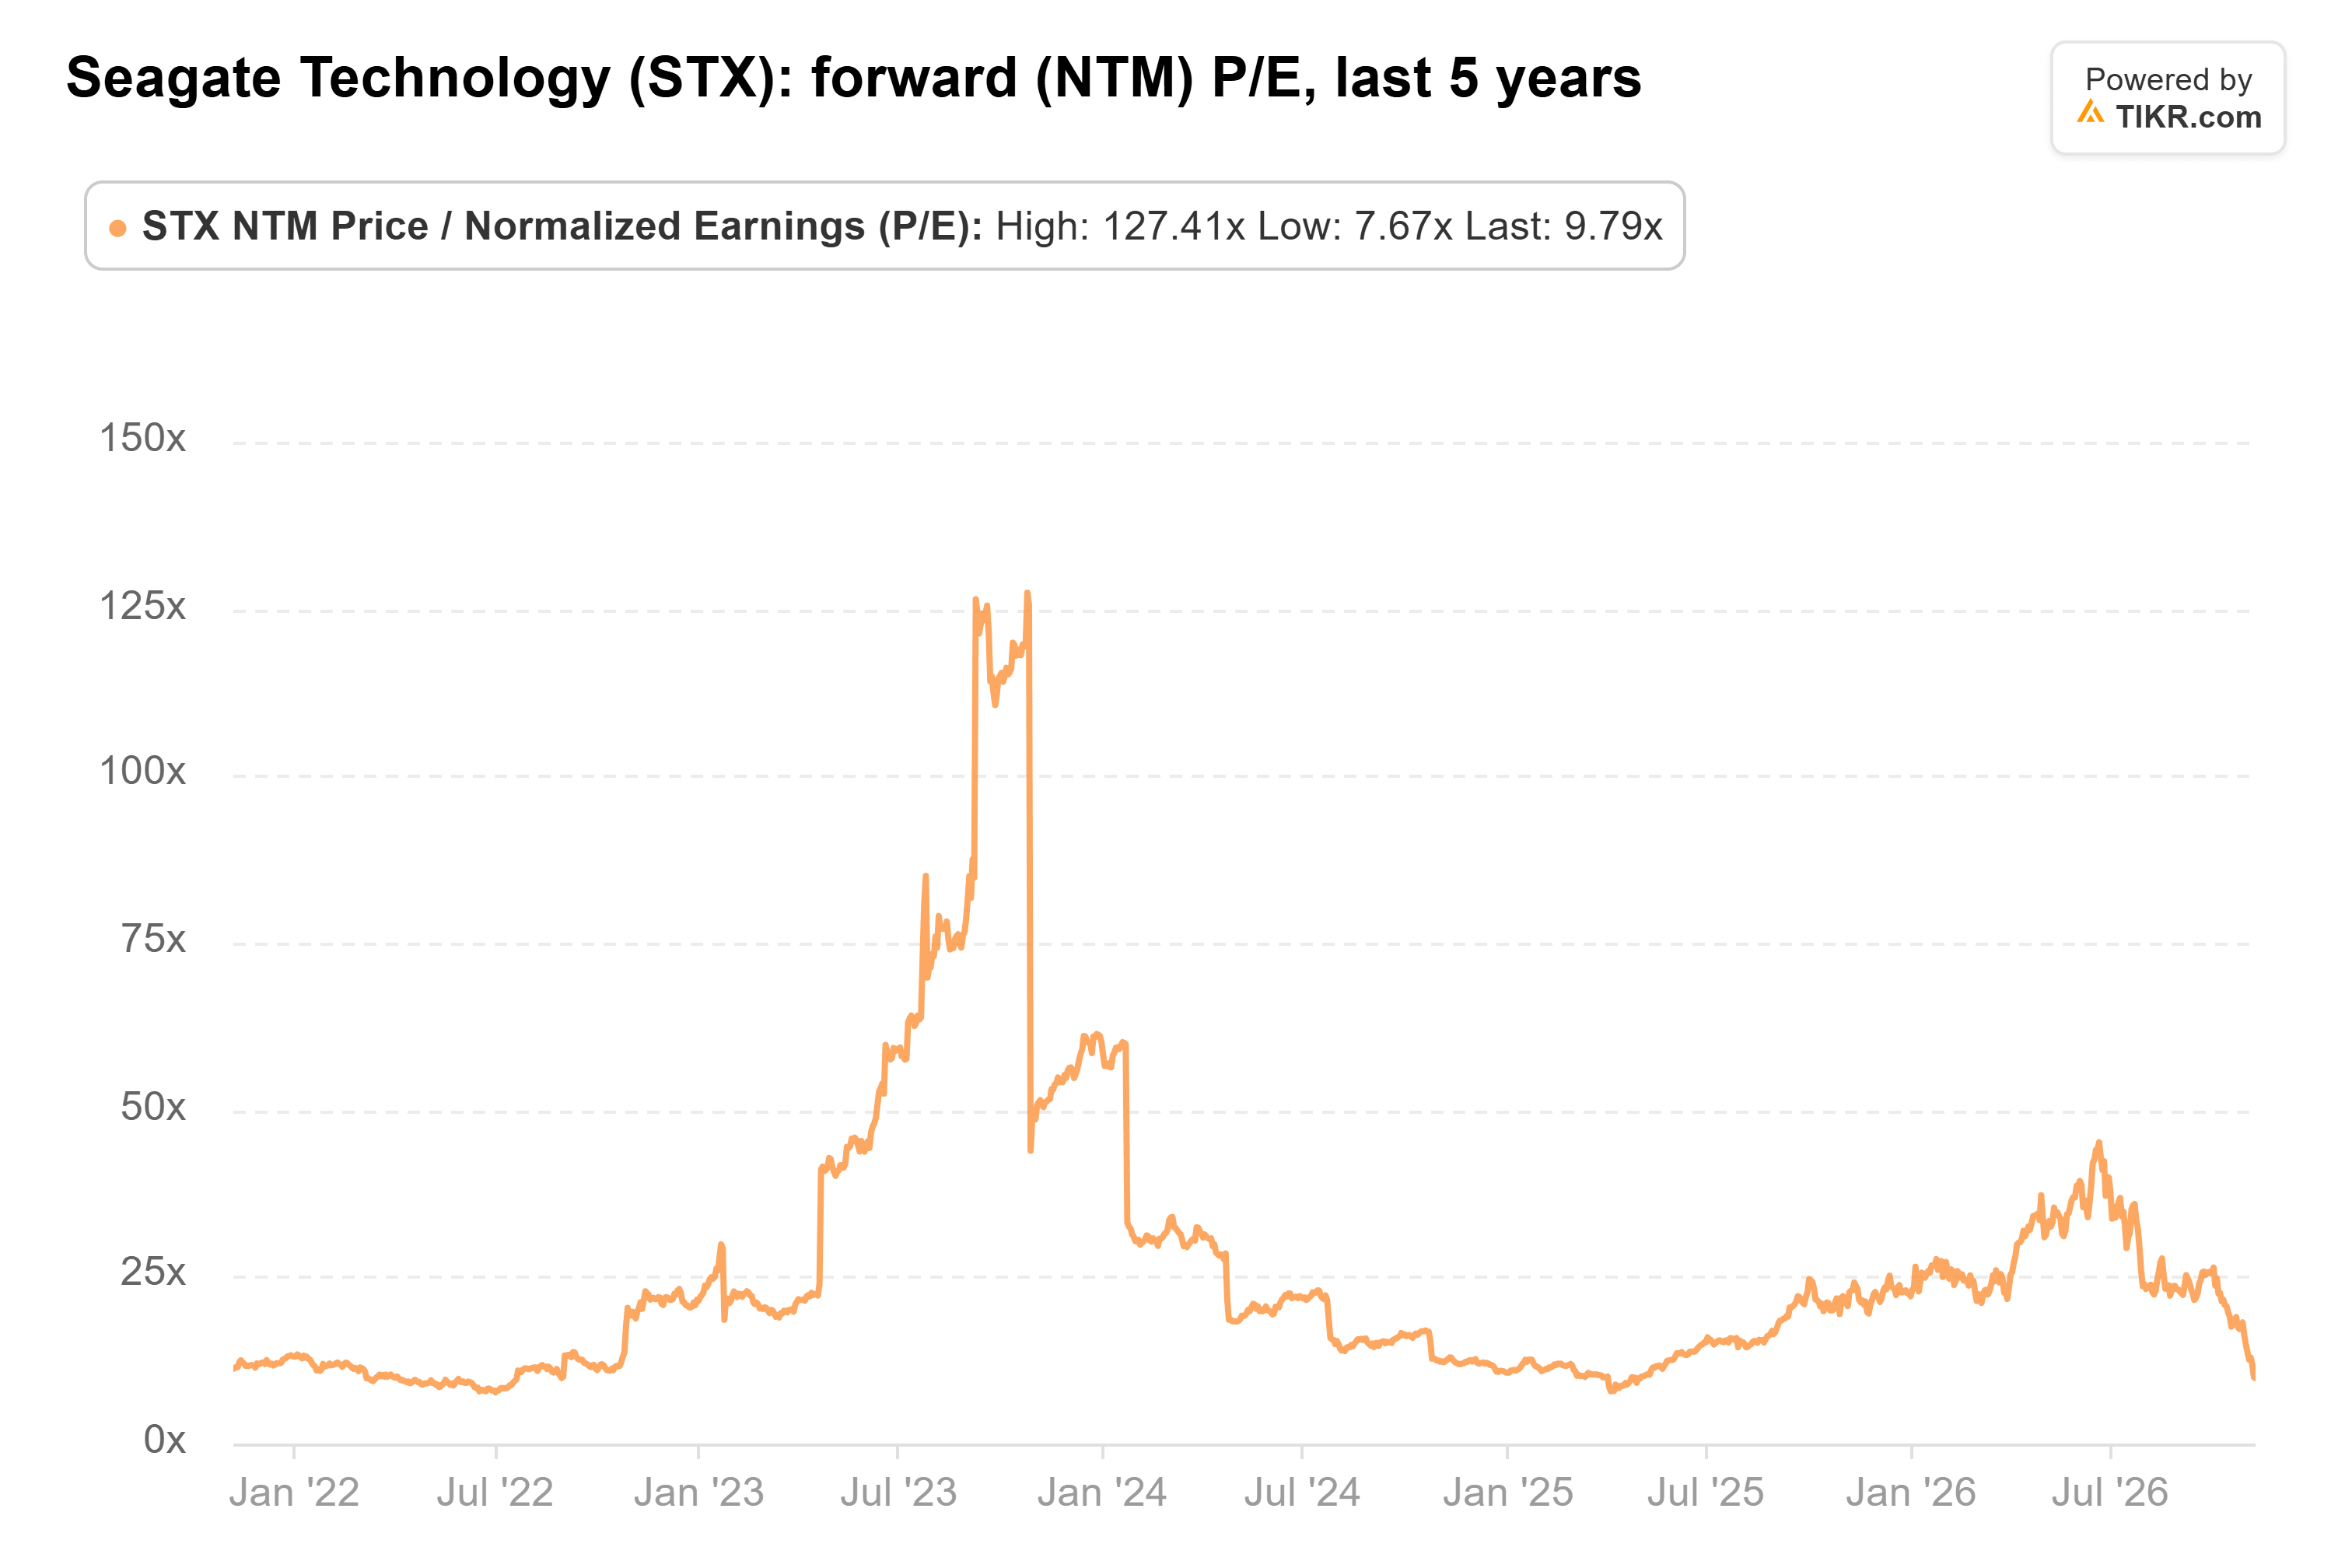
Even after today’s jump, it’s nowhere near that average. Woodring’s target works out to about 18x fiscal 2028’s expected EPS, which is still well below it.
TIKR tracks 26 analysts on Seagate Technology. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Seagate Technology, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Seagate Technology’s Analyst Ratings
Pricing is the whole ballgame
The worry is a repeat of fiscal 2023, when Seagate’s revenue fell 37%. This time, Seagate is growing mostly on price. Revenue per exabyte shipped rose 33% from a year earlier to $19.2 million in the quarter ended Oct. 2, and gross margin has risen for seven straight quarters:
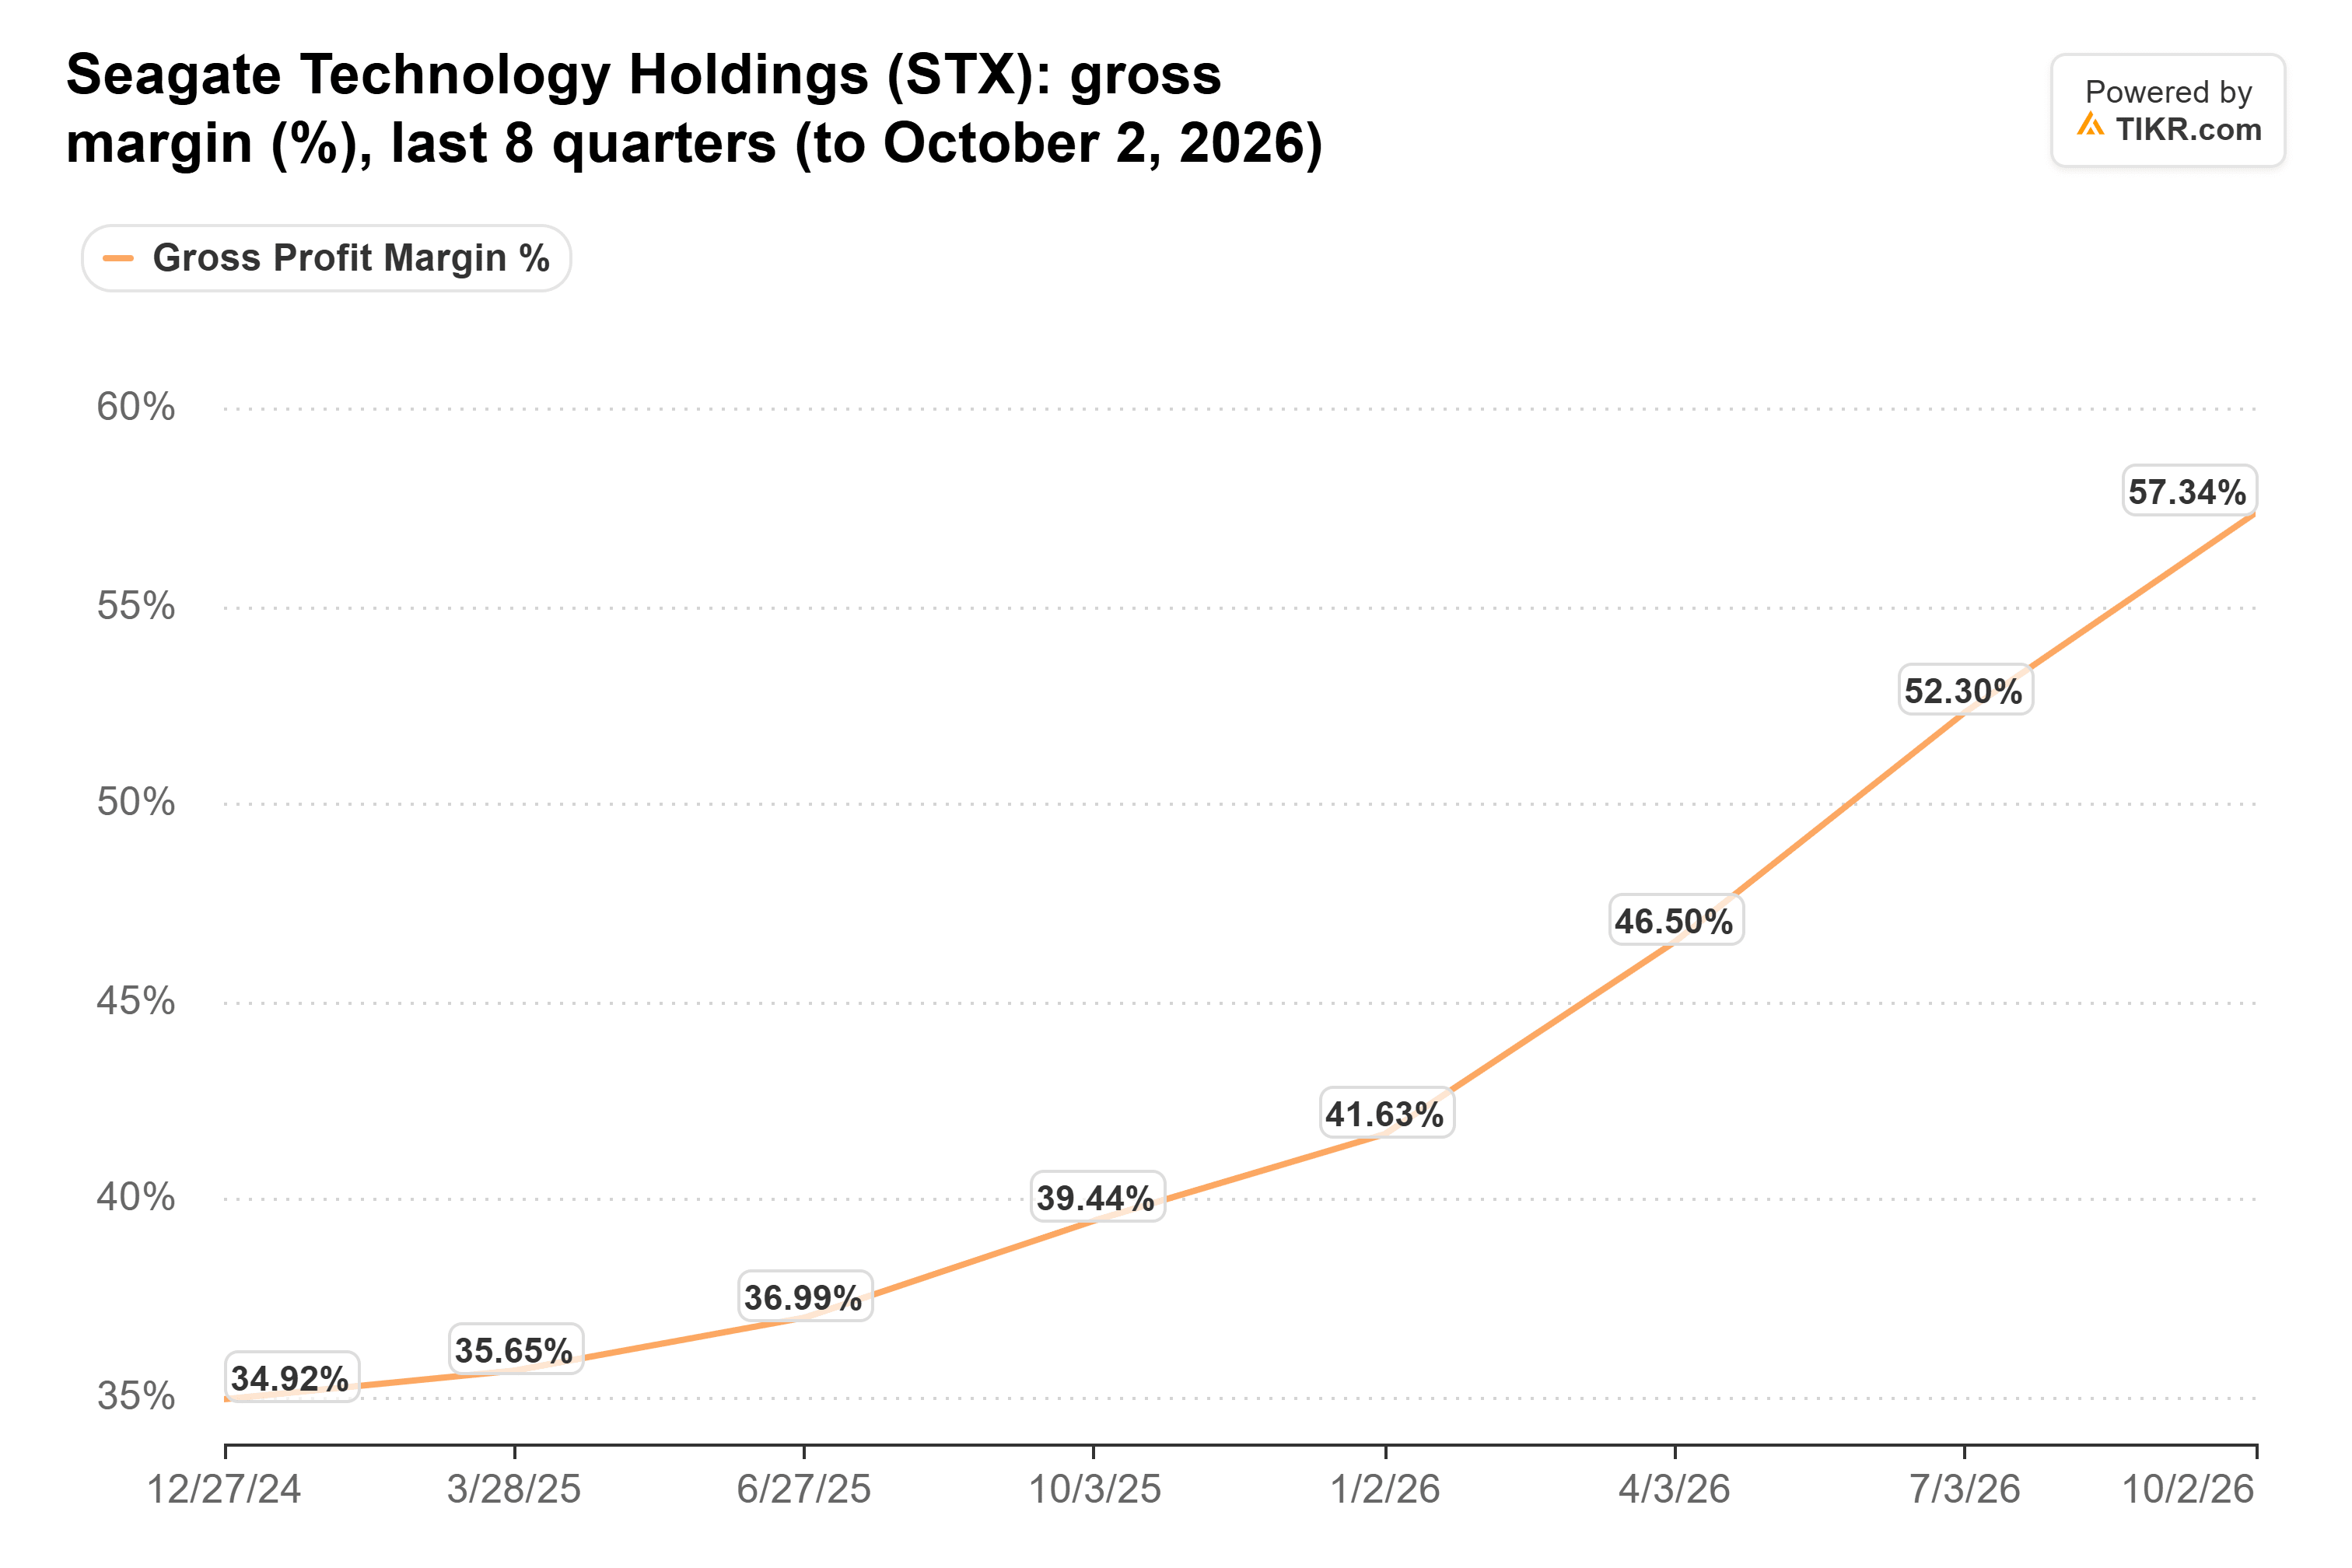
Prices are set through calendar 2027, but 2028’s prices haven’t been agreed yet. Toshiba’s plan to double its hard disk capacity, which Nikkei reported in October, is the clearest threat to them.
The way I see it, the market priced Seagate for an AI slowdown that its results and guidance don’t show, and Woodring’s call looks right. The December-quarter report in late January is the next check, with management guiding for $4.7 billion to $4.9 billion of revenue.
So what is Seagate stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Seagate could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!