Key Takeaways
- Snap shares have rallied 43.8% in three months to $6, with the Q3 report set for November 4.
- Q2 revenue grew 19% to $1.60 billion, and adjusted EBITDA jumped to $250 million from $41 million.
- Blue Duck Capital wants Snap to raise outside capital for Specs, which it estimates costs about $500 million a year.
- Q3 guidance calls for $1.70 billion to $1.74 billion in revenue and $300 million to $350 million in adjusted EBITDA.
For years, Snap had plenty of users and too little cash. That gap is closing.
Snap (SNAP) closed Friday at $6, up 43.8% over three months as investors warmed to a leaner ad business and a hardware bet that suddenly has enterprise partners. The stock still sits about 31% below its 52-week high of $9.
Now an activist wants someone else to help pay for that hardware.
The ad machine started paying
Q2 was Snap’s cleanest quarter in a while:
- Revenue grew 19% to $1.60 billion, ahead of the $1.54 billion consensus.
- Adjusted EBITDA rose to $250 million from $41 million.
- Free cash flow reached $121 million, up from $24 million.
The net loss narrowed to $164 million from $263 million. Daily active users rose 5% to 493 million, and ARPU climbed to $3.25 from $2.87, so monetization did more of the work than user growth.
CEO Evan Spiegel said in the earnings release that Snap is “investing with discipline to increase free cash flow per share over time.” The share count, flat at about 1.68 billion, suggests he means it.
Cash flow is the line to watch.
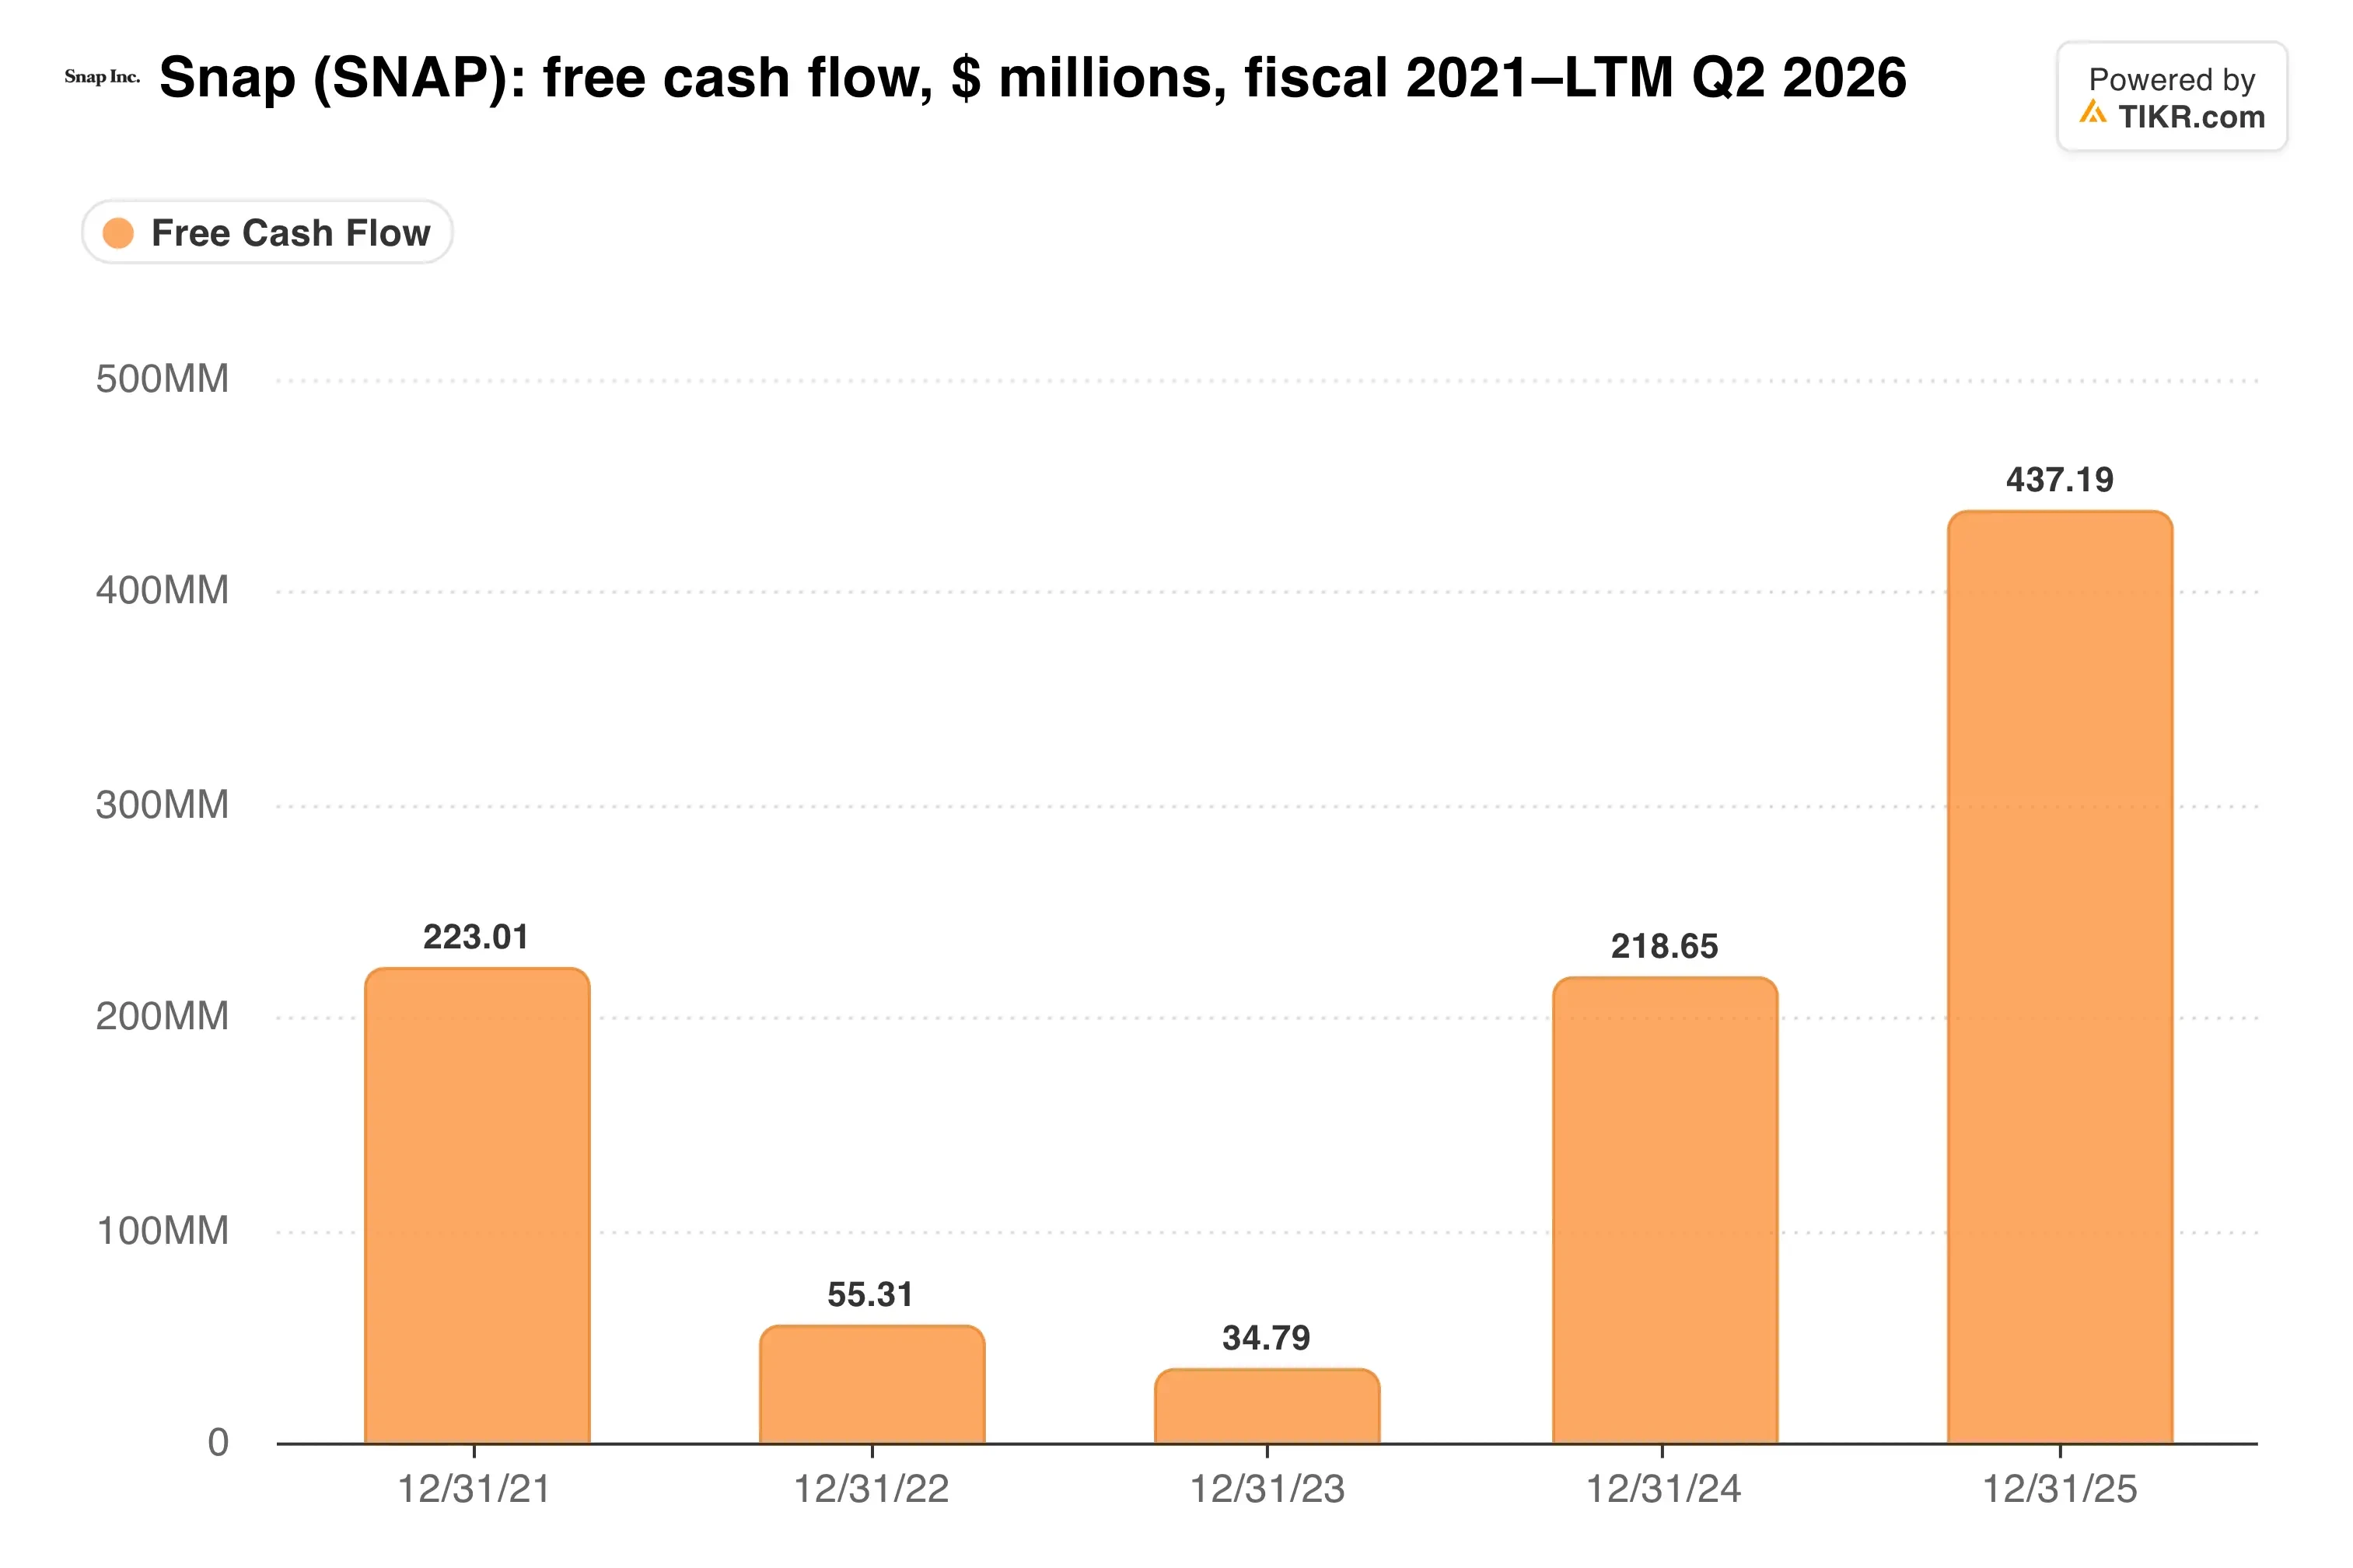
Positive free cash flow gives Snap room to fund Specs without tapping markets, at least for now.
Specs goes to work
Snap unveiled Specs in June at $2,195, with shipping expected later this fall in the U.S., UK and France. In September, it lined up Salesforce (CRM), Nvidia (NVDA) and Amazon (AMZN) Web Services to bring workplace AI tools to the glasses, along with Trifork and Hololight.
The pitch targets field service, retail and remote support, where hands-free computing has a clearer payback. Salesforce’s Agentforce will let workers pull company data, and Snap added Specs Intelligence, an AI service that runs across glasses, iPhone and Mac.
The consumer market is crowded. Meta Platforms (META) dominates smart glasses with its Ray-Ban line and launched a new AI gadget called Charm in September.
Where does that development money land?
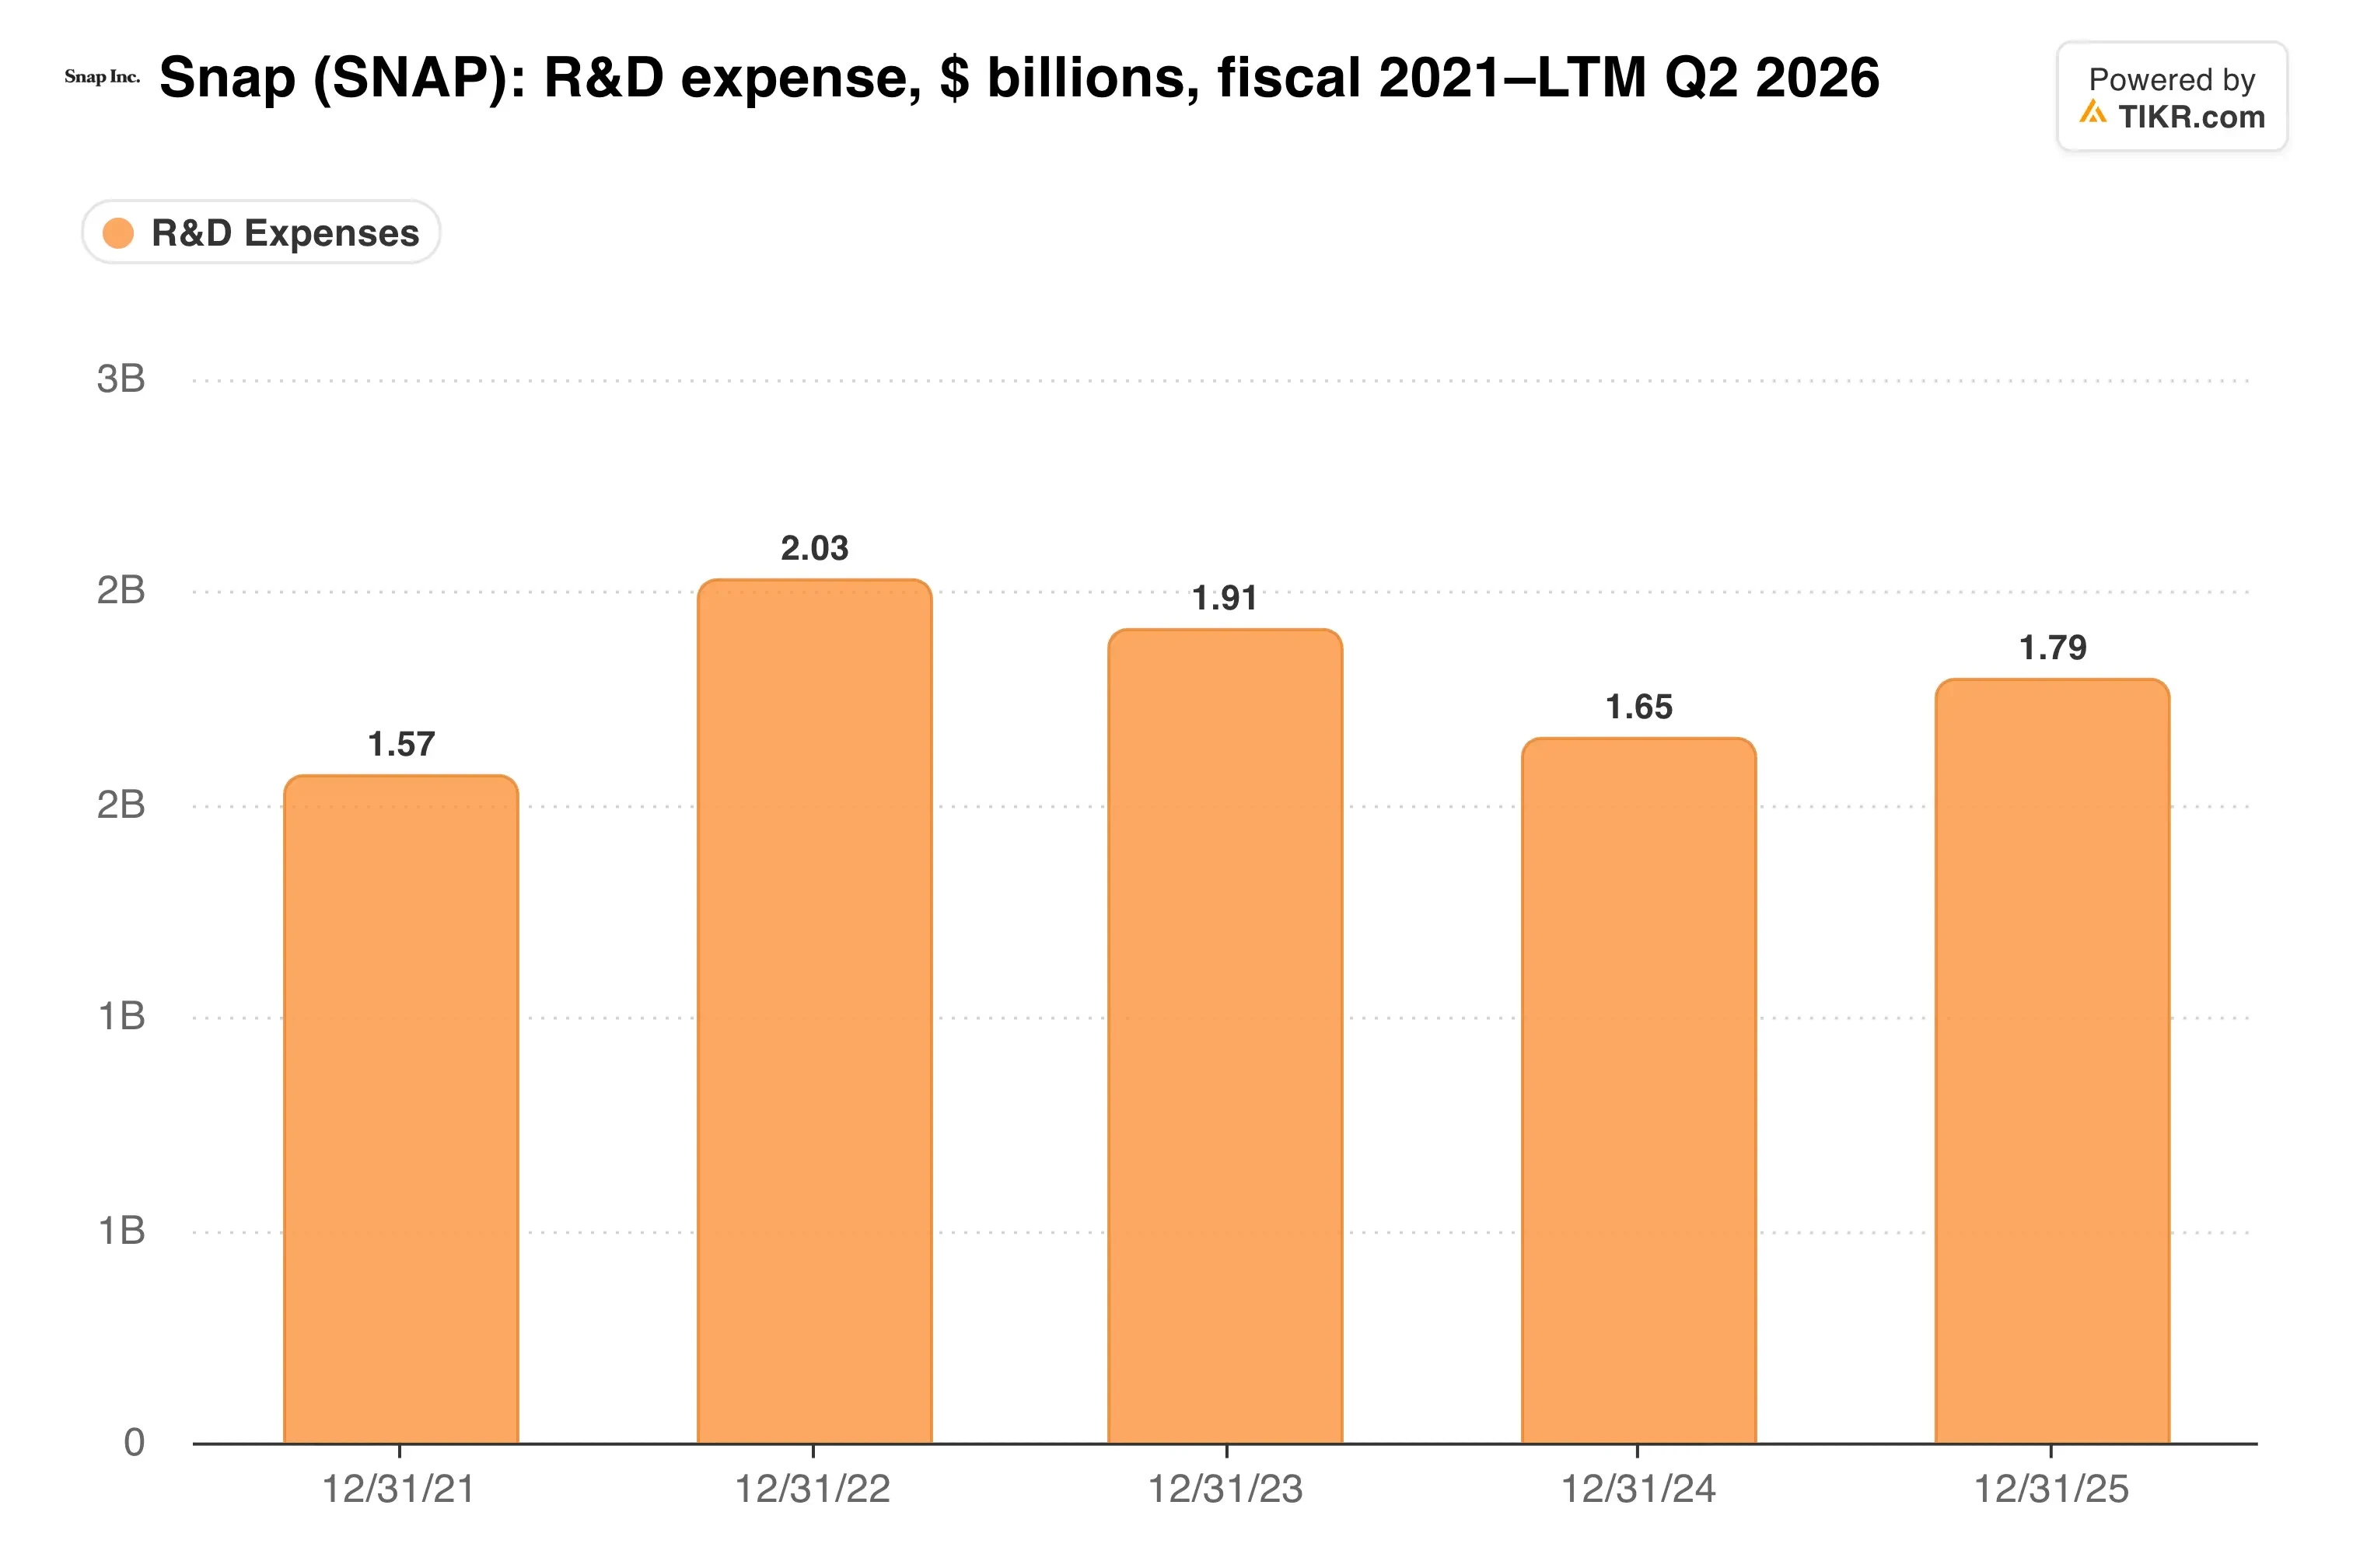
R&D is where most Specs spending sits, so any outside funding would ease this line first.
TIKR tracks 42 analysts on Snap. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Snap, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Snap’s Analyst Ratings
The case for splitting the bill
Blue Duck Capital urged Snap’s board to raise external capital for Specs, arguing it would unlock sum-of-the-parts value. The fund estimates Specs costs about $500 million a year and says outside funding could lift the stock to $12 to $14.
The valuation gap makes that argument easy to follow. Snap trades at 8.3x forward EBITDA and 1.7x forward revenue, while Roblox (RBLX) trades at 30.4x and 5.1x.
Consensus expects that EBITDA to keep climbing…
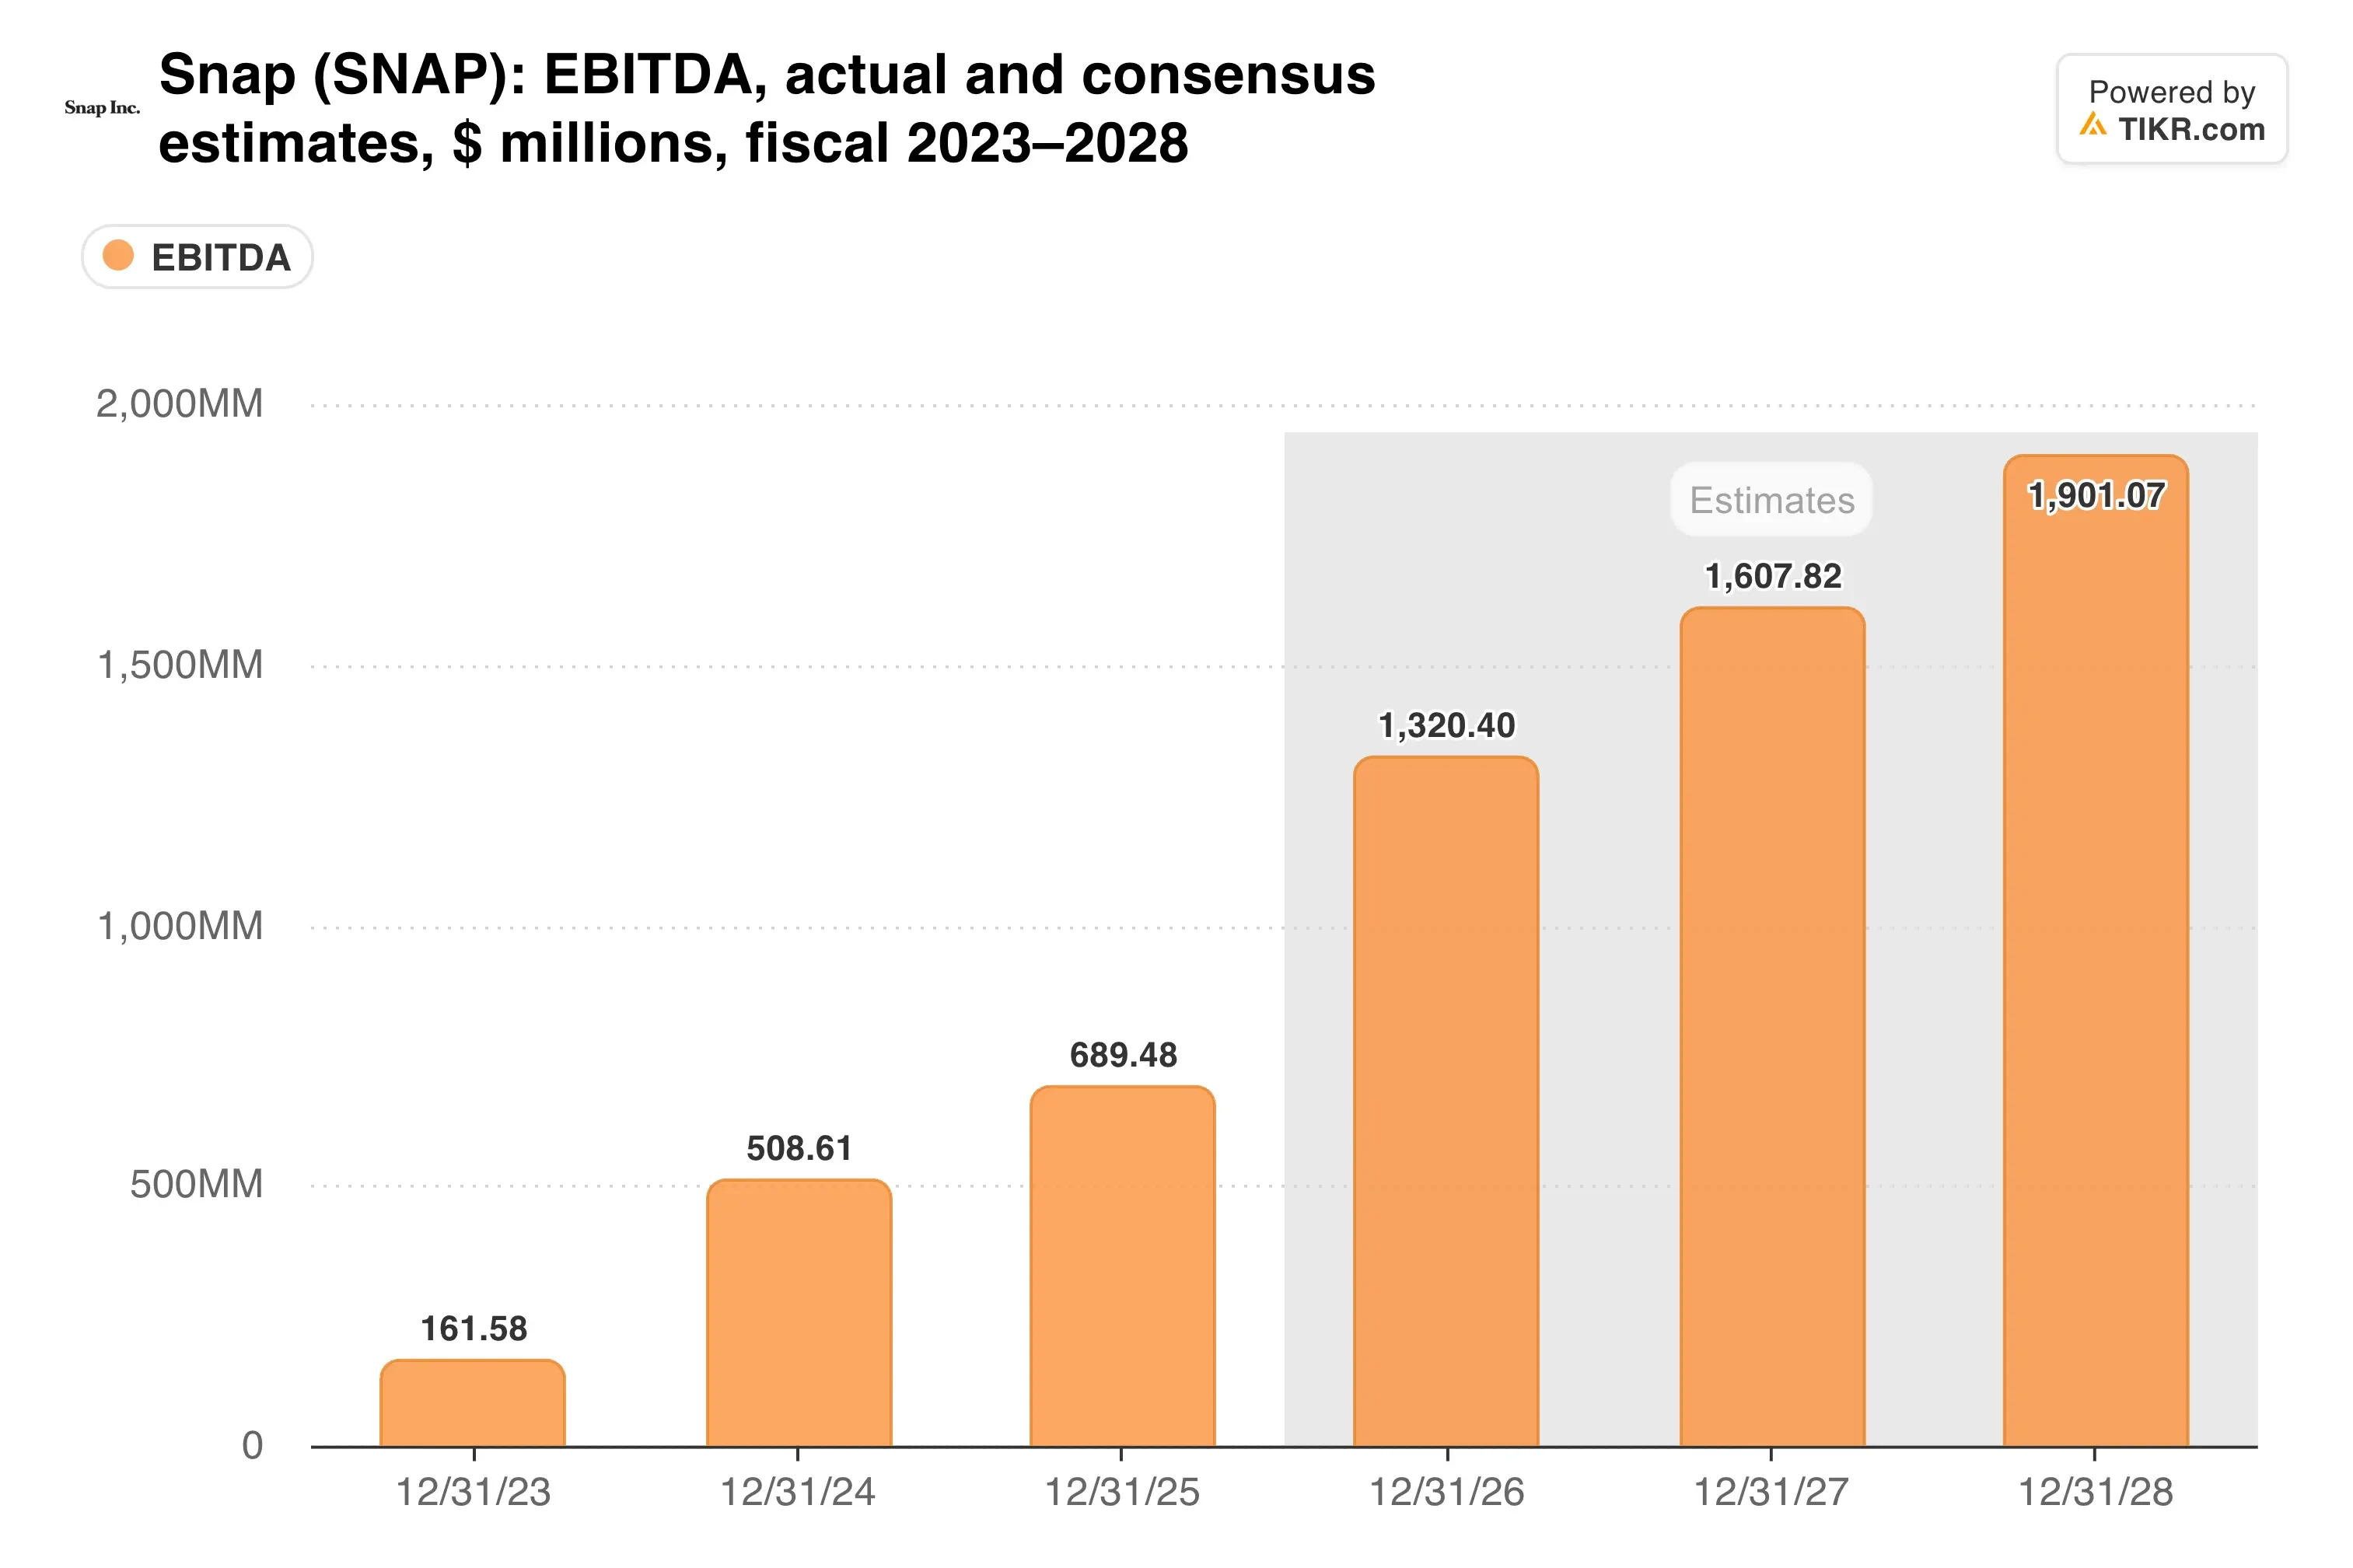
Analysts model roughly 52.7% annual EBITDA growth over the next two years, yet the average Street target of $7.44 implies only about 17% upside.
Regulation is the biggest wildcard. Florida can now enforce its law barring young children from social media, California enacted new curbs, and Norway is targeting an under-16 ban.
My take: Snap’s core business finally looks self-funding, and the multiple is cheap for a company guiding to $300 million to $350 million in Q3 adjusted EBITDA. I like the outside-funding idea if terms are fair, because it would separate a promising experiment from a cash-generating ad business. Until Specs ships and shows enterprise orders, though, I’d value it near zero.
Snap reports on November 4. Revenue of $1.70 billion to $1.74 billion is the guide, and any Specs funding plan or launch date will matter just as much.
So what is Snap stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Snap could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!