Key Takeaways
- Roblox reports Q3 results on October 29 after guiding bookings to $1.58 billion to $1.65 billion, a 14% to 18% decline and its first forecast drop.
- Q2 bookings grew just 8% to $1.56 billion even as daily active users rose 10% to 123 million.
- Shares at $53 are down 59.1% over the past year and trade above the $50 average analyst target.
- More than 180 federal child-safety cases and a new AI creation platform from Alphabet and Unity add risk beyond the bookings reset.
A year ago, Roblox was one of the market’s favorite growth stories. Today it is guiding to shrinking bookings.
Roblox (RBLX) closed Friday at $53, down 59.1% over the past year and about 61% below its 52-week high of $135. It even trades above the $50 average analyst target, a sign of how far estimates have fallen.
Thursday’s Q3 report is the first test of management’s reset. Investors mostly want to know whether this is the bottom.
Engagement grew as spending stalled
Q2 pulled in two directions:
- Revenue rose 36% to $1.47 billion.
- Bookings grew 8% to $1.56 billion, the low end of guidance and down from 70% growth in Q3 2025.
- Daily active users rose 10% to 123 million, with 82% outside the U.S. and Canada.
Players drifted away from high-spending viral hits. At the same time, Roblox retuned discovery to favor long-term retention at the expense of near-term spending, which hit monetization.
Revenue still grows because Roblox recognizes most bookings over about 27 months. So the 2025 surge keeps flowing into reported results.
Reported revenue hides the slowdown, at least for now…
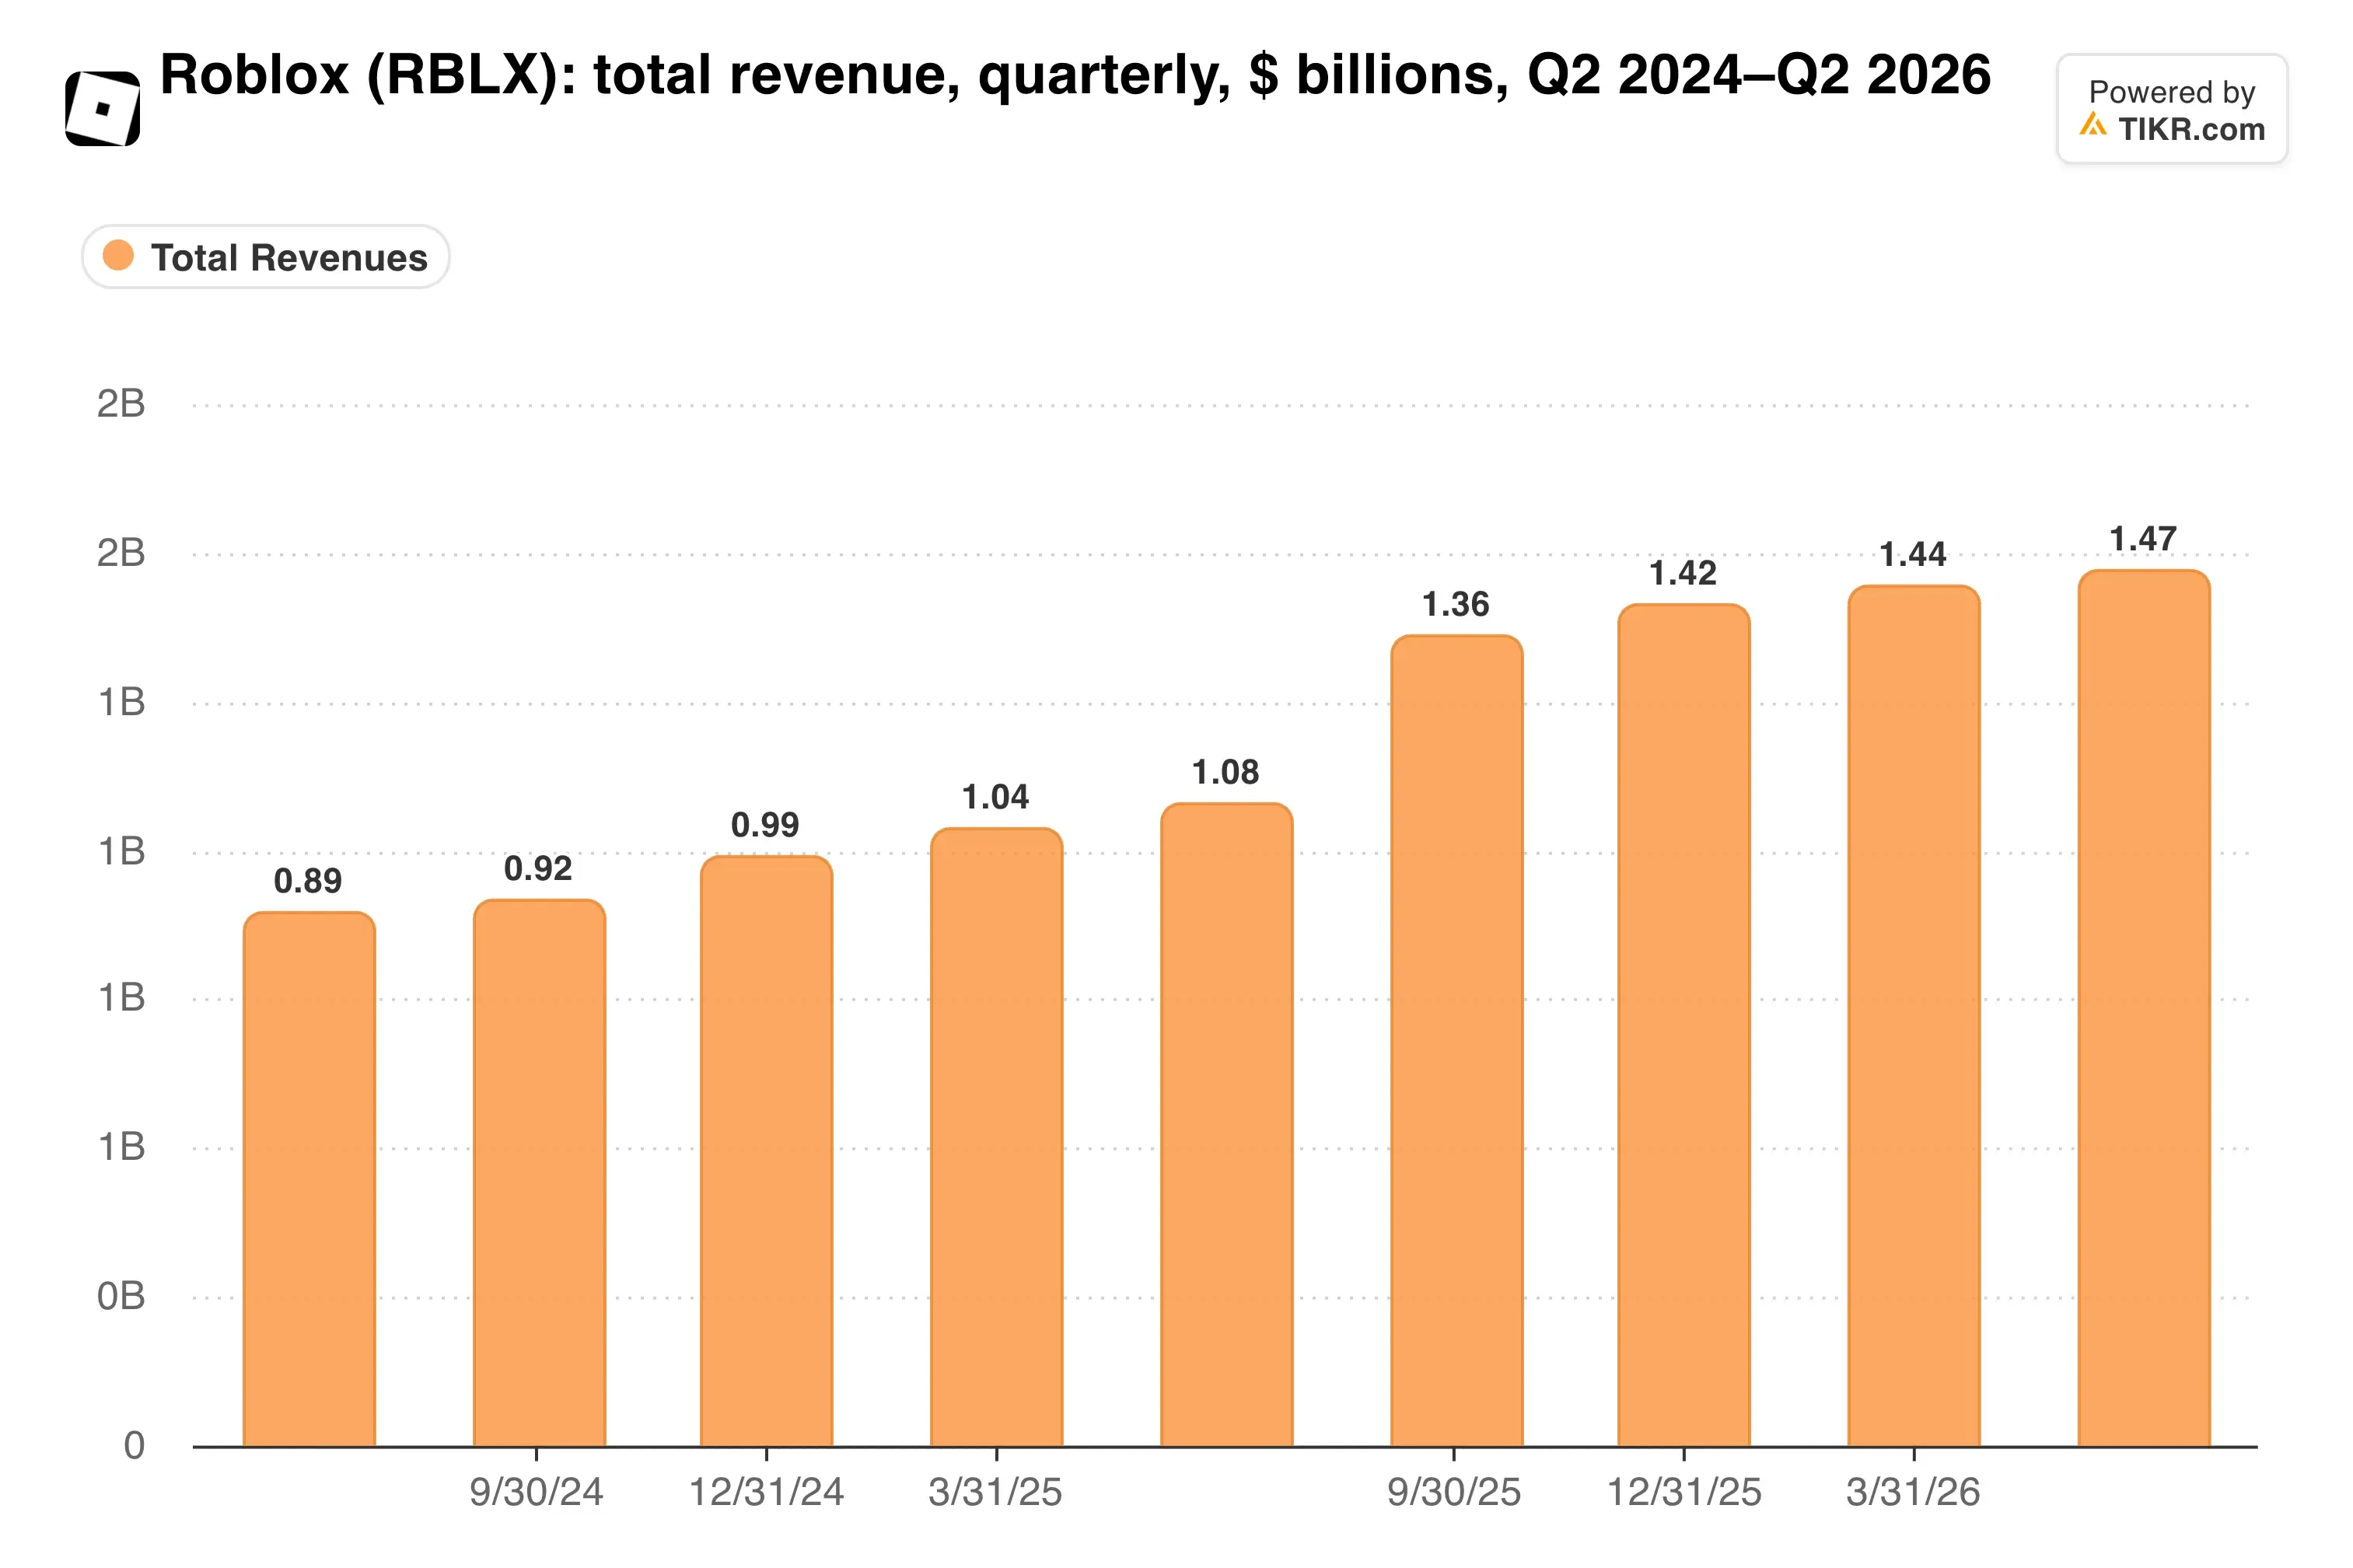
That lag is running out. Q3 guidance calls for revenue growth of just 4% to 10%.
A reset with a long fuse
For Q3, Roblox guided bookings to $1.58 billion to $1.65 billion, a 14% to 18% decline. Adjusted EBITDA is expected between roughly break-even and $41 million. Management also pulled full-year guidance and moved to quarterly outlooks only.
The long-term pitch stands. “Our conviction in the ability to deliver 20%+ compounded top line growth over the long term has not changed,” management wrote in its Q2 shareholder letter.
Safety changes add friction. Roblox now requires facial age checks for chat access, runs age-based accounts with tighter limits, and has expanded parental controls. Those steps protect the platform but likely weigh on engagement in the near term.
Competition is shifting too. Alphabet (GOOGL) and Unity Software (U) announced an AI-powered game creation platform on October 7, and Roblox shares fell on the news. Roblox has answered with its own expanded creator tools.
Against a fellow youth platform, the premium stands out.
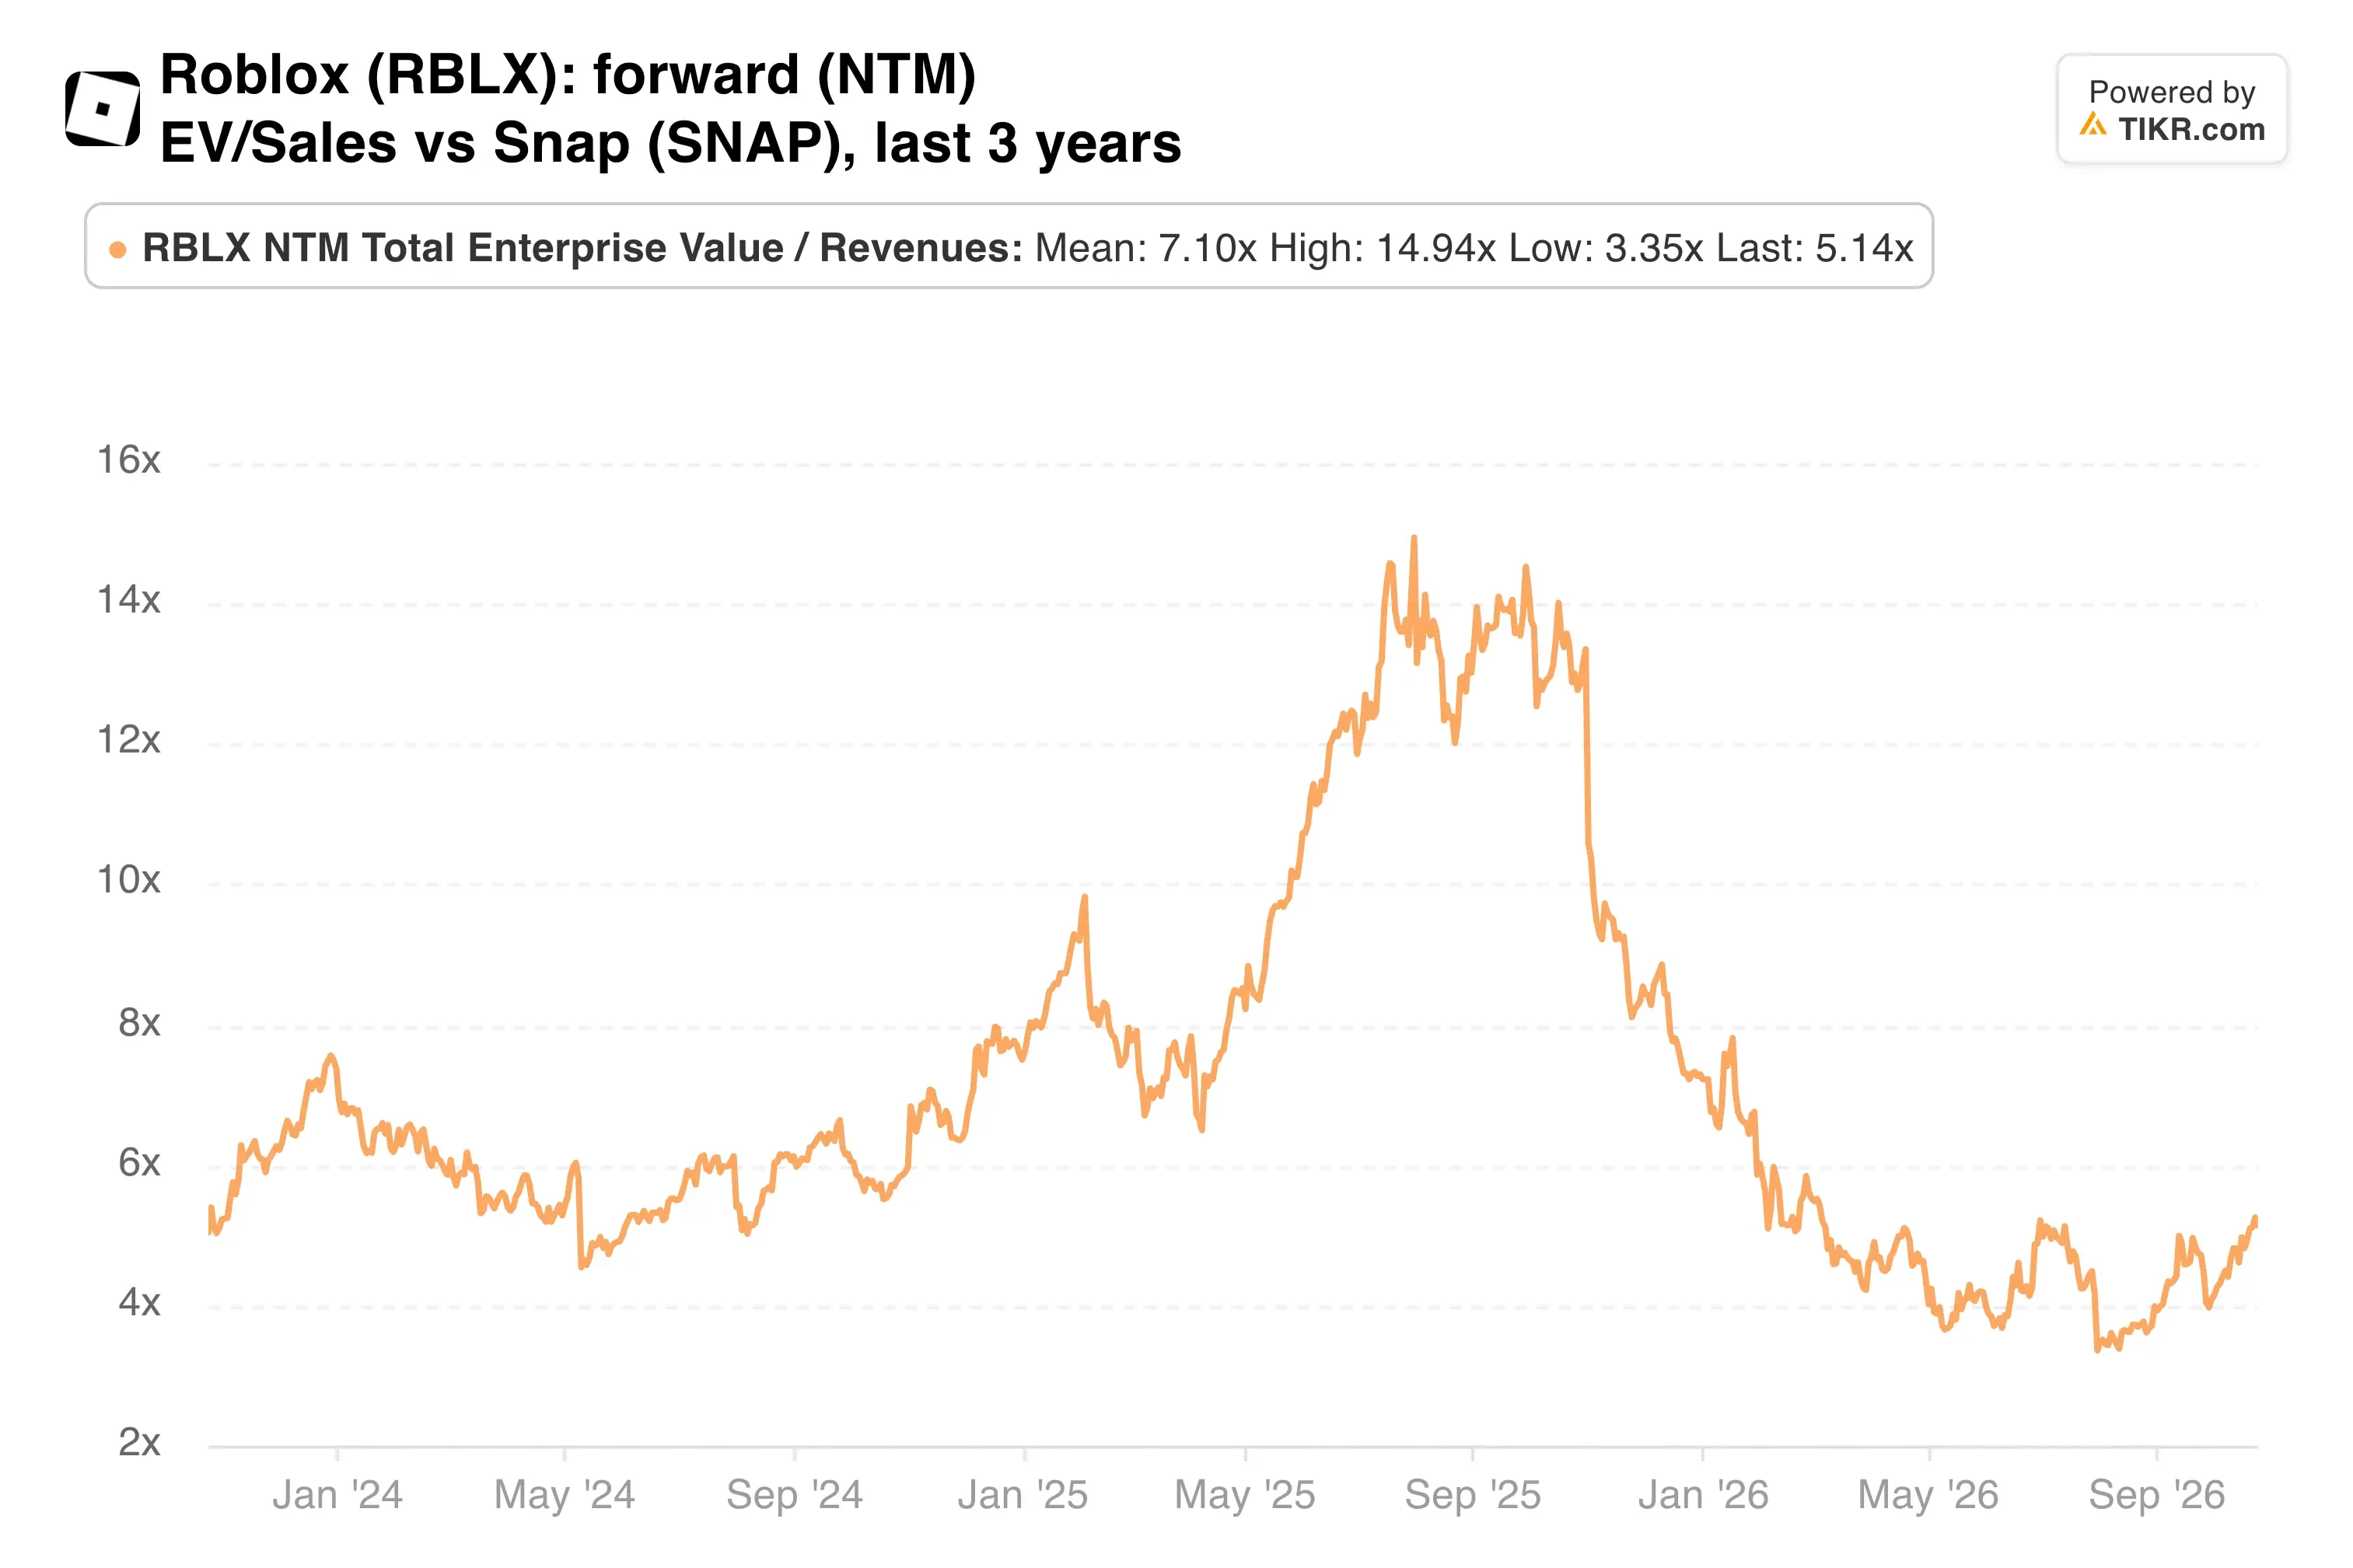
Roblox trades at 5.1x forward revenue, while Snap (SNAP) fetches just 1.7x, even though both face the same proposed under-16 ban in Norway.
TIKR tracks 34 analysts on Roblox. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Roblox, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Roblox’s Analyst Ratings
Legal risk meets a rich multiple
Legal exposure keeps widening. Roblox lost its bid to halt Los Angeles County’s lawsuit alleging child sexual exploitation on the platform. It has settled with attorneys general in Alabama, West Virginia and Nevada for more than $30 million, and more than 180 related cases sit in federal multidistrict litigation.
Europe will also hold Roblox to its strictest rules for very large online platforms.
Then there is valuation.
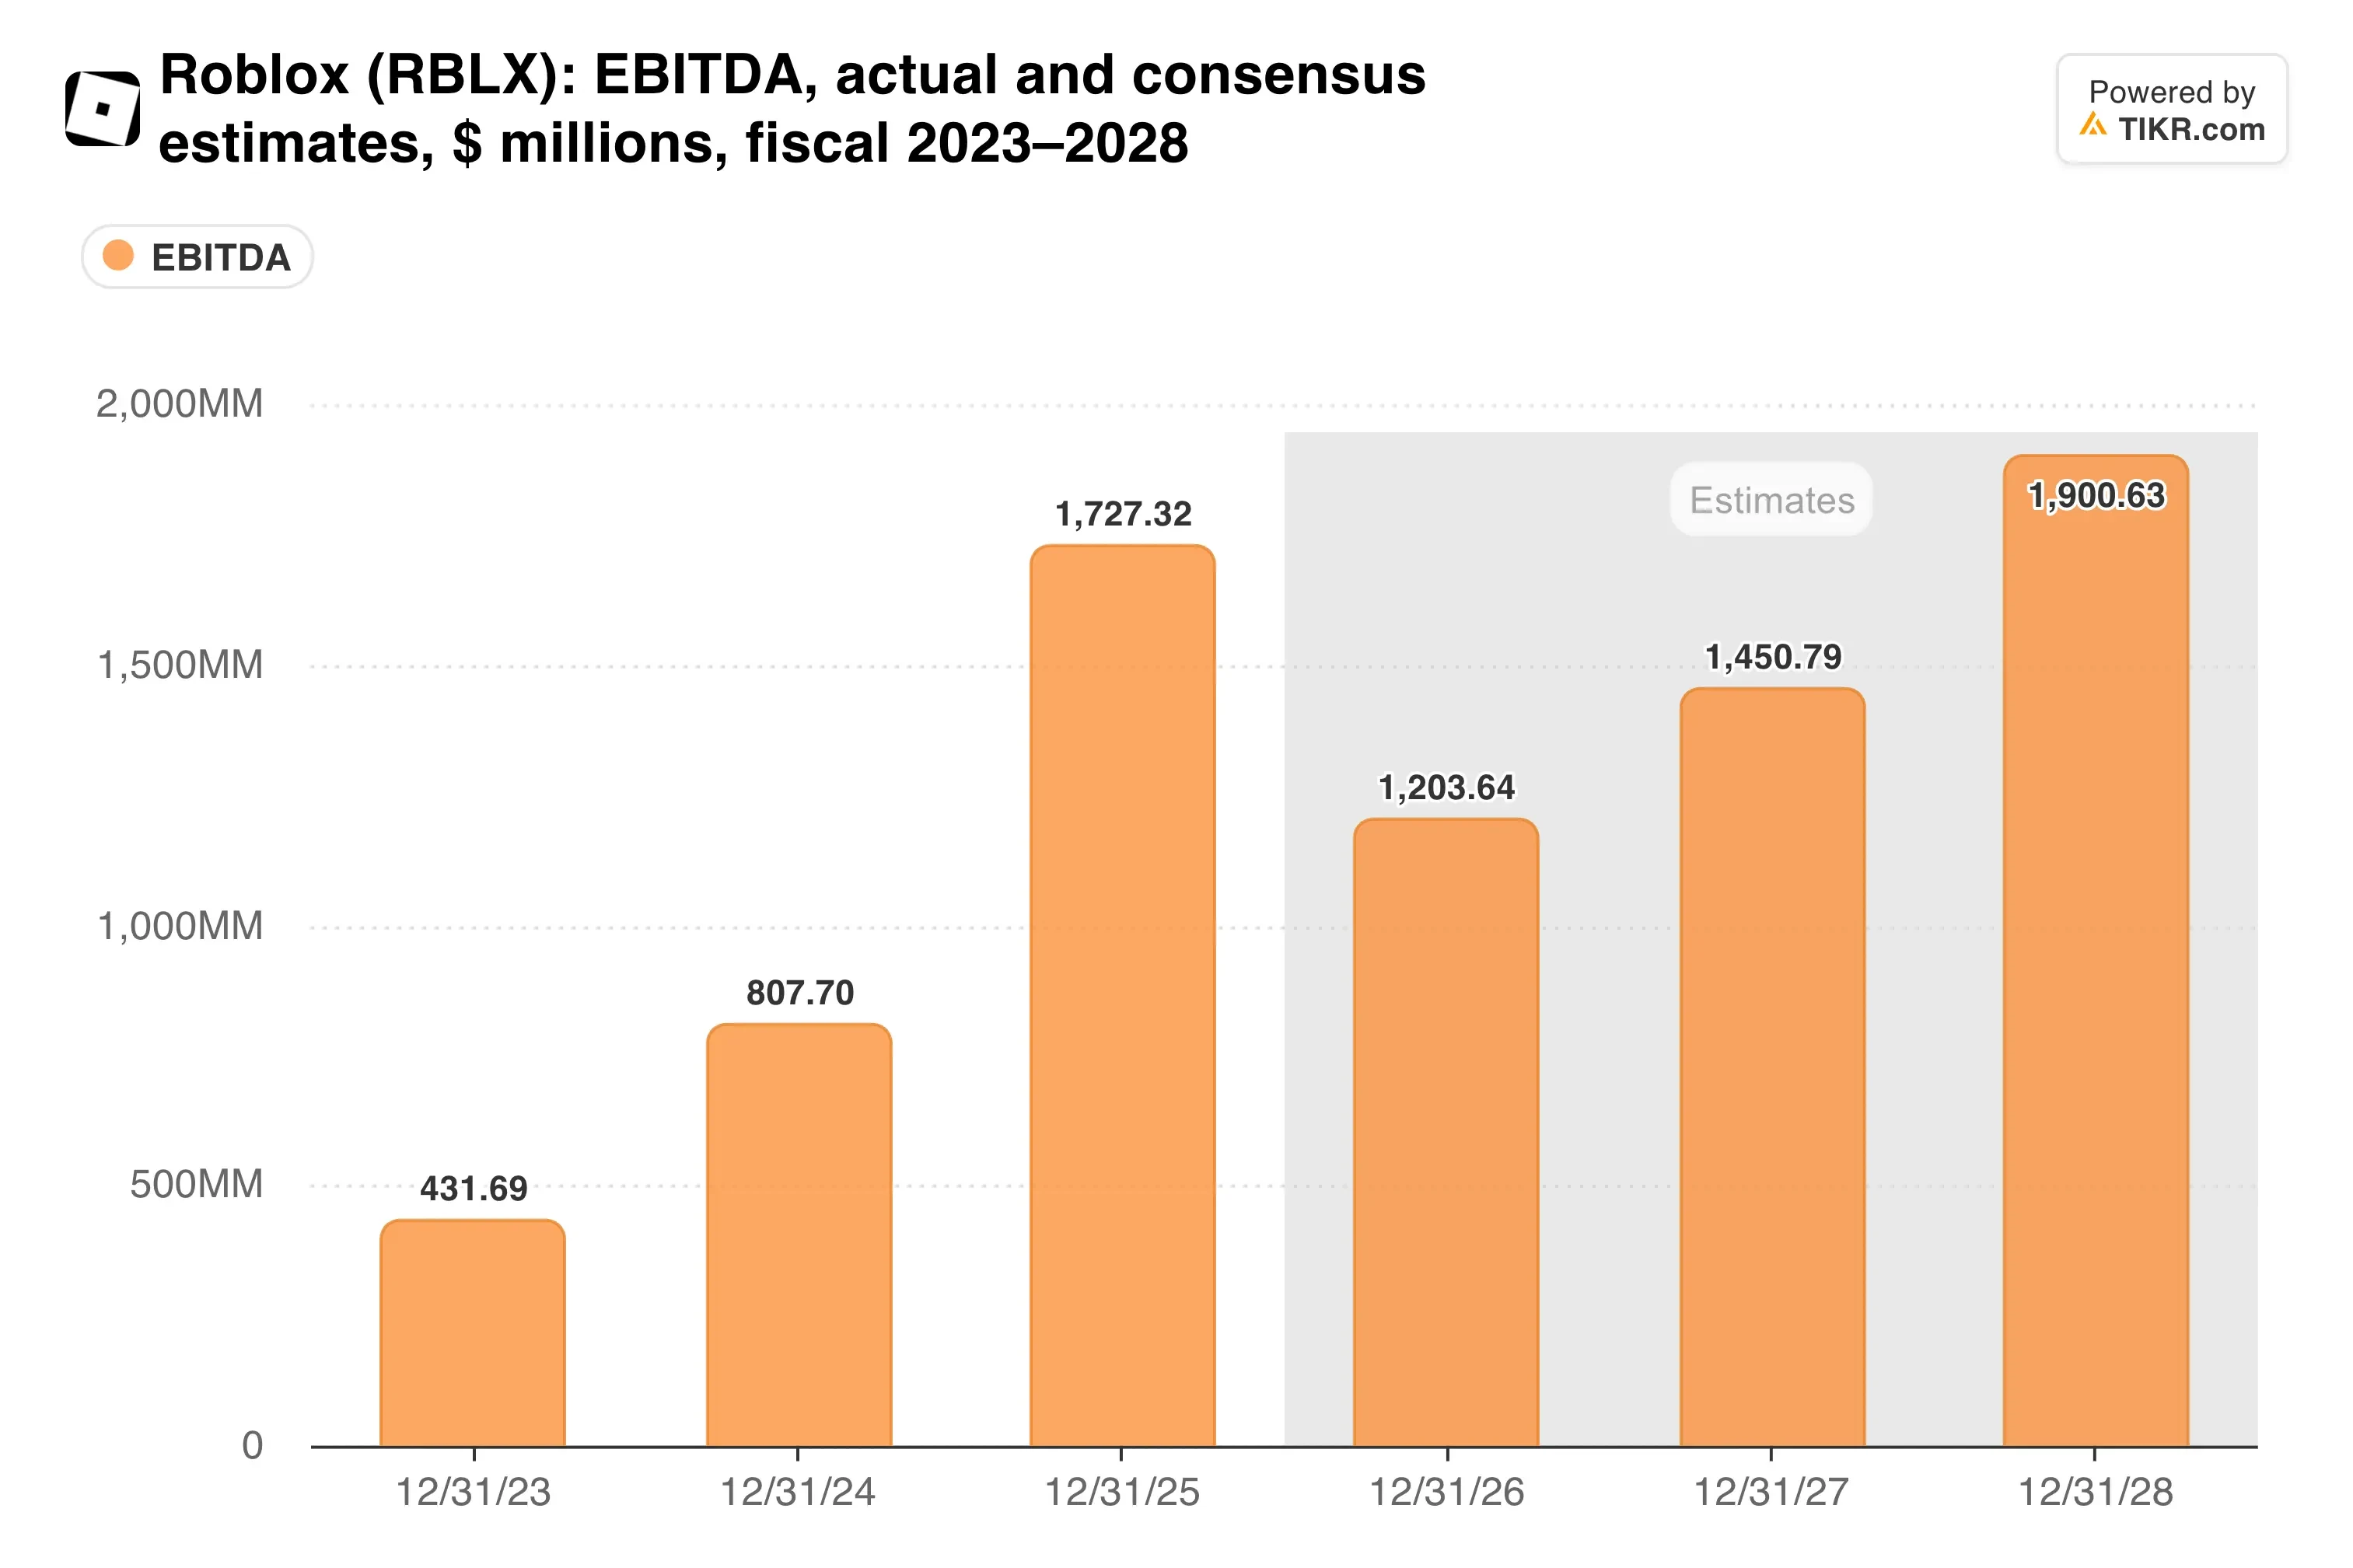
Consensus sees EBITDA shrinking at an 8.4% annual rate over the next two years, yet the stock still trades at 30.4x forward EBITDA. The $1.18 billion net cash position buys time, but it does nothing for the multiple.
My take: The user base looks healthy, and international growth gives Roblox a long runway. However, paying 30x forward EBITDA for a business guiding to falling bookings and rising legal costs feels early to me. I’d want Q3 bookings at the top of guidance and a Q4 outlook that shows the decline narrowing.
Roblox reports after the close on October 29. Bookings per daily user and the Q4 guide will tell us whether the reset is finished.
So what is Roblox stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Roblox could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!