Key Takeaways
- Qualcomm will notify employees of global, performance-based job cuts starting in November, but CEO Cristiano Amon’s memo gave no headcount.
- Handset revenue fell 20% to $5.09 billion last quarter, while automotive revenue jumped 61% to $1.59 billion.
- Q4 EPS guidance of $2.05 to $2.25 trails the $2.36 consensus, and Apple revenue is fading faster than planned.
- The November 4 report should reveal the size of the cuts and whether custom silicon wins lift December quarter guidance.
Qualcomm wants a leaner company before its data center bets start paying.
Qualcomm (QCOM) will cut jobs worldwide in what CEO Cristiano Amon called a “performance-focused reduction.” Notifications begin in November, right after annual employee reviews.
The memo gave no headcount. Qualcomm had about 52,000 employees at the end of fiscal 2025, so even a few percent would touch thousands of people.
Shares closed at $180 on Monday, up 2.1% as AI-linked chip stocks rallied. Still, the stock had gained only 1.5% this year as of last week, while the Philadelphia Semiconductor Index was up nearly 60%.
That gap is the real backdrop for this memo.
Cuts start right after reviews
Amon tied the reductions to performance and skills. “As we have expanded the business, so have the competencies and skills we require,” he wrote to staff.
He also said the cuts would address situations where the company “has consistently fallen short of expectations.”
Here is what we know so far:
- Notifications start in November and cover Qualcomm’s global workforce.
- Qualcomm booked $70 million of restructuring charges in fiscal Q3.
- Non-GAAP R&D and SG&A expenses totaled about $2.59 billion in that quarter.
What we do not know is the size. So the savings remain a guess until management puts a number on them.
Spending has climbed for years, and R&D is where any real savings would have to come from…
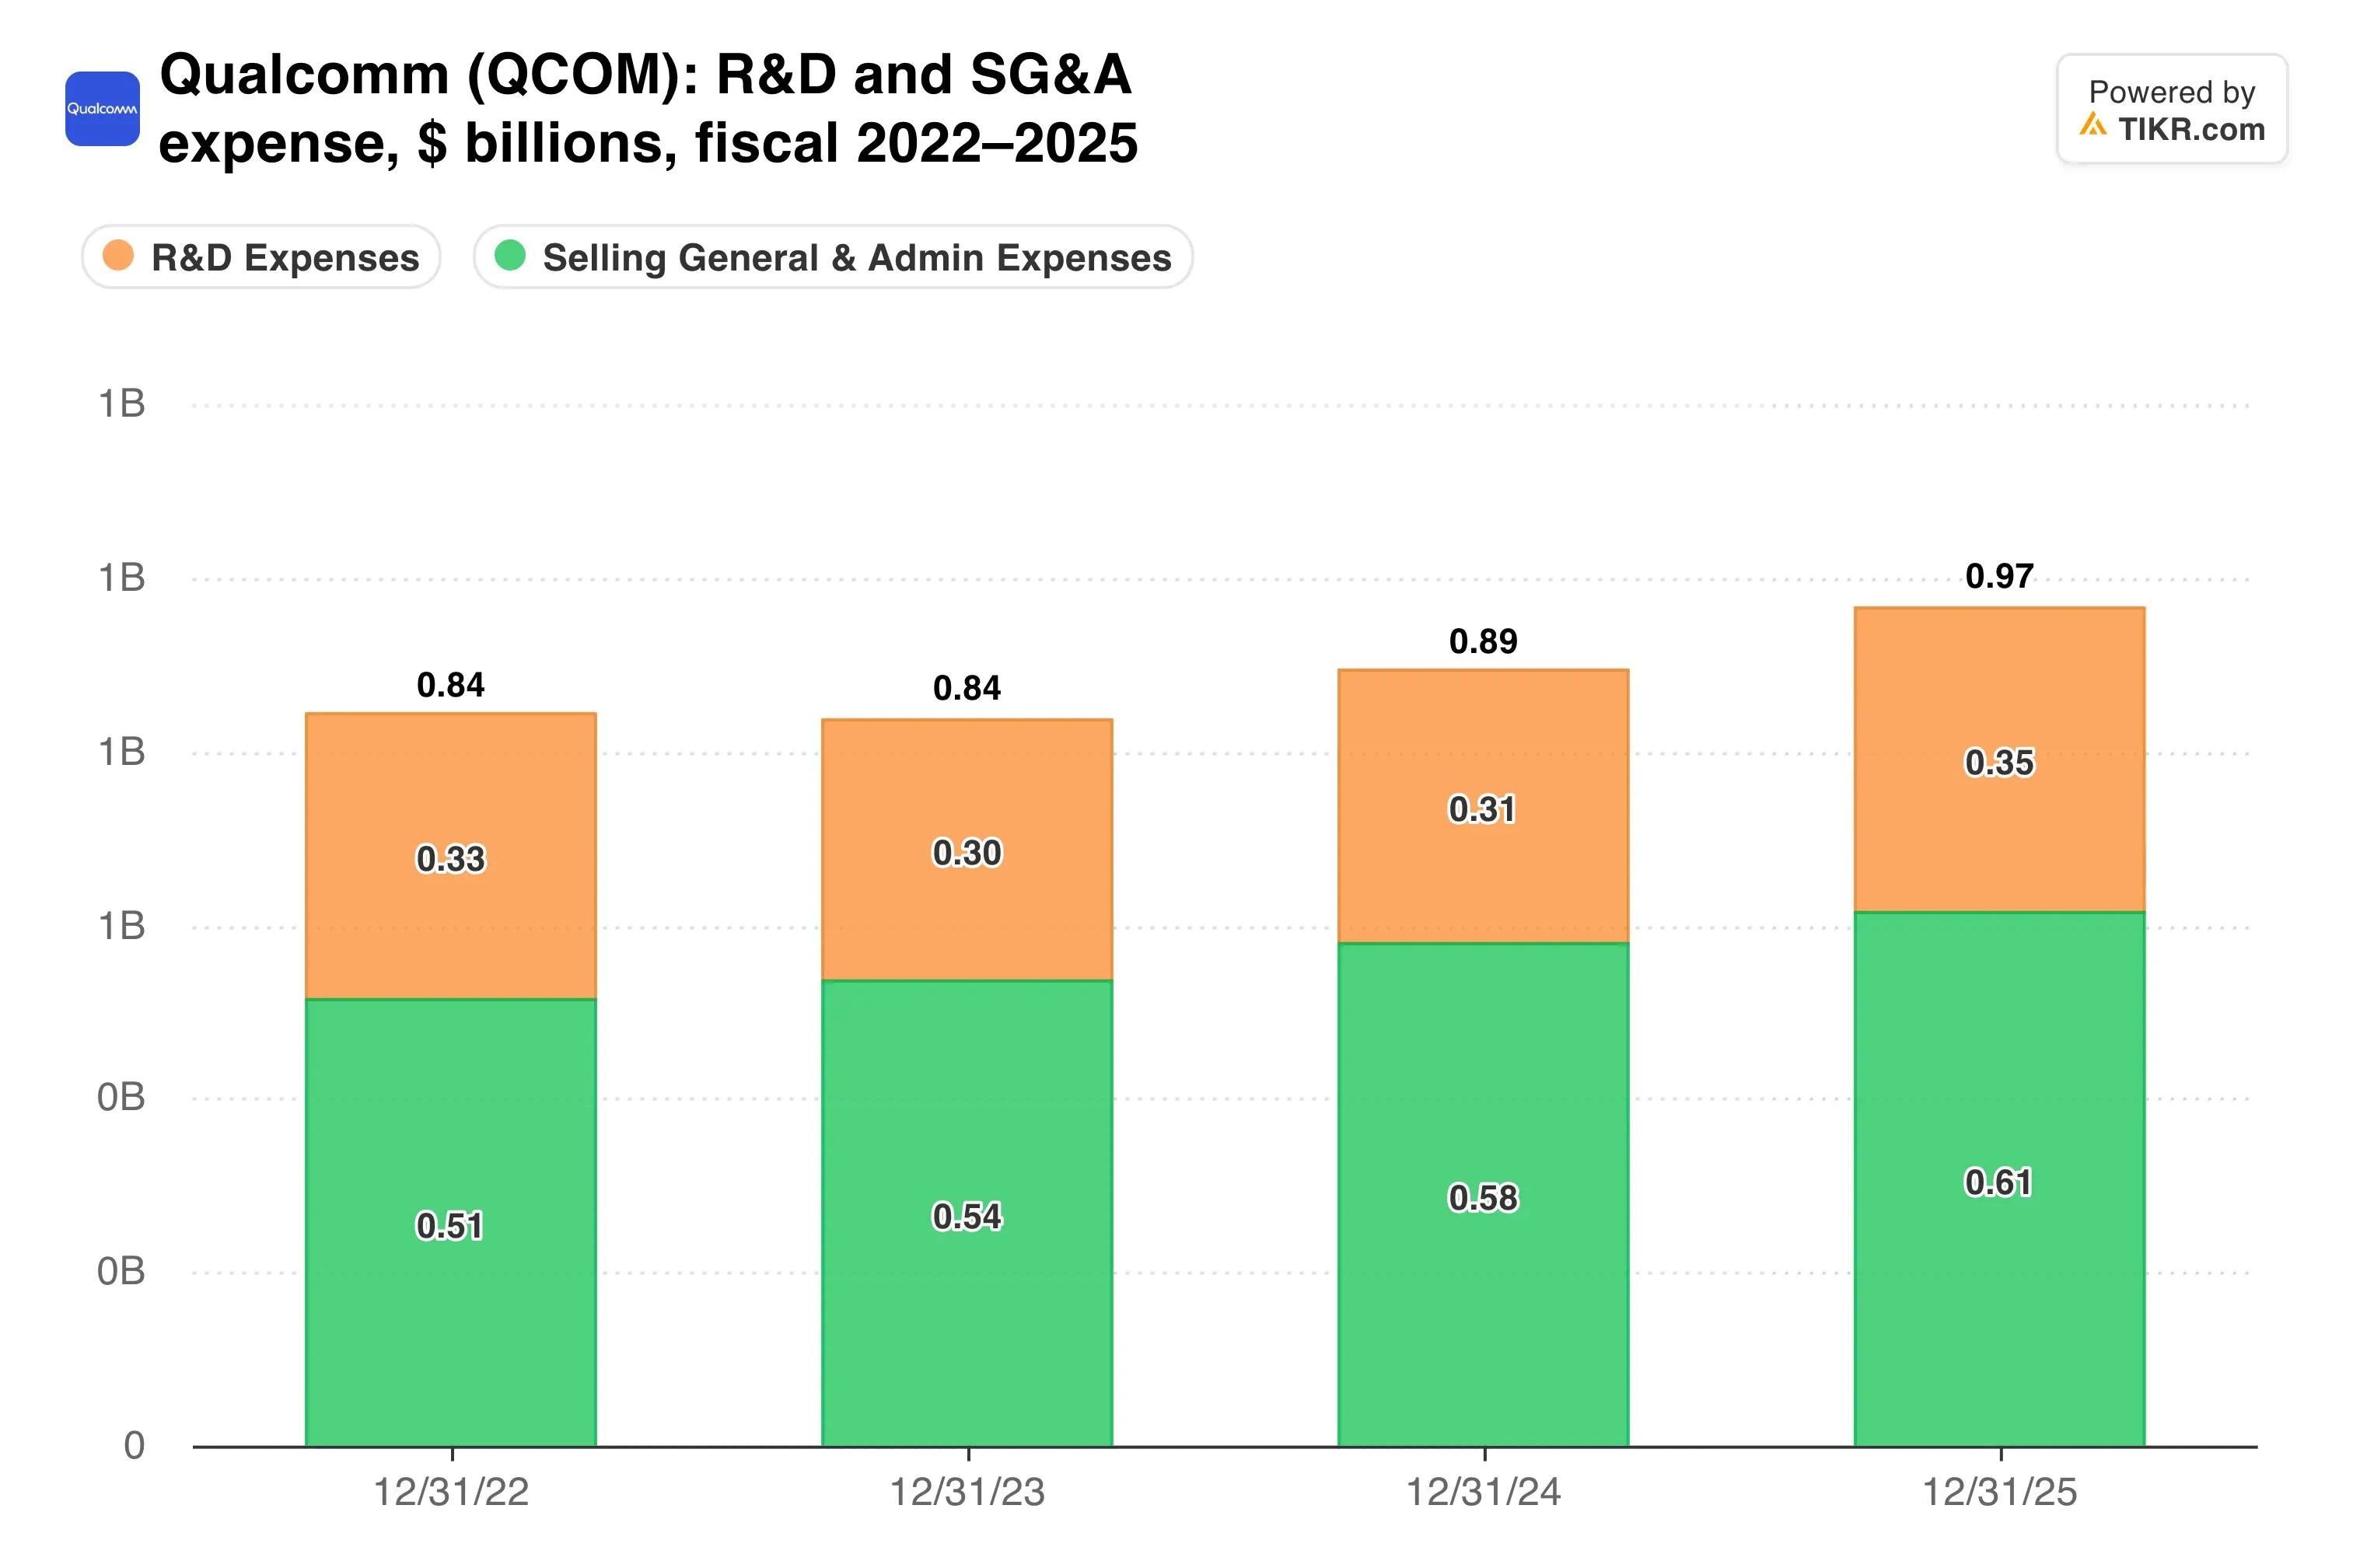
Trimming that line without slowing the data center push is the balancing act.
Cars and servers carry the load
The urgency sits in the segment mix. Handset revenue fell 20% to $5.09 billion in fiscal Q3, while automotive revenue jumped 61% to $1.59 billion and IoT grew 9%.
Apple (AAPL) is part of the drag. Qualcomm now expects its share of the next iPhone launch to land materially below its earlier 20% estimate, and Apple revenue is stepping down faster than planned.
Management’s answer is the June Investor Day target of $40 billion in non-handset revenue by fiscal 2029, roughly double the prior goal. Amon said non-handset growth should accelerate “from 24% in fiscal 2026 to greater than 60% in fiscal 2027.”
Two custom silicon wins are also slated to generate revenue in the December quarter. And a Delaware jury found Arm Holdings (ARM) breached its license agreement with Qualcomm, although damages came to just $2.
Automotive alone now equals about 31% of quarterly handset revenue.
TIKR tracks 37 analysts on Qualcomm. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Qualcomm, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Qualcomm’s Analyst Ratings
Earnings still have to bottom
The near term is soft. Qualcomm guided fiscal Q4 revenue to $9.7 billion to $10.5 billion, below the $11.3 billion it posted a year earlier.
EPS guidance of $2.05 to $2.25 also trails the $2.36 consensus. Analysts expect EPS to decline about 8% a year over the next two years.
Wall Street’s estimates show the dip before any rebound.
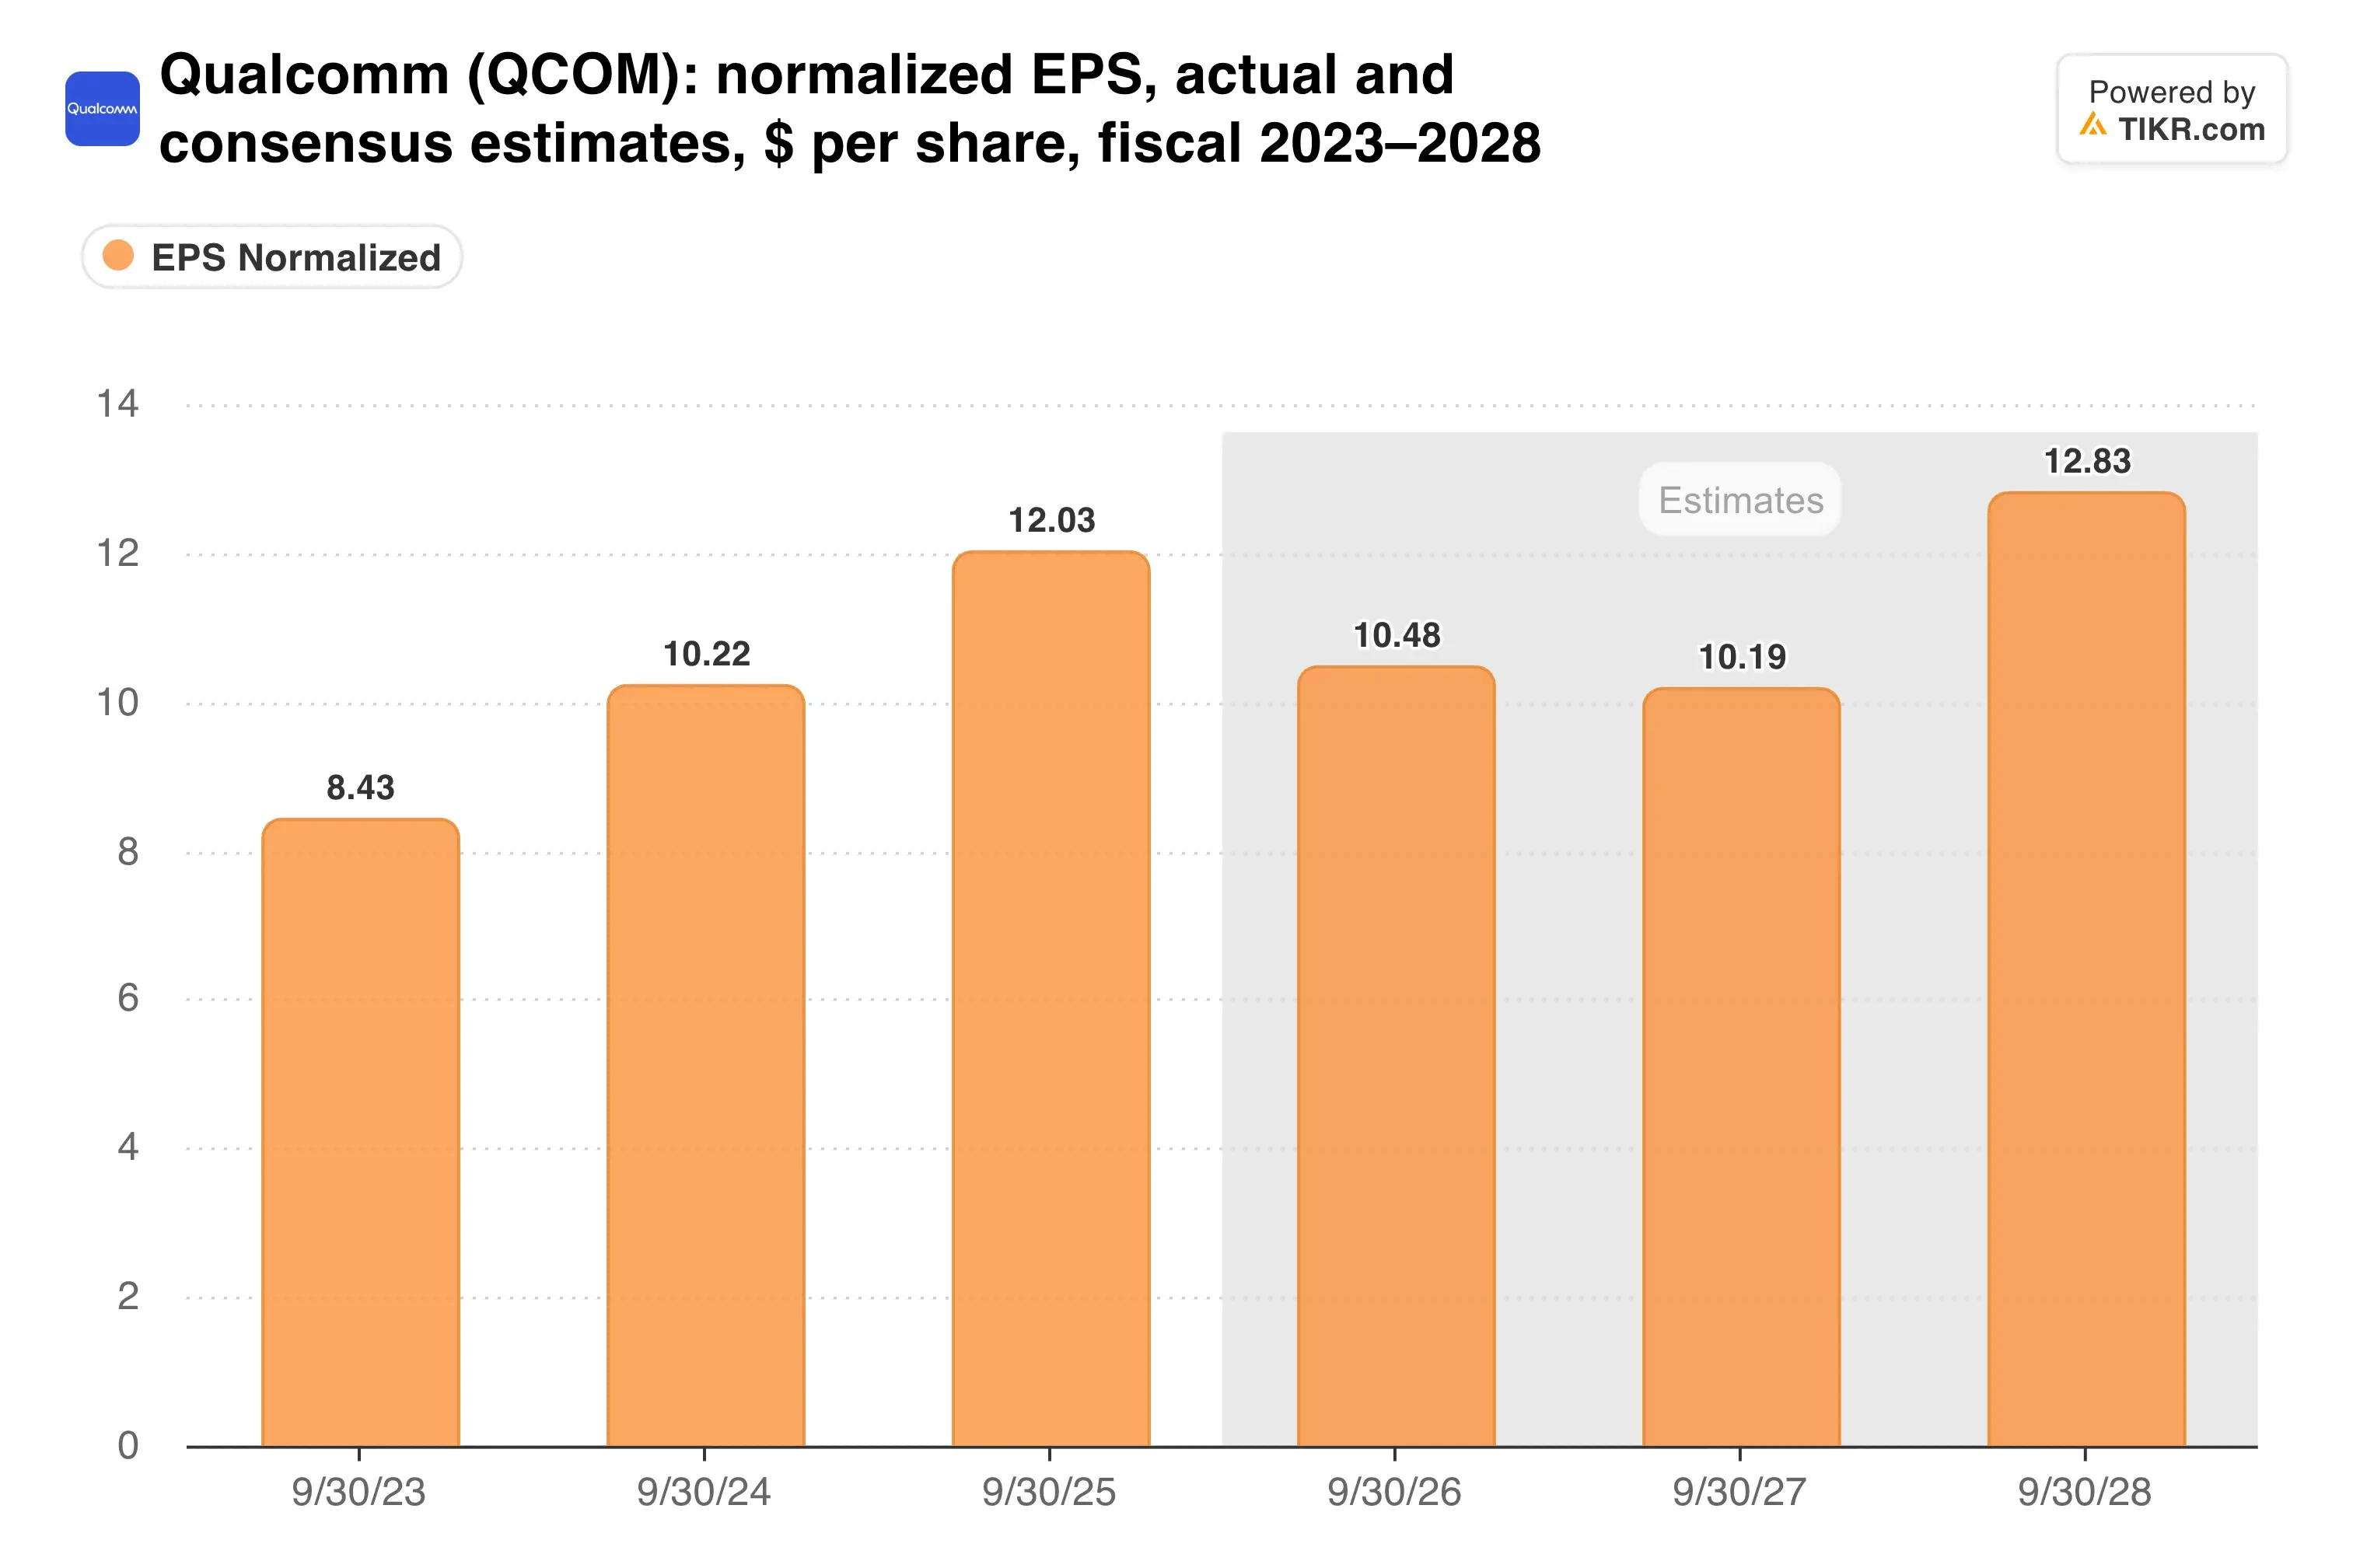
That trough is what holds the multiple at 19.4x forward earnings.
The stock sits about 31% below its 52-week high of $260, and the average Street target of $196 implies roughly 9% upside. Qualcomm still returned $2.3 billion to shareholders last quarter, including $1.4 billion of buybacks.
My take: The layoffs look like sensible housekeeping, and 19.4x is a fair price for a company in the middle of a transition. Cost cuts alone cannot replace Apple revenue, though. I want to see the custom silicon wins show up in December quarter revenue before treating the $40 billion target as more than a slide.
Qualcomm reports fiscal Q4 results on November 4. Watch for a headcount figure, the restructuring charge, and whether December quarter guidance finally shows non-handset growth outrunning the handset decline.
So what is Qualcomm stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Qualcomm could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!