Key Takeaways
- Methanex jumped 14% today after third-quarter adjusted EPS of $3.69 beat the $2.86 analysts expected.
- Lost Middle East supply kept methanol prices high, and Methanex expects a stronger fourth quarter.
- LyondellBasell expects a slow return to normal, while Celanese expected its windfall to fade.
- Analysts expect earnings to more than halve by 2028, but Methanex is paying off debt and buying back up to 5% of its shares.
Methanex (MEOH) stock is up 14% today after its third-quarter results beat estimates.
The supply crunch has helped other chemical makers too. LyondellBasell (LYB) is up (an admittedly more modest) 5% after its own report this morning. And Celanese (CE), another methanol maker, reports early next week.
The details
Methanex earned $3.69 of adjusted EPS, against $2.86 expected. CEO Rich Sumner said in the release: “The Middle East conflict’s dramatic impact on the methanol industry persisted through the third quarter, with the significant loss of industry supply supporting ongoing pricing strength.”
It expects a higher realized price and EBITDA this quarter.
Analysts already see the peak
Going into the report, analysts expected normalized EPS to peak at about $10 this year and more than halve by 2028:
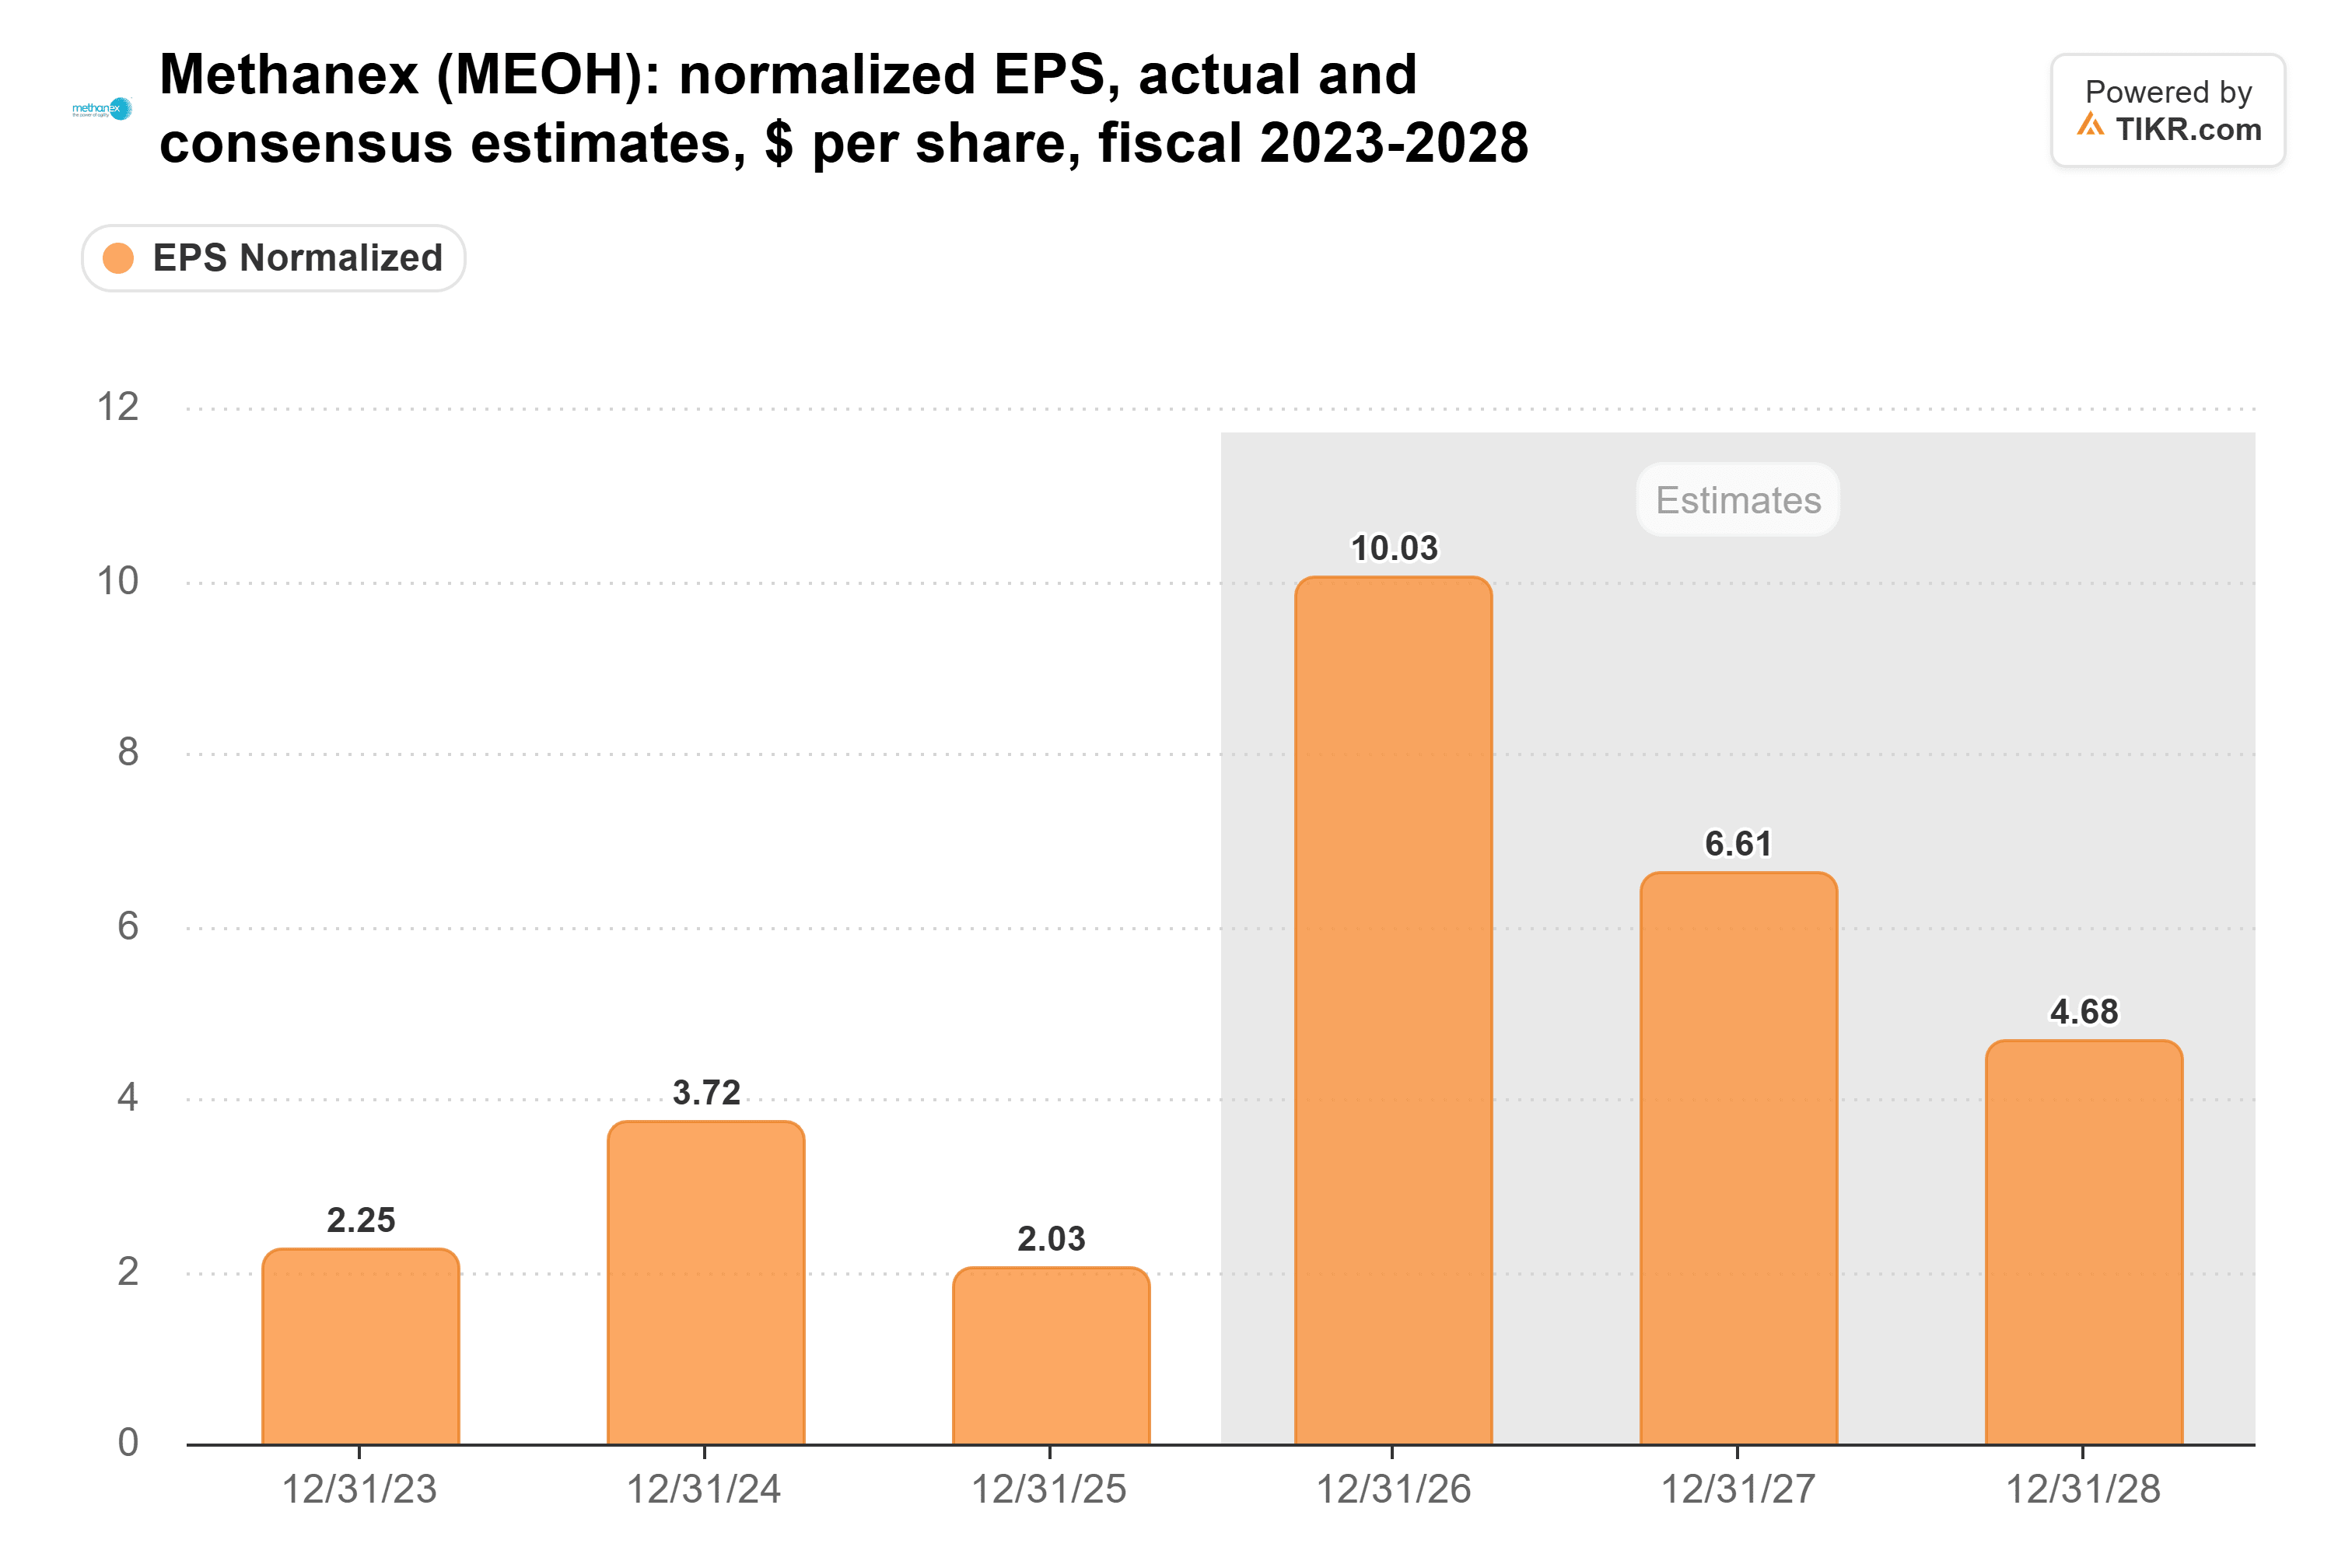
With $7.90 already earned through September and a stronger fourth quarter ahead, this year’s estimate looks likely to rise.
LyondellBasell’s outlook today supports that view: it expects any return to pre-conflict conditions in the Middle East to be uneven and slower than anticipated. Its adjusted EBITDA jumped to $1.51 billion from $835 million a year earlier, led by oxyfuels.
Celanese expected the opposite. CEO Scott Richardson said in August, after higher prices lifted its second quarter, “we expect continued moderation of supply-related opportunities.” We’ll see next week whether that windfall held up like Methanex’s.
Methanex traded at 6.6x forward earnings at Thursday’s close, about half its five-year average of 13x.
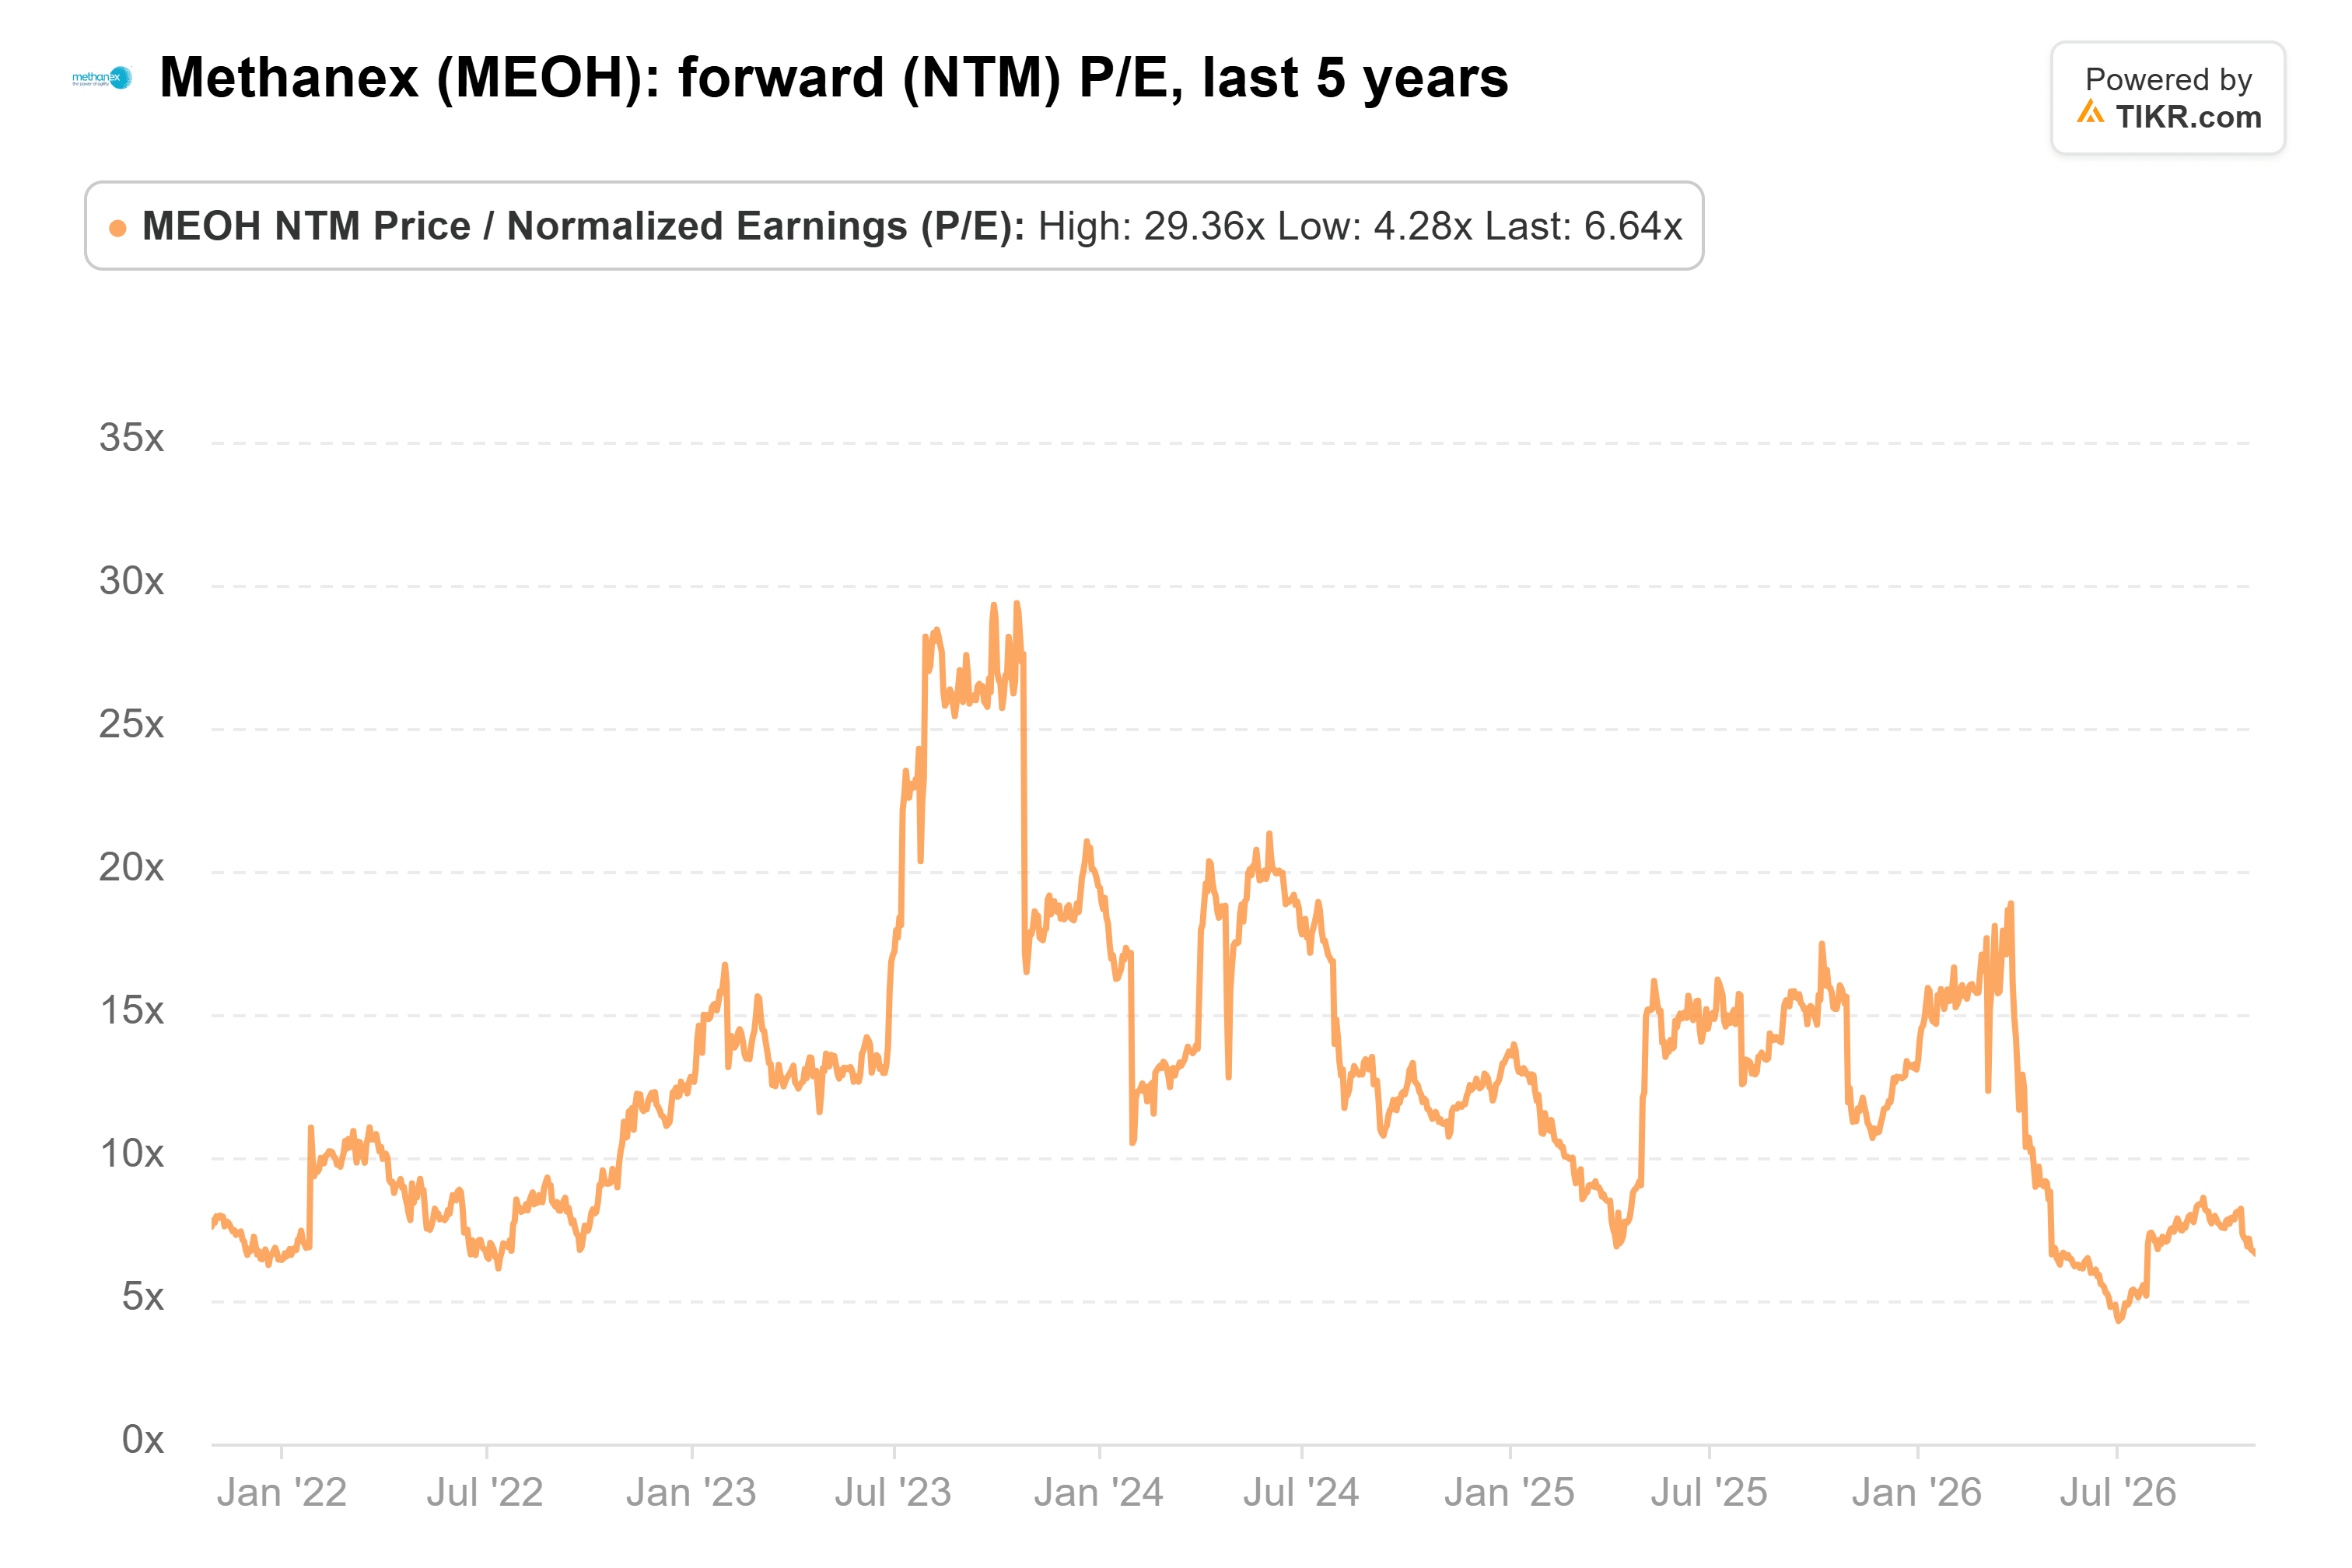
At today’s price, it’s a bit higher.
TIKR tracks 10 analysts on Methanex. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Methanex, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Methanex’s Analyst Ratings
Cashing in while it lasts
Free cash flow hit $622 million in the third quarter, the most in at least two years:
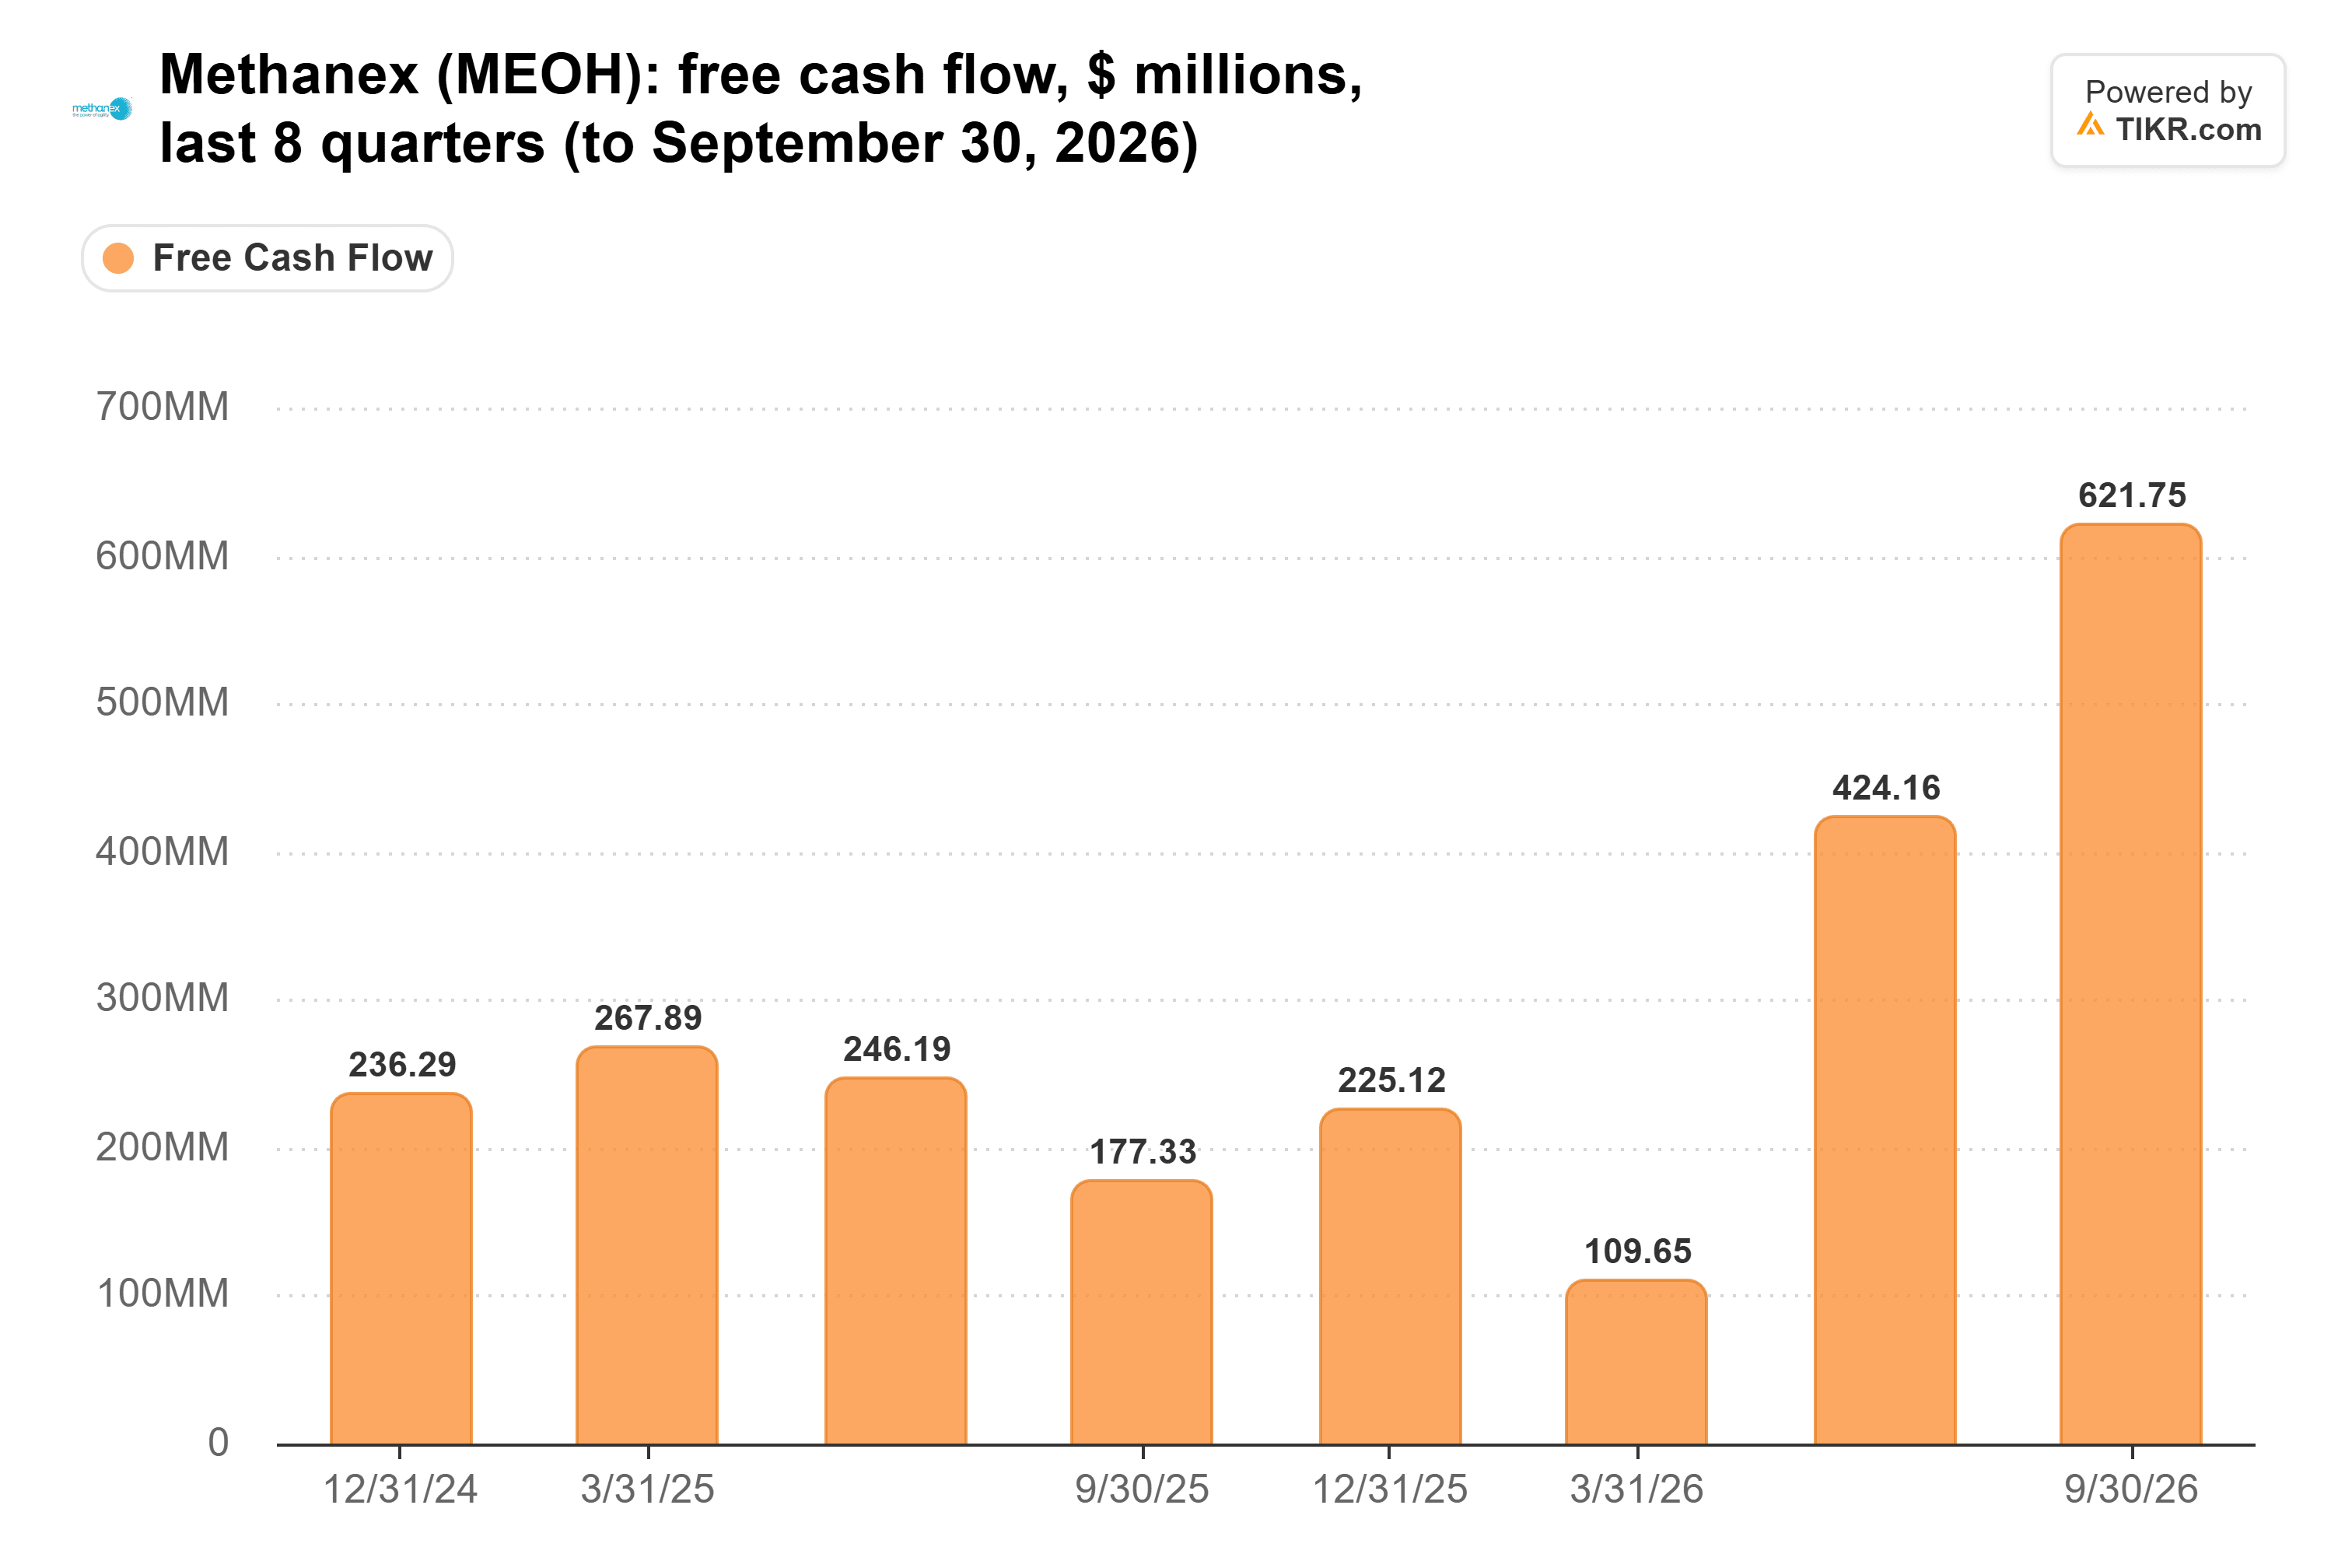
With that and $912 million of cash at September’s end, Methanex redeemed $300 million of its $700 million of 2027 bonds and plans to pay off the rest this quarter.
The way I see it, the market is underestimating how long high methanol prices can last. And when they fall, Methanex will have less debt and fewer shares to show for them.
Of course, prices could fall faster if Middle East supply returns quickly. The fourth-quarter report will show how much of the premium held.
So what is Methanex stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Methanex could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!