Key Stats for Mastercard Stock
- Current Price: $635.70
- Target Price (Mid): ~$1,055
- Street Target: ~$676
- Potential Total Return: ~66%
- Annualized IRR: ~13% / year
What Happened?
Mastercard (MA) gained 4.16% on October 29 after its third-quarter report beat estimates. New CFO Ling Hai, on his first earnings call in the role, said part of that beat was timing: services projects and deal signings moved from the fourth quarter into the third. The $635.70 close topped the October 22 record of $633.21. Visa and American Express were up about 2% each that afternoon, per Reuters, while Mastercard was up more than 4%.
A Beat With a Fourth-Quarter Offset Built In
Net revenue reached $9.81 billion, up 14% year over year, against a $9.66 billion Street estimate. Adjusted EPS of $5.31 topped the $5.17 consensus, with $0.16 coming from share repurchases. Value-added services grew 19% on a currency-neutral basis, and the payment network grew 11%.
Hai said revenue ran above expectations “primarily due to the continued strength of our business and the timing of both services projects and payment network deals.” When JPMorgan’s Tien-Tsin Huang asked whether anything was one-time, Hai called the strength broad-based, then added: “You will see a similar offset in Q4.”
He flagged two more fourth-quarter headwinds:
- Rebates and incentives will take a larger share of gross assessments than in the third quarter.
- Pricing will see some lapping.
Analysts expect fourth-quarter normalized EPS of around $5.18, up about 9%. That’s against a tough comparison, since last year’s fourth quarter beat estimates by 12%. Their revenue estimate of around $9.97 billion implies roughly 13% growth as reported. Management’s guide calls for the high end of low double digits on a currency-neutral basis, with currency subtracting about 1 percentage point.

October started steady. Hai said spending in the first three weeks stayed strong, with U.S. switched volume improving as the Capital One debit migration laps and recent commercial wins ramp.
Cross-border was softer. Volume grew 11% in the third quarter, and cross-border card-not-present growth outside travel slowed to 15% from 20% in the second quarter. Hai tied that mostly to lower-yielding intra-Europe flows, including a new EU customs fee, and said higher-yielding cross-border volume held stable.
TIKR tracks 39 analysts on Mastercard. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Mastercard, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Mastercard’s Analyst Ratings
What the Price Now Has to Carry
CEO Michael Miebach also pointed to a new OpenAI partnership: “with OpenAI this quarter, we signed a broad strategic partnership that includes the use of Agent Pay and goes well beyond.” He gave no financial terms. He also said Mastercard will not support one-time virtual cards as a long-term fix for AI checkout, and is pushing for fully tokenized transactions instead. Separately, Pinnacle Financial Partners’ entire issuing portfolio moves onto the network starting in 2027.
Analysts raised targets after the print: Goldman Sachs to $743 from $716, and Raymond James to $726 from $632 and JPMorgan to $755 from $720. All three sit above TIKR’s Street mean of about $676 as of October 29. TIKR’s ratings data from that date also shows one Underperform that was not there on September 30.
TIKR Advanced Model Analysis
- Current Price: $635.70
- Target Price (Mid): ~$1,055
- Potential Total Return: ~66%
- Annualized IRR: ~13% / year
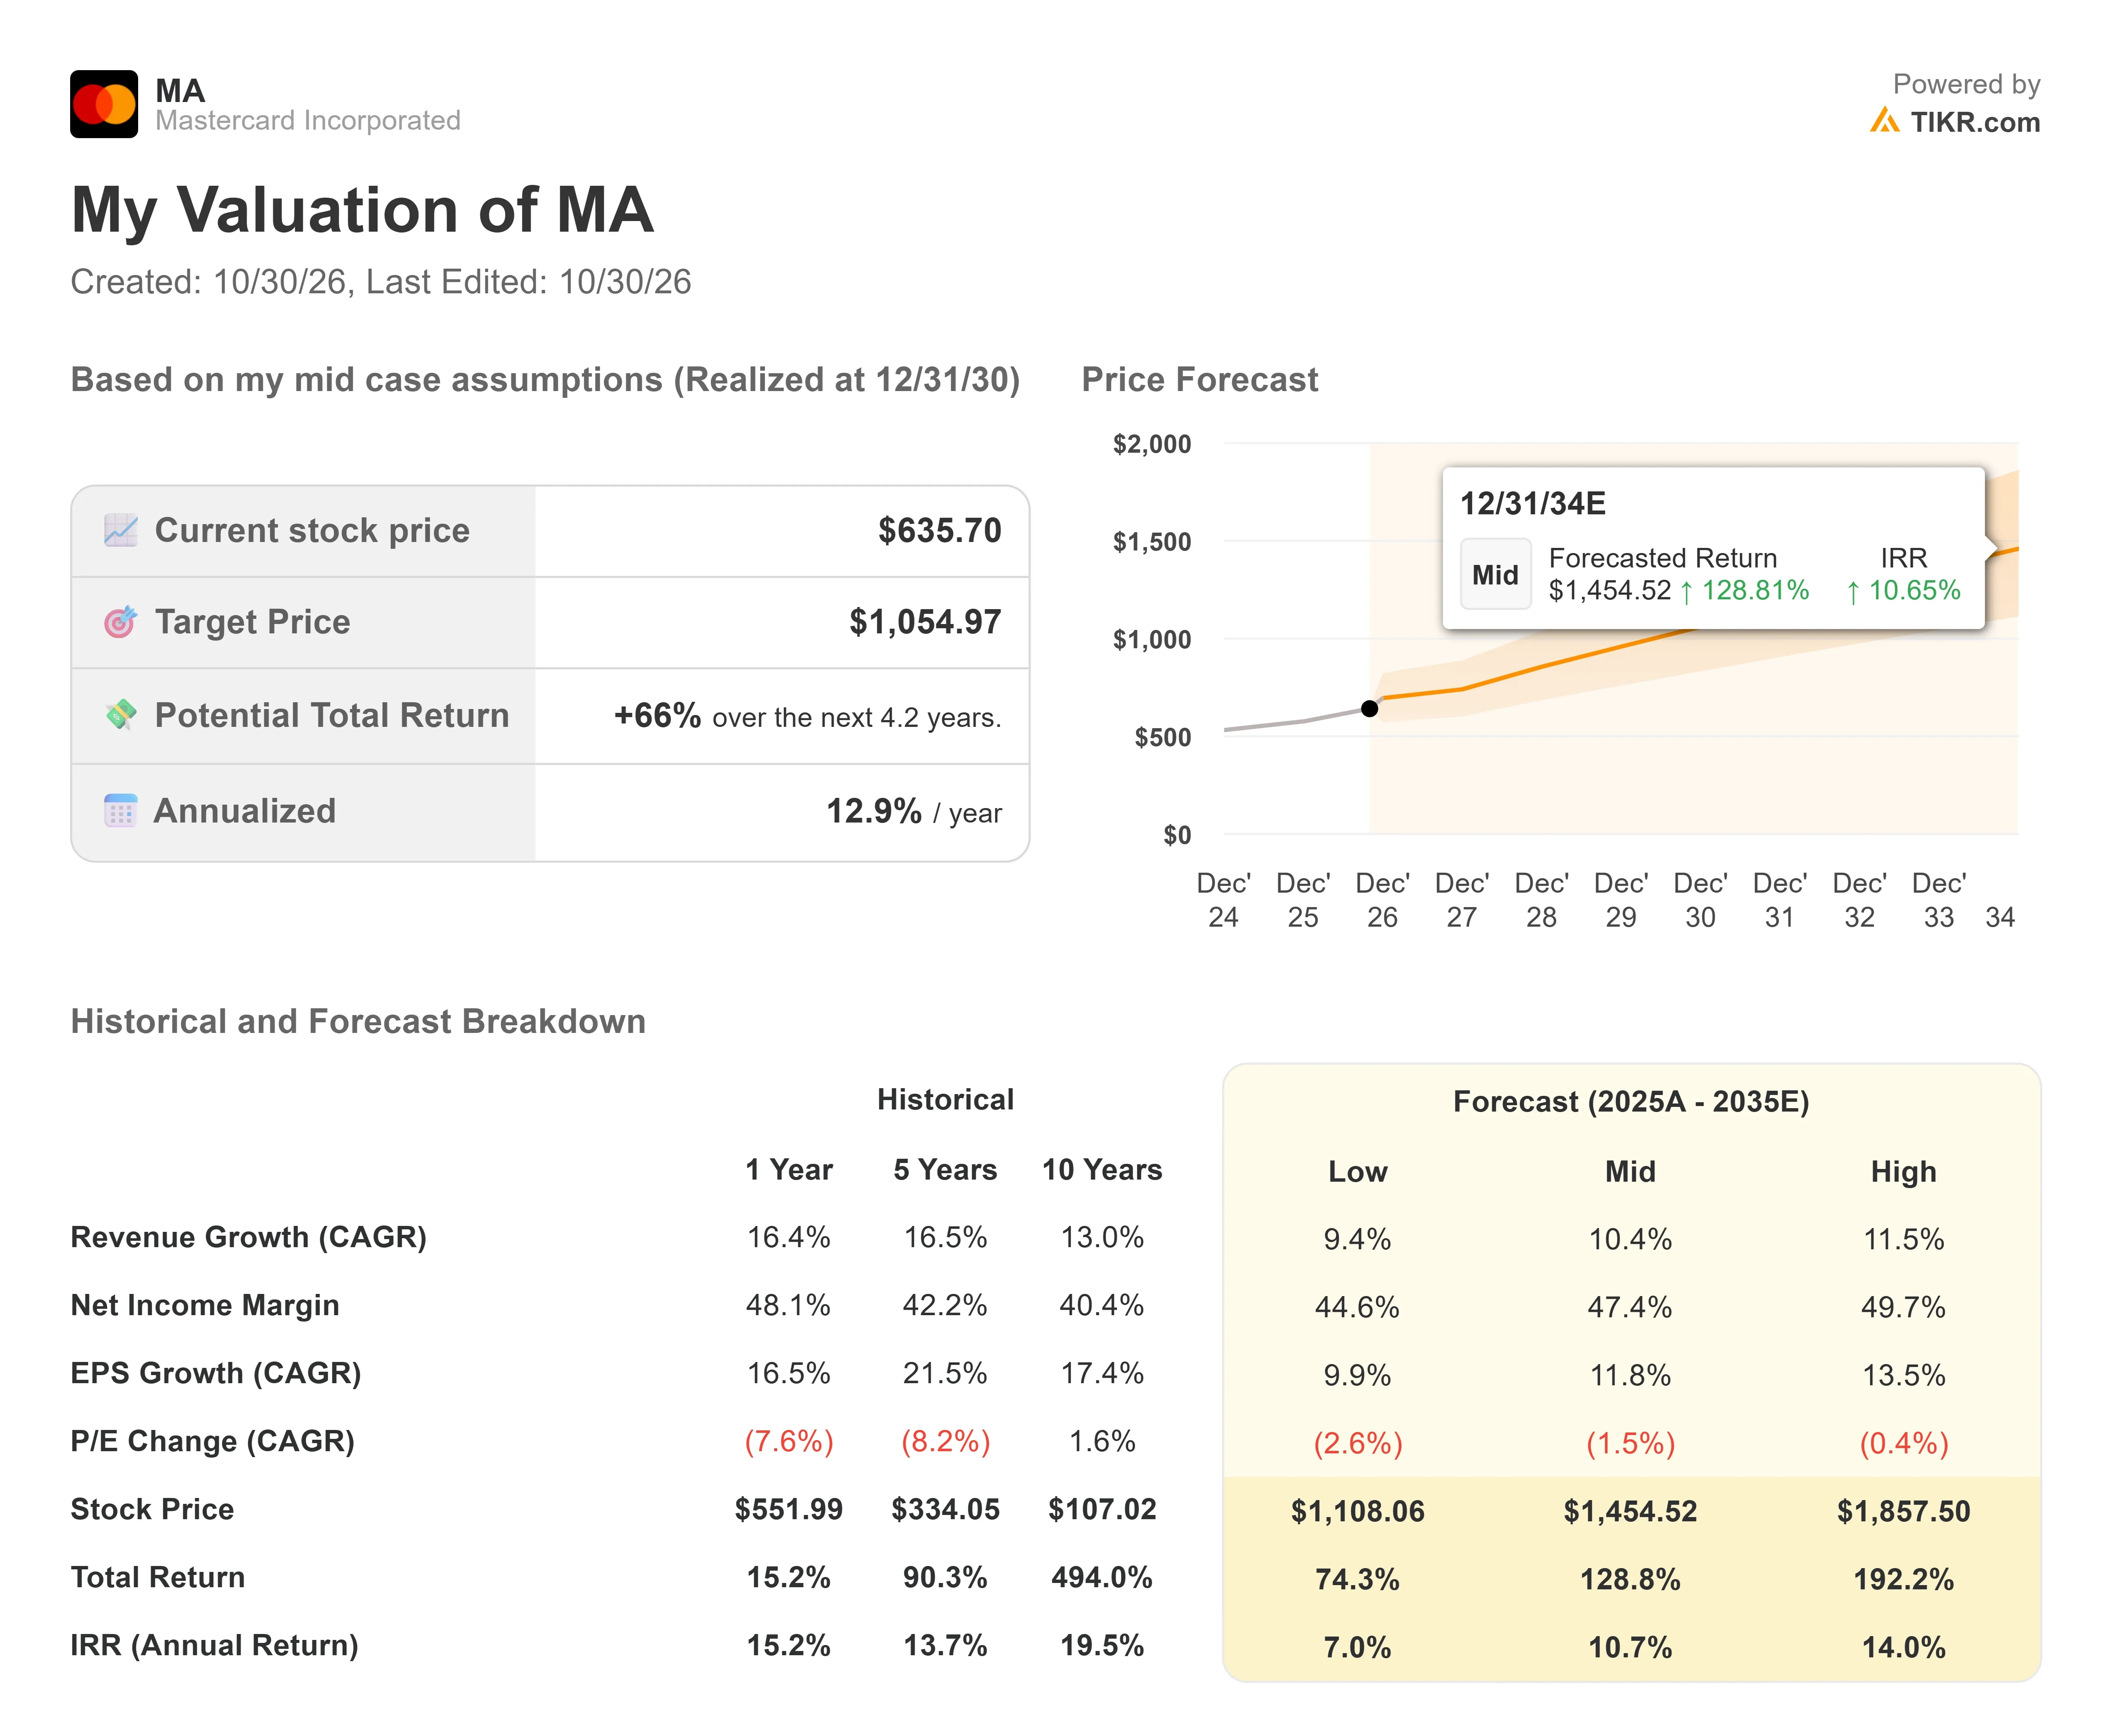
The mid case is used because its net margin of about 47% sits close to the 48.1% one-year historical figure on the model card. The TIKR model projects about $1,055 by December 31, 2030. That’s around 66% above $635.70, or about 13% a year over 4.2 years.
Revenue grows about 10% a year over the model’s 2025 to 2035 forecast, below the 13% pace of the past decade. Services (up 19% this quarter) and cross-border assessments (up 16%) are the two revenue lines that would have to carry that. The P/E slips about 1.5% a year, so earnings growth does the work.
The high case’s roughly 11.5% growth would lift the result. The low case’s roughly 9% growth and 45% margin would shrink it.
Conclusion
Mastercard reported last year’s fourth quarter on January 29. Its next report also brings its first formal 2027 guidance, which Hai promised for that release. Revenue near the roughly $9.97 billion consensus despite the timing reversal would show the record rests on the business. A clear miss, after a 4% jump to a record, would show how much of the third quarter came from timing.
So what is Mastercard stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Mastercard could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Analyze Mastercard on TIKR Free →
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!