Key Stats for Intel Stock
- Current Price: $92.07 (October 29, 2026 close)
- Q3 Adjusted EPS: $0.52 (vs. $0.40 consensus)
- Q4 Revenue Guide: $15.0 billion to $16.0 billion
- Q4 Gross Margin Guide: 38% (non-GAAP)
- Street Target: ~$118 (October 29 mean, before post-earnings cuts)
What Happened?
Intel Corporation (INTC) reported third-quarter revenue of $16.513 billion on October 29, up 20.95% and in line with estimates, and adjusted EPS of $0.52 against the $0.40 consensus, per TIKR. It then guided fourth-quarter revenue to $15.0 billion to $16.0 billion, below TIKR consensus of around $17.1 billion. Shares closed at $92.07 that day, fell more than 20% after hours, and were down 25.4% at $68.68 in Friday premarket trading, per Benzinga.
CFO David Zinsner expects client revenue to fall more than 20% sequentially as PC makers cut inventory amid memory shortages. An October 14 accident at Fab 28 in Israel costs about $300 million of fourth-quarter revenue on an early assessment, with a similar hit likely in the first quarter. Overshadowed in the selloff was the segment CEO Lip-Bu Tan calls Intel’s fastest-growing, and management’s choice to accept thinner margins to grow it.

Custom Chips Are Intel’s Fastest Grower
Tan said purpose-built silicon, custom chips built for specific customers, is “tripling over the last 3 years, and poised to triple again over the next few years.” Zinsner said its revenue grew more than 50% sequentially and more than doubled year over year, though he still counts it among businesses with “relatively modest revenue today.”
It sits inside data center and AI (DCAI), where revenue rose nearly 80% to $7.3 billion. Intel guides DCAI up mid-teens sequentially in the fourth quarter, with purpose-built silicon growing faster, and Zinsner said it is “part of what’s driving a lot of the growth in the fourth quarter.”
Tan named AI labs as potential customers and said Intel will offer “fully modular, verified instances” of its x86 CPUs for custom workloads.
Intel Is Trading Margin Percentage for Gross Profit
Intel guides a 38% non-GAAP gross margin for the fourth quarter, down from 44.1% in the third. Zinsner put the drop mainly on lower revenue against fixed factory costs, plus about 200 basis points from Fab 28 and a mix shift led by purpose-built silicon.
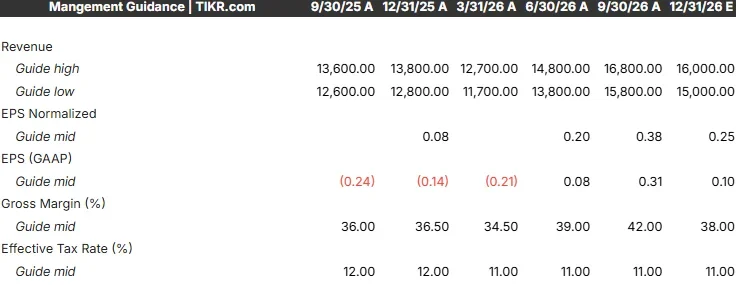
He said the custom chip business is “kind of in its early stages, its margins are below the corporate average,” calling it a headwind “which is, I think, a positive viewed the right way.” He added that “Lip-Bu and I really decided to focus on driving the gross profit,” which “may put a little pressure on the operating margin percentage through next year.”
TIKR tracks 50 analysts on Intel. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Intel, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Intel’s Analyst Ratings
What Consensus Still Assumes
Granite Rapids server chips are now margin accretive and Intel 18A costs are down about 40% since the first quarter, though Panther Lake PC chips remain below the corporate average. Zinsner said he still leans toward a 40% to 60% fall-through, meaning that share of added revenue reaching gross profit, which should expand gross margin in a growth year. TIKR consensus, which still had fourth-quarter revenue near $17.1 billion, shows:
- 2026 Gross Margin: ~42%
- 2027 Gross Margin: ~44%
- 2030 Gross Margin: ~54% (only six analysts publish 2030 revenue estimates)
- 2027 Revenue: ~$73 billion
- Ratings (October 29): 13 Buy, 1 Outperform, 32 Hold, 5 No Opinion, 1 Underperform, 1 Sell

The 2027 step-up depends on that rule holding while lower-margin custom chips grow fastest, the same mix pressure TIKR flagged in October for packaging. Analysts are already resetting: BofA’s Vivek Arya downgraded the stock to Neutral and cut his target to $100 from $145.
Intel’s next update comes in January. Fourth-quarter gross margin at or above 38%, with purpose-built silicon still outgrowing DCAI, would show Intel can grow custom chips without stalling the margin recovery analysts expect in 2027.
So what is Intel stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Intel could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!